The Secret to Conquering Auto Financing Without Getting Scammed
Buying a car is one of the most exciting yet stressful financial milestones in adult life. Whether you are shopping for a sleek brand-new sedan, a spacious family SUV, or a dependable pre-owned vehicle, the thrill of stepping into a new ride is undeniable. However, behind the glossy showroom paint and the fresh new-car smell lies a complex financial decision that can impact your monthly budget for years to come. I remember walking onto a busy car dealership lot a few years ago with stars in my eyes, completely unprepared for the high-pressure finance office. My lack of preparation cost me dearly when I walked out with an inflated interest rate and a loan package loaded with hidden fees I did not understand. That painful mistake taught me that walking in blind is the fastest way to drain your bank account and lose your peace of mind.
Imagine you are sitting across from a fast-talking dealership finance manager after hours of exhausting test drives. The paperwork looks like an endless maze, and they start throwing complex numbers, high-pressure warranties, and confusing monthly payment options at your face. It is completely normal to feel overwhelmed, anxious, and tempted to just sign whatever document they slide across the desk. You want to drive your new car home today, but deep down, that nagging fear tells you that you are making an expensive mistake.
The pressure to close the deal makes your stomach turn, leaving you exhausted and entirely on your own against corporate sales tactics. You want to make a smart choice, but the aggressive atmosphere makes it nearly impossible to think straight or read the fine print. Unscrupulous lenders use complicated financial jargon to hide predatory rates, trapping everyday consumers in cycles of long-term automotive debt. Many buyers fall victim to dealership tricks simply because they lack clear guidance on how vehicle financing truly operates behind closed doors.
Let us look at a different approach. Meet Sarah, a working teacher who needed a reliable vehicle to commute to her school every single day. Sarah refused to rush into a bad deal; instead, she checked her credit profile, secured bank pre-approval beforehand, and walked onto the lot as a confident buyer. She bypassed all the dealership smoke and mirrors, saving thousands of dollars in interest and fees.
You deserve that exact same safety, clarity, and control when you purchase your next vehicle. That is why learning the truth about auto loan financing is so empowering for your personal budget. Let us step away from the stress and explore the actual facts together.
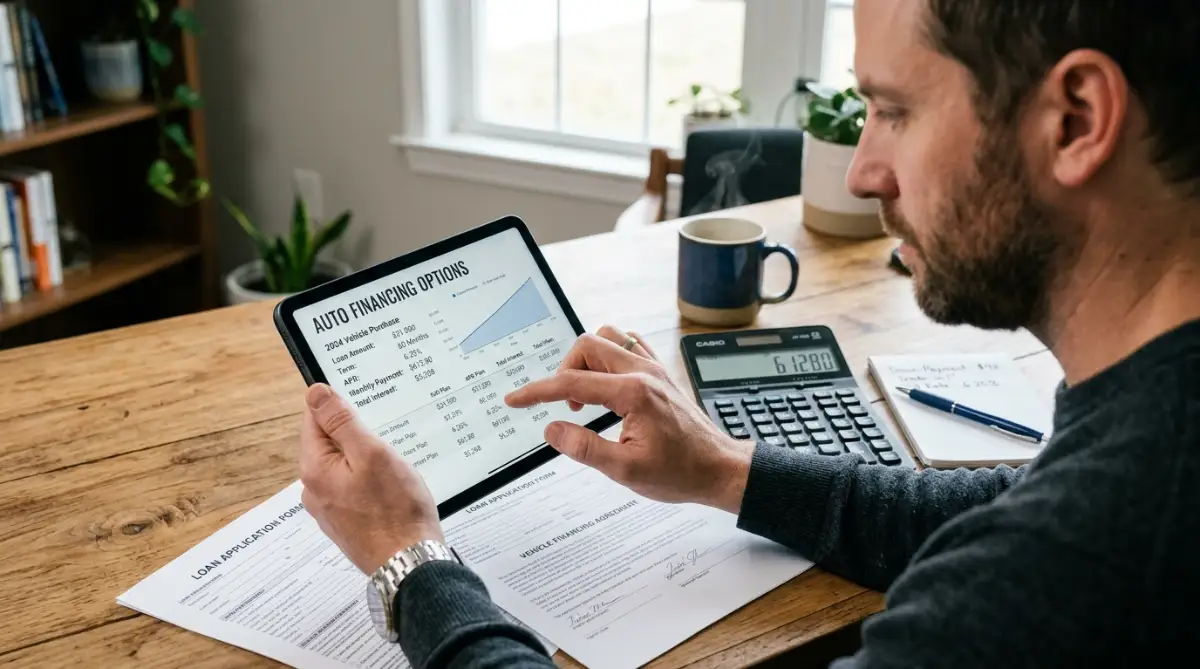 Mastering the Core Pillars of Auto Loan Financing
Financing a car breaks down into three core moving parts that dictate your financial reality: the total amount borrowed, your annual interest rate, and the length of the loan. Understanding how these elements interact prevents you from getting trapped in a bad financial contract.
Part 1: The Total Amount Borrowed
The amount you borrow includes the actual price of the vehicle, plus government taxes, registration fees, and any prior loan balances you are rolling over. Never pay full sticker price or buy expensive dealer add-ons because those items inflate your principal balance unnecessarily.
Part 2: Securing Your Interest Rate
Your interest rate determines how much extra money you pay the bank just for borrowing their cash. Excellent credit scores or a qualified co-signer will help you unlock the lowest possible interest rates available on the market.
Part 3: Controlling Your Loan Length
The length of your loan determines how many months you will make payments. While longer terms lower your monthly bill, they dramatically increase the total interest you pay over time.
Myth vs Reality: Auto Financing
Myth: "You have to finance your car through the dealership where you buy it."
Reality: You can secure a loan independently through a credit union or online bank before visiting the lot, giving you total leverage over the dealer.
Comparing Your Auto Financing Options
My Personal Pro Tip: Early on, I made the mistake of letting a car dealer run my credit through six different lenders in one afternoon, which caused my score to drop due to multiple hard inquiries. Once I learned to use independent bank pre-approvals first, I could shop around safely without damaging my credit profile or getting tricked by inflated dealer rates. Always secure your own financing before stepping foot on a car lot to keep your financial standing completely protected.
Watch this quick video to discover how auto loans work and how to choose the right lender for your next vehicle purchase!
Advanced Strategies to Save Thousands on Your Vehicle Purchase
Once you grasp the basic framework of auto loans, you can utilize advanced techniques to protect your wallet. Getting a great auto loan requires the same careful preparation as buying a home or managing major credit accounts. One of the most effective strategies is checking your credit health well before you start shopping. You can review guidelines on how to improve your credit score to ensure your report looks immaculate to lenders.
A cleaner credit profile opens doors to tier-one interest rates that save you a small fortune over a 60-month term. Another smart move is organizing your financial documents into a single folder, including recent pay stubs and tax returns. Being organized proves to lenders that you are a reliable borrower who handles obligations with discipline. If you are balancing student debt alongside your car search, you might also want to research federal vs private student loans to see how different borrowing structures affect your overall debt-to-income ratio.
When you walk into negotiations with pre-approved financing from a credit union, you hold all the cards. Dealerships hate pre-approvals because it stops them from padding your monthly payment with hidden interest markups. Make sure you also evaluate your total insurance costs before signing final papers. Upgrading to a luxury vehicle often causes insurance premiums to spike drastically, catching many buyers off guard. For related insights on managing household risk, check out tips on how to choose your first home insurance policy without unnecessary anxiety.
Furthermore, timing your purchase strategically can yield massive savings. Dealerships often offer aggressive discounts and manufacturer incentives at the end of the month, quarter, or calendar year. Sales representatives are eager to hit their quotas during these windows, making them far more willing to negotiate vehicle prices downward. Combine these seasonal savings with your independent bank pre-approval, and you create an unbeatable purchasing formula.
Finally, always remember to keep a cash buffer for unexpected maintenance costs after the purchase. Even a brand-new car requires routine upkeep like oil changes, tire rotations, and annual registration renewals. Setting aside a dedicated automotive maintenance fund ensures that minor service bills never disrupt your household budget. By staying disciplined and executing these advanced steps, you turn a stressful purchase into a smooth, empowering victory.
 Traps and Blind Spots That Destroy Your Car Buying Power
When you are excited about buying a new vehicle, it is easy to become impatient and skip vital financial checks. Dealership finance departments are engineered to maximize profit, and they rely on common consumer blind spots to close expensive contracts.
The Danger of Stretching Loan Terms to 84 Months
Many buyers fall for the trap of choosing 72 or 84-month loan terms just to get a lower monthly payment. While the monthly bill looks smaller, you end up paying thousands of extra dollars in total interest.
Extended loans also cause you to become upside down on your vehicle quickly. Because cars depreciate fast, you will owe more than the car is worth for a longer period of time.
Falling for Expensive Dealer Add-Ons
Finance managers love pitching overpriced extended warranties, paint sealants, GAP insurance, and tire packages inside the F&I office. These items carry massive markups and are rarely worth their retail price tag.
If you need GAP insurance or an extended service contract, purchase them independently through your auto insurer or manufacturer. You will save hundreds of dollars while avoiding dealership padding.
Simple Do's and Don'ts for Auto Financing
- Do check your credit report for errors and dispute them before shopping.
- Do get pre-approved by a credit union or bank before visiting a dealer.
- Do aim for a down payment of at least 10% to 20% to lower your principal.
- Don't focus exclusively on the monthly payment while ignoring the total loan price.
- Don't accept extended 84-month loan terms that balloon your interest costs.
- Don't buy unnecessary dealership add-ons during the final paperwork phase.
Your Daily Action Checklist: Reclaiming Control of Your Auto Purchase
Taking control of your automotive financing is not about making massive sacrifices overnight. It is about taking small, deliberate steps that protect your hard-earned money and keep your financial future secure.
- Pull Your Credit Report: Review your score online and check for any reporting errors before applying for loans.
- Shop Local Credit Unions: Apply for pre-approved financing through a member-owned institution to secure lower rates.
- Save Your Down Payment: Set aside a comfortable cash buffer to cover 10% to 20% of your target vehicle's purchase price.
- Stick to a 60-Month Limit: Choose a repayment term of 60 months or fewer to minimize total interest payments.
Looking back at my own early mistakes in the dealership finance office, I realize how crucial financial literacy truly is. My personal journey taught me that true confidence comes from preparation, patience, and refusing to be rushed into bad debt. I want you to feel that same absolute freedom when you drive off the lot in your next car. Stay strong, keep your standards high, and take that very first step toward smart financing today.
Recommended Reading Resources
Explore these internal guides to master your overall financial strategy:
- How to Improve Your Credit Score Before Applying for a Mortgage
- Federal vs Private Student Loans Guide
- How to Choose Your First Home Insurance Policy Without Stress
Frequently Asked Questions
Is it better to get pre-approved for an auto loan?
Yes, getting pre-approved gives you strong negotiating leverage and protects you from paying inflated dealership interest rate markups.
What is a good loan term for a used car?
A loan term of 36 to 48 months is ideal for used vehicles to prevent you from paying excessive interest on a depreciating asset.
How much down payment should I put on a car?
Financial experts generally recommend putting down at least 10% for used vehicles and 20% for new cars to avoid negative equity.
Can I refinance my auto loan later?
Yes, if your credit score improves or market interest rates drop, you can refinance your auto loan to secure a lower monthly payment.
Are dealership add-ons refundable?
Many dealer add-ons like extended warranties or service contracts can be canceled and refunded pro-rata if reviewed and handled promptly.
Disclaimer: Navigating a major purchase is challenging, but you have the power to protect your wallet with the right steps. Take your time, trust your preparation, and enjoy peace of mind on the road ahead. The information provided in this article is for educational and informational purposes only. It should not be taken as professional financial, investment, or legal advice. Always consult with a certified financial planner or advisor before signing major lending agreements.