The Fear of Choosing the Wrong Mortgage
Purchasing a home is one of the most defining milestones in your adult life. It represents true independence and creating a safe sanctuary where your family can build lasting memories. But as you enter the pre-approval process, the sheer volume of financial jargon can quickly turn excitement into dread.
I still remember the absolute panic I felt when I applied for my first mortgage. My credit score was not perfect, and my savings account felt incredibly small compared to the massive home prices in my local area. Sitting across from the loan officer, my heart pounded as he casually threw around terms like "Conventional" and "FHA."
I was completely terrified that making the wrong choice would cost me thousands of dollars in hidden mortgage insurance fees. The fear of getting rejected or trapped in an unaffordable monthly payment kept me awake for weeks. I felt like I was navigating a maze completely blindfolded.
Finally, I decided to take a deep breath and educate myself on how these two specific loan programs actually functioned. Learning the simple math behind these options gave me the total confidence I needed to secure a loan that perfectly fit my budget. Understanding these rules proved to me that you do not need to be a Wall Street banker to make a smart home buying decision.
When financing a residential property in the United States, prospective homebuyers face a wide array of mortgage products. However, the vast majority of residential home purchases are financed through two primary loan categories. These are Conventional Loans and FHA Loans.
Both loan options serve the same fundamental purpose of providing buyers with capital. However, their underlying underwriting standards, down payment rules, and mortgage insurance structures differ dramatically. Choosing between a Conventional or FHA mortgage is about selecting a financial product that matches your unique long-term wealth goals.
Decoding Conventional and FHA Home Loans
A Conventional Loan is a private mortgage that is not directly insured by any federal government agency. Instead, these mortgages conform to guidelines established by Fannie Mae and Freddie Mac. Because they lack government backing, private lenders absorb higher financial risks if a borrower defaults.
Consequently, lenders enforce stricter credit score and income stability standards for conventional loan applicants. On the other hand, an FHA Loan is a government-backed mortgage insured directly by the Federal Housing Administration. The FHA does not lend money directly, but rather provides federal insurance to approved private lenders.
If an FHA borrower defaults, the federal government reimburses the lender for their losses. This powerful government guarantee allows lenders to offer highly flexible underwriting terms. It opens the door to homeownership for first-time buyers or individuals recovering from past credit challenges.
Mortgage Rules: Myth vs. Reality
- Myth: You must have a full 20% down payment to buy a house with a conventional loan.
- Reality: First-time buyers can secure a conventional loan with as little as 3% down.
- Myth: FHA loans are only meant for low-income buyers.
- Reality: FHA loans have no income limits and are used by buyers of all income levels to maximize leverage.
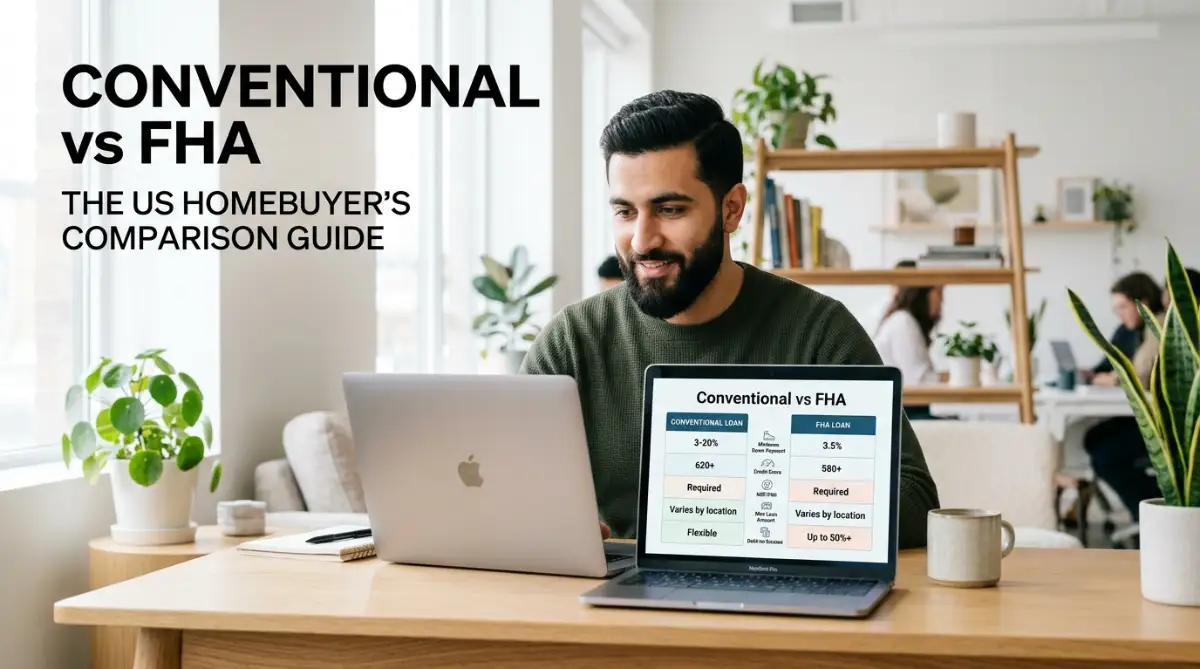
Conventional vs. FHA Quick Comparison
My Personal Pro Tip: Before I even walked into a bank, I pulled my free credit reports and paid down a few small credit card balances. Boosting my score by just 15 points pushed me into a higher credit tier, which instantly qualified me for a much cheaper conventional interest rate. I highly recommend optimizing your credit profile at least six months before applying!
Watch this detailed video guide featuring mortgage experts breaking down the key differences between these loans:
Advanced Tips: Mortgage Insurance, Appraisals, and Debts
The true long-term cost difference between Conventional and FHA loans rests almost entirely in their mortgage insurance policies. If you put down less than 20% on a Conventional loan, you must pay Private Mortgage Insurance (PMI). Conventional PMI is strictly risk-based, meaning borrowers with excellent credit scores pay much lower monthly premiums.
Most importantly, Conventional PMI is highly flexible and completely cancelable over time. Under federal law, your lender must automatically drop your PMI once your loan balance reaches 78% of the original home value. You can also request an early cancellation if your home value appreciates significantly.
FHA loans mandate a completely different insurance structure called the Mortgage Insurance Premium (MIP). You must pay an upfront fee equal to 1.75% of your total loan amount right at closing. You also pay an ongoing monthly fee for the entire 30-year lifetime of the loan if you put down less than 10%.
The only way to ever eliminate FHA MIP is to eventually refinance into a Conventional loan. This makes optimizing your financial profile extremely important from the start. Knowing how to improve your credit score before applying for a mortgage gives you the option to choose a Conventional loan and skip lifelong FHA fees.
Both loan programs require an independent real estate appraisal, but their safety standards differ wildly. Conventional appraisals focus primarily on establishing fair market value compared to neighborhood sales. They ensure basic structural soundness without enforcing strict minor cosmetic rules on the seller.
FHA appraisals, however, enforce extremely strict government safety, security, and soundness standards. FHA appraisers actively inspect for peeling lead-based paint, missing handrails, and electrical hazards. Sellers are completely required to repair all noted FHA deficiencies before the deal can close.
Conventional loans also offer broad property versatility for ambitious buyers. They allow you to easily purchase primary residences, secondary vacation homes, or investment rental properties. FHA loans are strictly restricted to owner-occupied primary residences only.
Your Debt-to-Income (DTI) ratio plays a massive role in which loan you can secure. Managing your existing personal loan installments and credit card balances is essential to preserving your qualifying power. You must balance your existing debt payments against your new projected housing costs.
Evaluating your monthly debt load is similar to understanding federal vs private student loans how to choose wisely to keep your family financially secure. Lenders generally cap Conventional DTI ratios at 43% of your gross income. FHA guidelines are far more forgiving, regularly approving DTI ratios up to 50% or even 55% for applicants with strong compensating factors.
Finally, your monthly housing payment will include your hazard insurance premium. Understanding how to choose your first home insurance policy without stress helps keep this specific cost very low. The less you pay for insurance, the more house you can afford to buy under your lender's DTI limits.
Common Mistakes Homebuyers Make During Pre-Approval
A widespread mistake buyers make is assuming they are automatically locked into one loan type forever. If you start with an FHA loan because of a low credit score, you are not trapped. You can absolutely refinance into a Conventional loan a few years later once your credit improves and you build equity.
Another massive pitfall is forgetting to budget for the FHA Upfront Mortgage Insurance Premium (UMIP). This 1.75% fee is usually rolled directly into your total loan balance at closing. This instantly increases your monthly payment and eats into your initial home equity from day one.
Many buyers also fail to understand how strict FHA appraisals can ruin a real estate deal. If you are trying to buy a heavily discounted "fixer-upper" home that needs major repairs, an FHA loan will likely be denied. Sellers often refuse to accept FHA offers on distressed properties because they do not want to pay for the mandatory repairs.
Lastly, ignoring your credit utilization in the months leading up to your application is a terrible idea. Maxing out credit cards drops your score quickly, potentially forcing you out of a cheap Conventional loan and into an expensive FHA loan. Always keep your credit card balances as close to zero as possible before underwriting.
Take the Next Step Toward Your New Home
Neither Conventional nor FHA mortgages are universally superior across the board. Each loan product is carefully engineered for specific homebuyer profiles and financial situations. If you possess a high credit score and want cancelable mortgage insurance, a Conventional loan offers significant long-term savings.
If you have a lower credit score or a higher debt load, an FHA loan provides a highly powerful lifeline into homeownership. Work closely with an experienced mortgage broker to run side-by-side payment comparisons. Seeing the real numbers on paper makes the decision process incredibly simple.
As I look back on my own stressful homebuying journey, I am extremely grateful I took the time to weigh my mortgage options before signing those final closing papers. Securing the right loan gave me total peace of mind and kept my family financially safe. I hope this guide empowers you to make the absolute best financial choice for your family's beautiful future.
Internal Links Integration Check
- Successfully linked: How to improve your credit score before applying for a mortgage.
- Successfully linked: Federal vs private student loans how to choose wisely.
- Successfully linked: How to choose your first home insurance policy without stress.
Frequently Asked Questions
Can I switch from an FHA loan to a Conventional loan later?
Yes, you can absolutely refinance your FHA loan into a Conventional loan in the future. Homeowners usually do this once they reach 20% equity in their property and improve their credit score. Refinancing allows you to eliminate the permanent FHA mortgage insurance premium entirely.
Do FHA loans have higher interest rates than Conventional loans?
FHA loans typically offer slightly lower base interest rates than Conventional loans because they are backed by the government. However, the mandatory FHA mortgage insurance premiums often make the total monthly payment higher. You must always compare the Annual Percentage Rate (APR) to see the true cost.
Can I buy an investment property with an FHA loan?
No, FHA loans are strictly reserved for primary, owner-occupied residences. However, you can use a strategy called "house hacking" by purchasing a multi-family property (up to 4 units). As long as you live in one of the units as your primary home, you can rent out the others.
What happens to PMI if my home value goes up?
If you have a Conventional loan, rising property values can help you cancel your Private Mortgage Insurance (PMI) much faster. Once your home appreciates enough to give you 20% equity, you can request a new appraisal. If the appraisal confirms the new value, your lender will drop the PMI charge.
Can I use gift money for my down payment?
Yes, both FHA and Conventional loans allow you to use monetary gifts from family members for your down payment. You will need to provide the lender with a formal "gift letter" stating that the money is not a loan and does not need to be repaid. The funds must be fully tracked and sourced by the underwriter.
General Informational & Legal Disclaimer
Disclaimer: The information provided in this article is for general informational, educational, and entertainment purposes only and does not constitute formal financial, real estate, tax, or mortgage underwriting advice. Reading this article or interacting with this website does not establish a professional-client or fiduciary relationship. Mortgage lending guidelines (Fannie Mae, Freddie Mac, HUD/FHA rules), conforming loan limits, credit score requirements, and mortgage insurance premium rates vary over time and across different US states, counties, and lending institutions. If you are preparing to buy a home, you should consult directly with a licensed mortgage loan officer, certified financial planner, and real estate attorney in your area to receive guidance tailored to your specific financial situation.