The Fear and Freedom of Your First Rental Property
I vividly remember the overwhelming fear I felt right before buying my first rental property. I spent countless nights staring at listings, completely paralyzed by the thought of losing my hard-earned savings.
My mind constantly raced with terrible worst-case scenarios. I worried about dealing with destructive tenants or paying for a sudden, expensive roof replacement entirely out of pocket.
It felt like I was standing on the edge of a financial cliff. However, staying stagnant was simply not an option if I wanted to build real generational wealth.
Eventually, I realized that relying entirely on my emotions was the root cause of my intense anxiety. Once I learned to trust objective math and clear cash flow formulas, my fear completely disappeared.
I bought that first duplex, and depositing that first rent check changed my entire financial life. Purchasing your very first investment property is one of the most exciting financial milestones you will ever achieve.
It represents the defining shift from relying solely on earned income to building long-term wealth that works while you sleep. Yet, taking that initial step into residential real estate investing can evoke intense fear of the unknown.
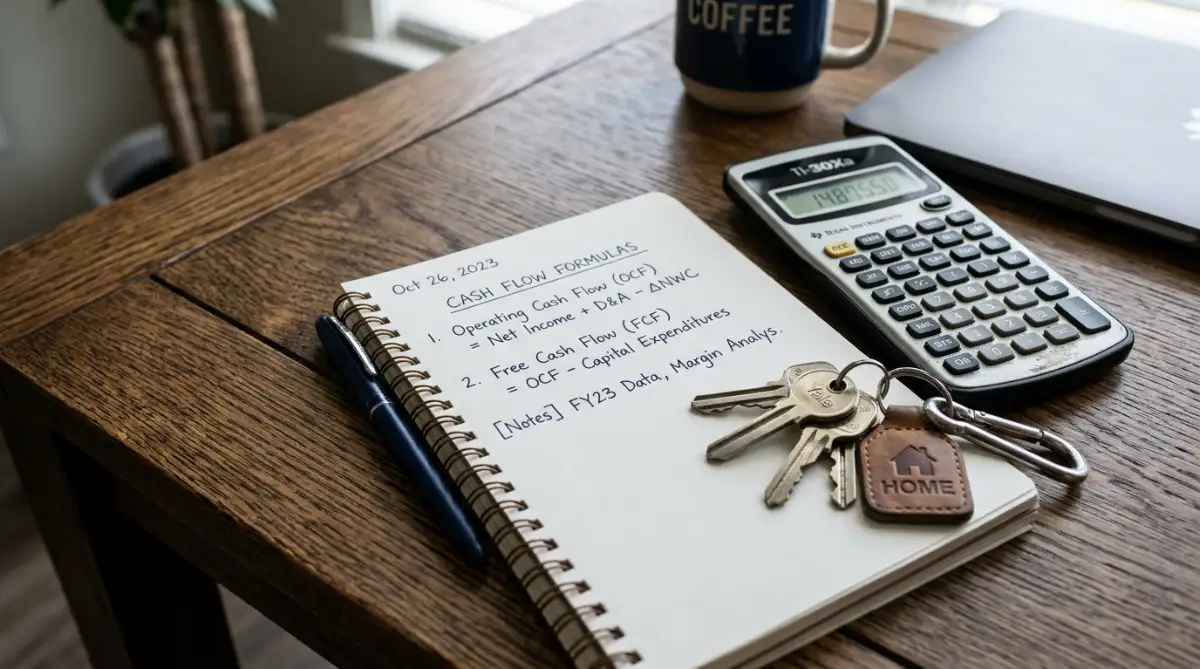
You worry about whether your cash flow calculations are correct or what happens if an appliance breaks. It is essential to realize that every successful real estate investor started exactly where you are today.
Real estate investing is not reserved for multi-millionaires or Wall Street insiders. With a disciplined strategy and proper preparation, anyone can acquire income-producing property and build a lasting family legacy.
The Four Pillars of Real Estate Wealth Generation
In the United States, residential real estate has historically proven to be an incredibly consistent vehicle for long-term wealth creation. Unlike paper assets, income-producing real estate offers a unique four-fold financial return profile.
First, you generate monthly Cash Flow, which is the net income remaining after paying all operating expenses and the mortgage. Second, you benefit from Principal Paydown, meaning your tenants systematically build your equity by paying off your loan.
Third, real estate offers massive Tax Advantages, allowing you to deduct mortgage interest, repairs, and paper depreciation against your rental income. Finally, Long-Term Appreciation expands your net worth as property values historically climb over multi-year periods.
Real Estate Investing: Myth vs. Reality
- Myth: You must have a 20% down payment to buy any rental property.
- Reality: You can use a 3.5% FHA loan to "house hack" a multi-family property if you live in one of the units.
- Myth: Being a landlord means fixing toilets at 2 AM.
- Reality: Hiring a professional property management company handles all tenant and maintenance emergencies for you.
Stock Market vs. Real Estate
My Personal Pro Tip: When I bought my first investment property, I made sure to open a completely separate business checking account just for the rental income and maintenance expenses. This single action saved me so much headache during tax season, and I highly recommend you do the same to protect your personal assets!
Watch this comprehensive video guide to learn exactly how to secure loan pre-approvals and analyze rental cash flow safely.
Advanced Tips: Financial Metrics and Buying Strategies
Beginner real estate investors must carefully align their strategy with their available capital and risk tolerance. Buying single-family detached homes is great for long-term stability and high resale appreciation. Conversely, small multi-family properties, like duplexes or fourplexes, generate higher gross rental yields from multiple units.
One of the best strategies for beginners is known as "House Hacking." This involves purchasing a multi-family property, living in one unit, and renting out the others to cover the mortgage. It is an exceptional way to utilize low-down-payment owner-occupant mortgages to eliminate your own housing costs entirely.
Never rely on emotional intuition when evaluating real estate deals. You must analyze potential properties using objective mathematical formulas to ensure profitability. The "1% Rule" is a quick screening method stating that monthly gross rent should equal approximately 1% of the total purchase price.
Mastering Net Operating Income and Cap Rates
Net Operating Income (NOI) is your total annual rental income minus all annual operating expenses. Operating expenses include property management, taxes, insurance, repairs, and vacancy allowances, but NOI strictly excludes your mortgage payment. Knowing your NOI allows you to calculate the Capitalization Rate (Cap Rate) to compare yields across different neighborhoods.
Securing an investment property mortgage differs significantly from securing a primary residence loan. Lenders enforce stricter underwriting standards due to higher perceived default risks on rentals. Because conventional investment loans require a 15% to 25% down payment, maintaining excellent credit is mandatory.
Just as you would research how to improve your credit score before applying for a mortgage, you must prepare your credit file months in advance. Lenders generally want to see scores above 740 to unlock the lowest interest rates. A lower interest rate dramatically increases your monthly cash flow.
Protecting Your Asset and Managing Debts
Once you close on the property, protecting the physical asset from unforeseen disasters is your top priority. Learning how to choose your first home insurance policy without stress applies directly to buying comprehensive landlord insurance. Proper coverage shields you from liability claims and severe property damage costs.
Additionally, managing your personal Debt-to-Income (DTI) ratio is critical before you apply for investor financing. Carrying high personal loan balances or credit card debt can quickly ruin your mortgage approval odds. Evaluating your debts is much like deciding between federal vs private student loans how to choose wisely to keep your monthly obligations low.
Real estate investing is absolutely a marathon, not a sprint. Taking time to build financial cushions protects your family from unexpected vacancies or emergency plumbing repairs. With proper analysis and strict debt management, you will gain the confidence needed to scale your portfolio safely over time.
Dangerous Mistakes Beginner Investors Must Avoid
Protect your hard-earned investment capital by avoiding the most common first-time real estate mistakes. The biggest trap is buying based on emotion instead of strict math. Falling in love with paint colors or granite countertops will not pay your mortgage when the property sits vacant.
Underestimating your ongoing operating expenses is another incredibly dangerous pitfall. Failing to budget for a 5% vacancy rate, routine maintenance repairs, and long-term capital expenditures will drain your cash flow quickly. Always set aside money for future roof replacements and HVAC unit repairs.
Skipping a thorough tenant screening process is a guaranteed recipe for disaster. Renting to the first friendly applicant without conducting full credit and background checks often leads to costly evictions. You must verify their employment and call their previous landlords to ensure they are reliable.
Finally, attempting to self-manage out-of-state properties is a massive headache for beginners. If your property is located hundreds of miles away, you cannot quickly verify repairs or check on the property's condition. Always hire a reliable, local boots-on-the-ground management team if you invest far from home.
Take Action and Start Building Your Legacy
Buying your first investment property requires careful strategy, mathematical clarity, and diligent execution. By selecting the right rental strategy, mastering cash flow math, and securing investor-friendly financing, you set a strong foundation. Protecting your assets with proper legal structures allows you to take complete control of your financial destiny.
Reclaiming your financial independence and building long-term wealth through real estate is a deeply rewarding journey. Deposit check by deposit check, tenant by tenant, you are creating tangible financial security for your entire future. Embrace the process, learn from the challenges, and keep moving forward.
As I look back at my own real estate journey, I am so incredibly grateful I pushed past my initial fears. Buying that first duplex taught me that financial freedom is completely possible for anyone willing to learn the numbers. I want to personally encourage you to trust your research, save your capital, and take that exciting first step toward building your legacy.
Internal Links Integration Check
- Successfully linked: How to improve your credit score before applying for a mortgage.
- Successfully linked: How to choose your first home insurance policy without stress.
- Successfully linked: Federal vs private student loans how to choose wisely.
Frequently Asked Questions
Do I need a 20% down payment to buy an investment property?
Conventional investment loans generally require a minimum 15% to 25% down payment. However, if you plan to live in one unit of a multi-family property (house hacking), you can qualify for owner-occupant financing. This allows you to put down as little as 3.5% to 5%.
What is a good cash-on-cash return for a beginner?
A solid target for a first-time investor is an annual cash-on-cash return of 8% to 12%. This metric measures the actual cash return on the money you paid out of pocket. Anything above 10% is generally considered a strong, wealth-building investment.
Should I put my rental property in an LLC?
Holding investment properties inside a Limited Liability Company (LLC) is highly recommended. It insulates your personal home, bank accounts, and other assets from potential property-related lawsuits. Always consult with a real estate attorney to set up your legal structure properly.
How do I calculate Net Operating Income (NOI)?
You calculate NOI by taking your total expected annual rental income and subtracting all your annual operating expenses. Operating expenses include property management fees, property taxes, insurance, routine repairs, and vacancy allowances. Do not include your mortgage principal and interest in this calculation.
Is house hacking a good strategy for beginners?
Yes, house hacking is widely considered the absolute best entry strategy for new real estate investors. It allows you to purchase a small multi-family property with a low down payment while tenants cover most or all of your mortgage. This strategy dramatically reduces your personal living expenses while building equity.
General Informational & Legal Disclaimer
Disclaimer: The information provided in this article is for general informational, educational, and entertainment purposes only and does not constitute formal financial, investment, tax, or legal advice. Reading this article or interacting with this website does not establish a professional-client or fiduciary relationship. Real estate market conditions, mortgage lending guidelines, landlord-tenant laws, tax statutes (including IRS Schedule E rules), and zoning regulations vary significantly across different US states, counties, and local municipalities. If you are preparing to buy an investment property, you should consult directly with a licensed real estate broker, certified public accountant (CPA), real estate attorney, and certified financial planner in your area to receive guidance tailored to your specific financial situation.