Understanding the Panic of a Sudden Cash Emergency
A few years ago, my home roof began leaking during a heavy storm, and I needed quick funds without putting my car on the line. I felt completely overwhelmed, staring at my bank account and worrying if I would ever find a safe option in time. That scary experience taught me how powerful the right guidance can be when you need cash without risking your hard-earned assets. I remember sitting at my kitchen table with water dripping into a bucket, wondering how people survived unexpected financial shocks without falling into deep debt. It took hours of research and careful phone calls to realize that safe, unsecured options actually existed for people in my exact position.
Imagine you are dealing with a sudden, stressful situation. Perhaps your family member is sick, or your roof has started leaking during a heavy storm. You need money to handle this problem immediately, but your savings account is empty.
The thought of putting your home or car at risk just to get a loan makes your stomach turn. You feel completely stuck and scared of making a bad financial move. The pressure to fix things right now leaves you feeling exhausted and entirely alone.
You want to make a smart move, but the constant worry makes it hard to think straight. You are not just looking for money; you are looking for safety and peace of mind.
The internet is overflowing with pushy lenders who promise instant cash but hide massive interest rates in the fine print. Many online articles give outdated advice, leaving you confused about how modern unsecured borrowing actually works. Unethical blogs often promote predatory payday lenders just to earn quick cash from your emergency. Lenders use complicated financial words to make the loan process seem impossible to understand on your own. People often rush to apply for several loans at once, which accidentally damages their credit score.
The endless worry about monthly payments drains your daily energy and makes it hard to focus on your work. You start to feel ashamed, doubting your ability to manage your household budget and provide safety for your family. Constant financial anxiety leads to sleepless nights, which slowly ruins your physical health. Money stress often spills over into your relationships, causing tense arguments with your partner and children. The fear of making a wrong decision paralyzes your progress and robs you of your natural self-confidence.
Let us look at a simple scenario. Meet Mark, a hardworking graphic designer who needed to repair his work computer quickly to avoid losing his clients. Mark did not own a home, and his car was not worth enough to use as collateral. Every traditional bank he visited seemed to speak a different language, demanding assets he simply did not have. He felt overwhelmed by the cold rejections and almost gave up.
Many people face this exact wall every single day. We live in a society where emergencies do not wait for you to build up a perfect savings cushion. When you need money, you do not want to be treated like a risky number on a spreadsheet. You deserve a fair, clear path to borrow money without risking the few valuable things you own.
That is why learning about no-collateral personal funding is so important. We wrote this guide to clear up the confusion and show you how to find trustworthy lenders. Let us step away from the stress and look at the real facts together.
 How to Secure a No-Collateral Bank Loan Without the Stress
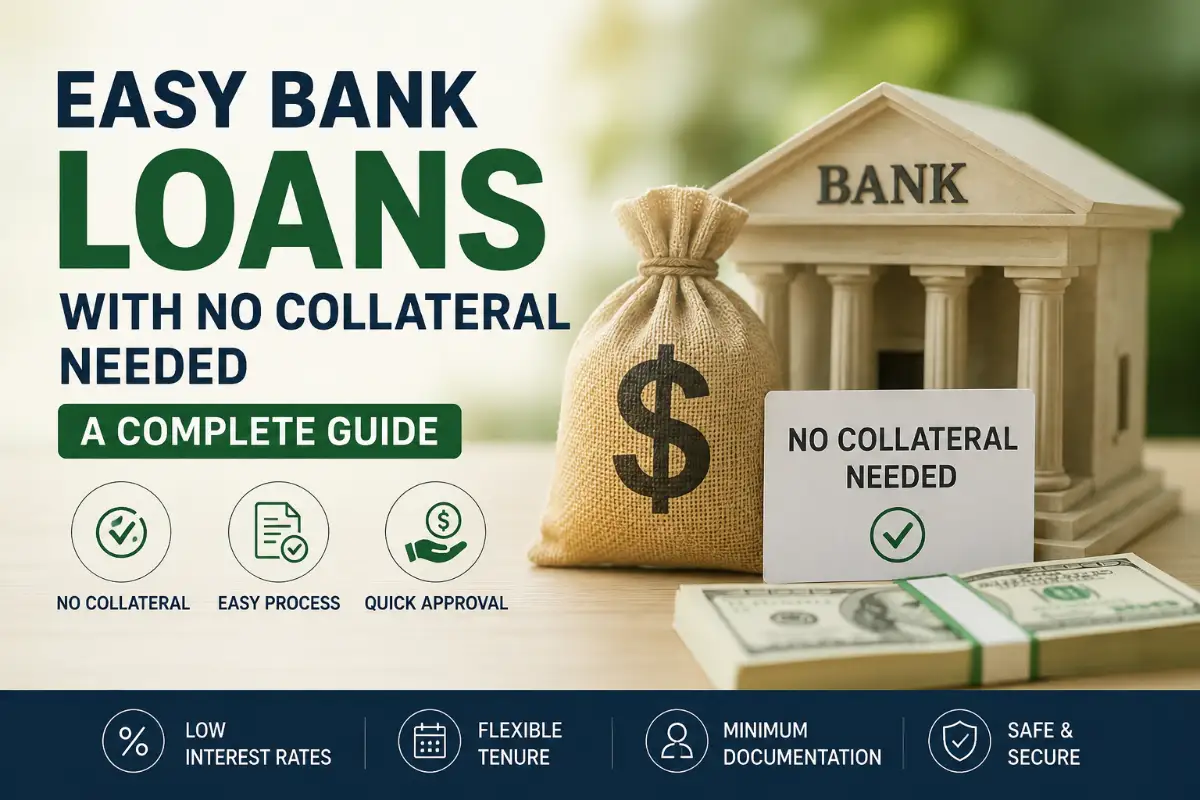
Getting a loan from a bank without offering any assets might seem complicated, but it is actually very straightforward. When a bank lends money without collateral, they are offering an unsecured personal loan.
Because the bank has no asset to seize if you stop paying, they look closely at your financial behavior. They want to be sure that you are a responsible borrower who will pay back every dollar. Let us break down the exact steps you can take to make your application look excellent.
Step 1: Make Your Credit Profile Shine
Your credit score is your financial reputation on paper. Since there is no house or car to back the loan, banks rely heavily on this number to make their decision. A higher score tells the lender that you are a safe bet.
You can check your credit report for free online within a few minutes. Look closely for any mistakes, such as a paid bill that still shows as outstanding. Disputing these simple errors can improve your score faster than you think.
Also, try to keep your credit card balances low compared to your overall limits. Keeping this utilization rate below thirty percent is a great way to show banks you manage your debts wisely. This small change can make a massive difference in your approval odds.
Step 2: Organize Your Income Proof
Banks want to see that you have a steady stream of cash coming in to handle the new monthly payments. If you cannot prove your income, the bank will quickly deny your request.
Gather your recent pay stubs from your job and put them in a dedicated folder. You should also find your tax documents from the past two years to show your steady work history.
If you are self-employed, download your past three months of business bank statements. Having these papers ready to go prevents delays and shows the bank that you are organized and serious.
Step 3: Compare Trustworthy Lenders
Watch this quick video to discover how no-collateral loans work and how to choose the right lender for your emergency!
Do not just apply at the first bank you see on your street. Different financial institutions offer vastly different rates and terms for unsecured borrowing.
Online-only banks often have lower overhead costs, which means they can offer better interest rates. Credit unions are another excellent option because they focus on helping their members rather than making massive profits.
Take some time to look at several options side by side. Pay close attention to the interest rates and the repayment lengths to find the best fit for your budget.
Myth vs Reality: Unsecured Borrowing
Myth: "Unsecured loans are only for people with perfect credit scores."
Reality: Many modern lenders offer easy bank loans to people with average credit. You might pay a slightly higher interest rate, but you can still get approved without risking your personal property.
Comparing Your Borrowing Options
My Personal Pro Tip: Early on, I made the mistake of filling out full applications at three different banks in one afternoon, which accidentally pulled down my credit score. Once I switched to using soft pre-qualification tools first, I could compare rates safely without hurting my profile or risking automatic rejections. Always use the pre-qualification options on lender websites before submitting a formal application because this process uses a soft inquiry to keep your credit score completely safe.
Calculating Your Debt-to-Income Ratio and Advanced Approvals
Before a bank gives you a loan, they want to make sure you can afford the monthly bill. They do this by calculating your debt-to-income (DTI) ratio.
To find your DTI, add up all your monthly debt payments, like credit cards and car loans. Then, divide that total by your gross monthly income before taxes.
Banks generally want to see a DTI ratio that is below thirty-five percent. A low DTI ratio shows the lender that you have plenty of room in your budget for a new payment. If your ratio is too high, try to pay down some small debts before you apply for your new loan.
Let us look at a simple scenario. Imagine you earn four thousand dollars a month before taxes. If your monthly bills add up to one thousand dollars, your DTI ratio is twenty-five percent. This is an excellent score that will make lenders feel very comfortable.
However, if your monthly bills are two thousand dollars, your ratio is fifty percent. At this level, banks might worry that you do not have enough breathing room to pay them back on time. Keep this formula in mind as you prepare your financial profile.
Once you prepare your basic documents, you can use advanced methods to improve your approval odds. Getting an unsecured loan is a lot like renting a high-end apartment. The landlord checks your job history and past behavior because they want to know you are highly reliable.
One of the best secrets to fast-track your application is to leverage your current banking accounts. When you apply at a bank where you already have a checking account, you bypass many verification steps. The bank's automated systems can instantly review your direct deposit history and average monthly balances.
For more details on this strategy, you can read about federal vs private student loans to see how smart structural choices impact borrowing costs. To avoid any unexpected roadblocks during this process, make sure you prepare your file properly. We highly recommend reviewing guidance on how to improve your credit score before you submit your formal paperwork.
Taking this precaution keeps you from making simple errors that might trigger an automatic rejection. A clean application file is the best ticket to getting your cash within a single business day.
The actual secret of master borrowers is not just getting the cash, but keeping their credit scores perfectly healthy. To do this, you must build strong, automated repayment habits from day one. We recommend setting your monthly payment date to land exactly two days after your monthly paycheck arrives. This buffer period ensures you always have enough money in your account to cover the loan bill.
It also keeps you from accidentally spending your bill money on non-essential items before the bank withdraws it. This small budgeting trick will protect your financial reputation without requiring any daily effort. While unsecured loans are an excellent tool for handling emergencies, you do not want to rely on debt forever. Over time, borrowing money repeatedly can hold you back from achieving true financial freedom.
Once your immediate cash emergency is solved, your next target should be to stop borrowing for good. You can do this by learning how to protect your budget from future surprises. Having your own cash reserve means you will never have to pay interest to a bank again when a crisis happens. You will have total control over your life, knowing your savings are strong enough to protect your family.
 Traps and Blind Spots That Destroy Your Borrowing Power
When you need cash quickly, it is easy to become impatient and skip important checks. Lenders are businesses that want to make a profit, and they often design loans to benefit themselves.
You must remain alert to avoid signing a contract that will drain your bank account for years. Let us look closely at the most common traps that catch unwary borrowers off guard.
The Danger of Multiple Hard Inquiries
Many people make the error of applying for three or four bank loans in the same week. They assume that casting a wide net increases their chances of getting at least one approval.
Unfortunately, this action actually causes your credit score to drop rapidly. Each formal application triggers a hard inquiry, which tells credit bureaus you are desperate for cash.
To avoid this, use soft-pull tools to check your rates instead of submitting full applications right away. You can study related concepts like choosing your first home insurance policy to understand how risk assessment works behind the scenes.
Ignoring the Real Cost of Hidden Administrative Fees
Another common pitfall is ignoring the upfront fees that banks deduct before you receive your funds. Some banks charge an administrative fee, often called an origination fee, which can range from one to eight percent of the total loan amount.
For example, if you get approved for a ten thousand dollar loan with an eight percent fee, the bank will deduct eight hundred dollars immediately. You will only receive nine thousand two hundred dollars, but you will still have to pay interest on the full ten thousand.
Always ask your lender if they charge these upfront fees before you finalize the loan. If they do, you may need to borrow a slightly higher amount to cover the difference.
The Temptation of Over-Borrowing
When banks see a strong credit score, they will often offer to lend you more money than you actually requested. If you need five thousand dollars, they might tell you that you are approved for fifteen thousand.
It is very tempting to take the extra cash to pay for a vacation or buy new electronics. However, this extra debt will quietly eat away at your monthly paycheck for years to come.
Remember that every extra dollar you borrow comes with a high interest charge. Stick strictly to your original plan and only borrow the exact amount needed to cover your emergency.
Simple Do's and Don'ts for Fast Bank Loans
- Do check your credit report for errors and fix them before applying.
- Do use online pre-qualification tools to check your rates safely.
- Do organize your tax returns and pay stubs into a single digital PDF folder.
- Don't borrow more money than you actually need to solve the current emergency.
- Don't apply for new credit cards while you are waiting for a loan approval.
- Don't hide your existing debts or income sources from your loan officer.
Your Daily Action Checklist: Reclaiming Control of Your Money
Taking control of your financial life is not about making massive changes overnight. It is about making small, deliberate choices every single day. You do not have to fix everything in one afternoon, but you must take consistent steps forward.
We have designed a simple action plan that you can start using tomorrow morning to protect your wallet and secure your financial future.
- Verify Your Credit Score: Download your free credit report online and check for any old errors that are holding your score down.
- Build Your Digital Folder: Gather your recent pay stubs, bank statements, and tax returns into one neat folder on your computer.
- Compare Soft-Pull Offers: Use a free online tool to calculate your current debt-to-income ratio.
- Choose Your Repayment Length: Choose the shortest repayment term you can comfortably afford to keep your total interest costs low.
Looking back at my own struggles with unexpected bills, I realize that taking control starts the moment you decide not to panic. My personal journey taught me that financial confidence is built brick by brick through informed choices. I want you to feel that same sense of relief knowing you can handle any cash crunch safely. Stay strong, keep learning, and take that very first step toward financial peace today.
Recommended Reading Resources
To further support your financial literacy journey, explore these internal guides:
- Federal vs Private Student Loans Guide
- How to Choose Your First Home Insurance Policy
- How to Improve Your Credit Score Before Applying for a Mortgage
Frequently Asked Questions
What is an unsecured personal loan?
An unsecured personal loan is money borrowed from a bank or lender that does not require any collateral like a house or car. Approval is based entirely on your credit history and income.
How fast can I get funds from an unsecured loan?
Many online lenders and traditional banks can deposit funds into your checking account within one to three business days after formal approval.
Will checking my rates hurt my credit score?
No, checking your rates using online pre-qualification tools triggers a soft credit inquiry, which has zero impact on your credit score.
What is a good debt-to-income ratio for loan approval?
Most lenders prefer a debt-to-income ratio below thirty-five percent because it proves you have sufficient monthly income to manage a new payment.
Can I get an unsecured loan with average credit?
Yes, several modern lenders cater to applicants with fair or average credit scores, though you may receive a slightly higher interest rate.
Disclaimer: Dealing with a sudden emergency is tough, but you are more than capable of taking control and guiding your financial future. Start with just one small action on your checklist today, trust the process, and watch your peace of mind return step by step. The information provided in this article is for educational and informational purposes only. It should not be taken as professional financial, investment, or legal advice. Always consult with a certified financial planner or advisor before making any major financial decisions or signing loan agreements.