The Stress of Navigating Your First Big Loan Without Collateral
When I applied for my very first loan years ago, I sat awake at midnight feeling completely terrified because I had zero assets to offer as security. My hands shook as I browsed online, worrying that one wrong click would ruin my financial future forever. That stressful night taught me how important it is to have clear, honest guidance when you are trying to secure funds without putting your personal property at risk. I remember feeling totally lost in a sea of confusing financial jargon while trying to figure out how monthly installments worked. It took hours of research and speaking with a trusted advisor to realize that safe borrowing options genuinely existed for beginners like me.
Imagine sitting at your kitchen table at midnight, staring at an unexpected medical bill or a major car repair cost. You need cash fast, but you have no home or expensive assets to offer a bank as security. The thought of walking into a cold bank office and asking for a loan makes your hands shake with anxiety.
You worry about getting rejected because you have never borrowed money before. The fear of making a bad deal that ruins your financial future keeps you awake for hours. You feel completely overwhelmed, confused, and alone in the dark.
You want to make a smart move, but the constant worry makes it hard to think straight. You are not just looking for money; you are looking for safety and peace of mind.
The internet is packed with deceptive loan ads that promise instant approval but hide trap-like interest rates in the tiny text. Confusing terms like amortization and annual percentage rate make simple loan documents look like a foreign language. Many online forums give conflicting, dangerous advice that can lead first-time borrowers into massive credit card debt. Pushy online lenders often target beginners with high-fee products before they can explore cheaper local bank options. Many people fail to realize that applying for multiple loans at once actually damages their credit score instantly.
The constant stress of not knowing where to get cash drains your energy and hurts your focus at work. You begin to doubt your own intelligence, wondering why you did not build a larger emergency fund earlier. Anxiety over unpaid bills can cause tension in your home, leading to sad arguments with the people you love. The fear of being rejected by a bank damages your self-esteem and makes you feel financially helpless. Struggling to find honest answers keeps your mind in a constant loop of worry, which ruins your physical health.
Let us look at a common scenario to understand this reality better. Meet Alex, a hardworking young retail worker who needed to replace his old car tires so he could safely drive to his job. He did not own a house, and his savings were barely enough to cover his monthly rent and food.
When he searched online for quick cash, he was flooded with hundreds of flashy advertisements. Some promised no credit check, while others demanded high fees that made no sense to him. Alex felt like he was walking through a dangerous swamp without a map.
He wanted to make a smart, responsible choice, but the fear of falling into a debt trap paralyzed him. This is the exact spot where millions of first-time borrowers get stuck every day. You should not have to risk your peace of mind just because you need to borrow money.
You deserve a clear, honest, and simple roadmap that teaches you how unsecured loans work without the complicated math. This guide is here to wipe away the fear and give you the real facts so you can step forward with total confidence.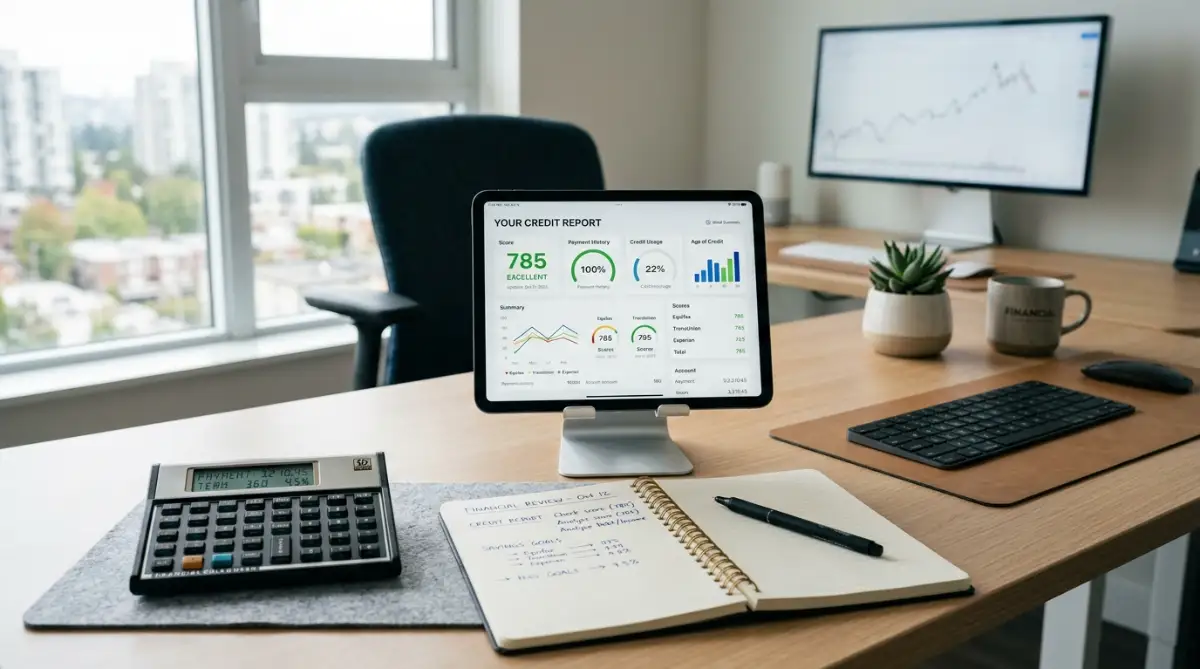 Demystifying Unsecured Borrowing: How These Loans Actually Work
An unsecured loan is a simple contract where you promise to pay back borrowed cash over time with interest. Lenders call these signature loans because your signature is the only security you provide.
Since there is no physical asset like a house or a car for the bank to take if you stop paying, they check your creditworthiness instead. Because of this, lenders evaluate your credit score, your steady monthly income, and your current job stability to measure their risk.
They also check your debt-to-income ratio to make sure you have enough breathing room in your budget for a new monthly payment. Understanding these factors is the key to preparing a successful application.
Myth vs Reality: The Unsecured Loan Truth
Myth: "First-time borrowers can never get approved for a bank loan without collateral."
Reality: Many banks and online lenders design specific starter loans for beginners with no collateral. You just need to show a steady income and a clean basic credit history.
Comparing Your Beginner Loan Options
My Personal Pro Tip: When I first started looking into borrowing, I almost accepted a high-rate deal because I only paid attention to the monthly bill instead of looking at the big picture. Once I learned to focus on comparing the full Annual Percentage Rate across multiple lenders, I saved hundreds of dollars in hidden charges and avoided a major debt trap. Always compare the APR instead of just the basic interest rate to uncover all hidden administrative fees.
Watch this quick video to learn how unsecured personal loans work and how you can compare rates safely before applying:
Three Key Steps to Secure Your First Unsecured Loan
If you want to get approved quickly, you need to prepare your profile before you talk to a lender. Following a step-by-step system will make you look like a highly responsible borrower. Let us examine the three most effective steps you can take today.
Step 1 is to decode and polish your credit score. Your credit score is your digital financial passport, and lenders use this number to decide if you are safe to trust. You can get a free copy of your credit report online in minutes and check for simple mistakes, like an old paid bill that still shows active. Disputing these tiny errors can instantly improve your score, giving you access to lower interest rates.
Step 2 is to build a ready-to-go digital document folder. The biggest reason beginner loans get delayed is missing or incorrect paperwork. You can avoid this headache by putting your recent pay stubs, bank statements, and tax returns into a single PDF folder. Having this ready shows the bank you are an organized, serious borrower and slashes verification time.
Step 3 is to utilize soft-pull pre-qualification. Never accept the very first loan offer you see in your inbox, because lenders have very different rates. Use online pre-qualification tools on trusted lender websites to compare your options safely using a soft inquiry. To understand how lenders evaluate risk, you can read our guide on federal vs private student loans to see how smart structural choices impact borrowing costs.
To avoid unexpected rejections, make sure your application file is completely clean. We highly recommend reviewing the ultimate guide on how to improve your credit score before submitting formal paperwork. Taking this precaution keeps you from making simple errors that might trigger an automatic rejection.
Once you understand the basic requirements, you can use advanced strategies to improve your financial profile. Consider the power of relationship banking by applying at a bank or credit union where you already keep a checking account. If you need additional background on managing credit types, you can also review resources regarding how to choose your first home insurance policy to understand risk management principles. Keeping your financial documents structured and clean is the best ticket to getting your cash within a single business day.
 Traps That Sabotage First-Time Borrowers
When you are facing an urgent money problem, it is very easy to become impatient and skip important checks. Lenders are businesses that want to make a profit, and they often design loans to benefit themselves.
Falling Into the Trap of Multiple Hard Inquiries
Many beginners make the classic mistake of applying for several loans at the same time to see who gives them the best deal. Each official application triggers a hard inquiry, which drops your credit score and signals financial distress to banks.
Ignoring Hidden Fees in the Fine Print
Many borrowers focus solely on the monthly payment amount while ignoring sneaky administrative charges. Origination fees are often deducted before cash hits your account, meaning you pay interest on money you never actually received.
Simple Do's and Don'ts for Beginners
- Do check your credit report for errors and dispute them before applying.
- Do compare the annual percentage rates of at least three lenders.
- Do set up automatic payments to avoid late fees and missed due dates.
- Don't accept a loan if the monthly payment takes up more than ten percent of your take-home pay.
- Don't apply for multiple loans within a short window of time.
- Don't use a personal loan to buy luxury items or fund expensive vacations.
Your Immediate Action Plan for Financial Peace
Taking control of your finances is a journey that starts with small, daily steps. You do not have to figure out everything today, but you must start moving in the right direction.
- Calculate Your Monthly Income and Bills: Write down every single dollar that comes in and goes out to see how much room you have for a loan payment.
- Get Your Free Credit Report: Use a trusted website to check your credit score and look closely for any mistakes.
- Compare Your Options Safely: Find three lenders that offer soft credit checks and look at their fees and interest rates side by side.
Looking back at my own early struggles with borrowing, I realize how much peace of mind comes from simple preparation. My personal journey taught me that financial literacy is the best shield against predatory traps. I want you to feel that same absolute confidence when managing your money. Stay strong, keep learning, and take that first step toward financial peace today.
Recommended Reading Resources
Explore these internal guides to master your financial strategy:
- Federal vs Private Student Loans Guide
- How to Improve Your Credit Score Before Applying for a Mortgage
- How to Choose Your First Home Insurance Policy Without Stress
Frequently Asked Questions
What is an unsecured personal loan?
An unsecured personal loan is money borrowed from a bank without requiring any physical assets or collateral, relying instead on your credit history and income.
Will checking my rates online hurt my credit score?
No, checking your rates using pre-qualification tools utilizes a soft credit inquiry, which keeps your credit score completely safe.
What is an origination fee on a loan?
An origination fee is an upfront administrative charge deducted by the lender from your loan amount before the funds are deposited into your account.
Can I use a co-signer if I have no credit history?
Yes, asking a trusted family member with strong credit to act as a co-signer can help you secure approval and lower interest rates.
Why should I compare APR instead of interest rates?
The Annual Percentage Rate includes all hidden administrative fees and charges, giving you the true, complete cost of borrowing the money.
Disclaimer: Taking charge of your financial journey might feel scary at first, but you have all the tools you need to make smart, confident choices. Take that very first step on your checklist today, stay consistent, and watch how quickly your financial peace of mind grows. The information provided in this article is for educational and informational purposes only. It should not be taken as professional financial or legal advice. Always consult with a certified financial planner or advisor before making any major financial decisions or signing loan agreements.


