The Credit Card Confusion: Why Most People Pick the Wrong Card
A few years ago, I signed up for an expensive premium travel card because the glossy advertisement promised thousands of free bonus miles. Within six months, I realized that I barely traveled enough to justify the steep annual fee, while high interest charges ate away my savings. That embarrassing mistake taught me the hard way that picking a card based on shiny perks instead of actual spending habits is a quick way to lose money. I remember sitting at my desk calculating the point values, realizing I had spent more on fees than I earned in rewards. That painful lesson forced me to study how reward structures and fee conditions actually work. Once I started matching my cards to my real budget, managing plastic became effortless.
Walking into a bank or scrolling through credit card offers online can feel completely overwhelming. Glossy advertisements promise free flight tickets, massive cash-back percentages, and exclusive airport lounge access.
However, millions of consumers end up picking credit cards that do not match their actual daily spending habits. You end up paying steep annual fees for benefits you never use, while high interest rates silently eat away at your hard-earned money.
Why everyday consumers struggle to select the right credit card:
- Falling for flashy sign-up bonuses: Many applicants choose cards based entirely on a temporary welcome bonus without reading the long-term annual fee conditions.
- Misunderstanding credit card interest rates: People often ignore high variable interest rates, assuming they will pay off their full balance every single month.
- Overestimating travel habits: Consumers frequently pick expensive travel rewards cards when a simple zero-fee cash-back card would save them far more money.
- Failing to check minimum credit score requirements: Applying for premium cards without meeting the necessary credit rating causes instant rejections and hard credit pulls.
How card mismatches damage your financial peace of mind:
- Regret over unexpected annual fees: Watching a hundred-dollar annual fee hit your statement for an unused card creates instant financial frustration.
- Trapped in high-interest debt cycles: Carrying a balance on a high-APR rewards card quickly cancels out any points or miles earned.
- Confusion over complicated reward structures: Struggling to understand rotating reward categories makes earning cash back feel like a confusing chore.
I have seen countless individuals face this exact frustration. You open a new credit card expecting great perks, only to find out that the points expire or the redemption process requires complex effort.
When you do not align your credit card with your true spending habits, you waste money every time you swipe. You end up serving the credit card company instead of making the credit card work for you.
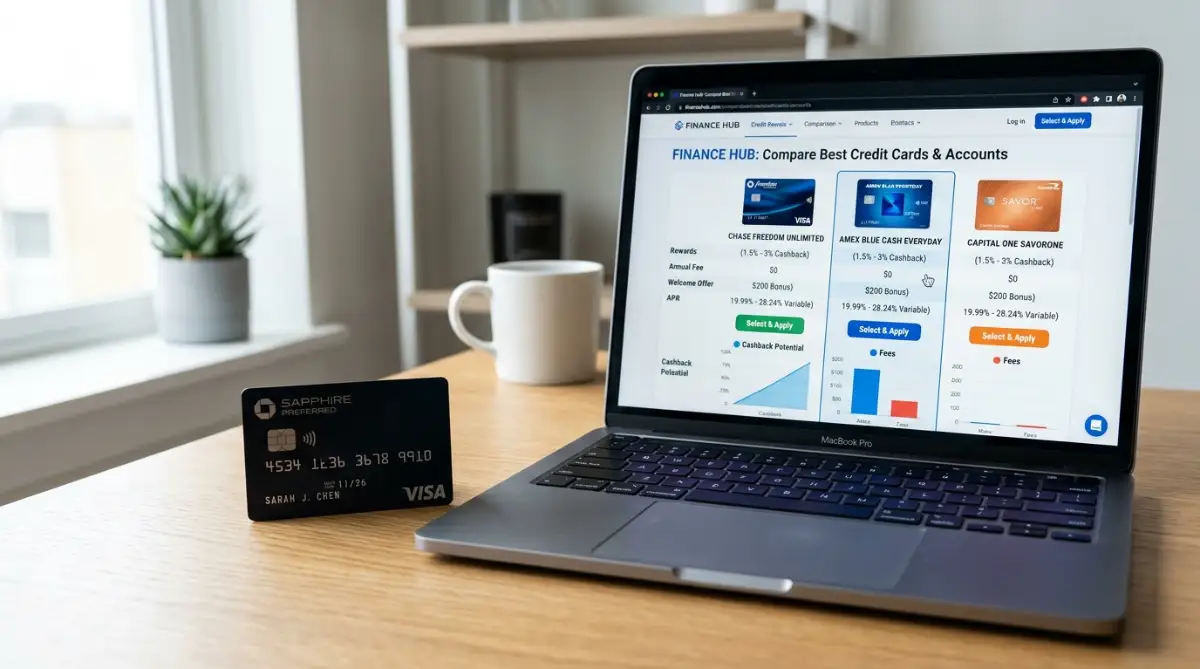
The key to financial success is choosing a credit card that fits your current budget like a glove. Once you learn how to evaluate interest rates, fee structures, and reward categories, you can select a card that builds your wealth effortlessly.
The Selection Framework: How to Pick Your Ideal Credit Card
Choosing a credit card is a personal financial decision that depends entirely on your income, spending priorities, and credit score. There is no single best credit card for everyone, but there is a perfect card for your specific profile.
Let us explore the core card categories to see how different options align with different financial goals.
Core Credit Card Categories
Matching your primary financial goal with the correct category ensures you earn maximum value without wasting money on unused features.
Comparing Credit Card Categories
Myth vs Reality: Credit Card Selection
Myth: "Opening a new credit card will ruin your credit score forever."
Reality: A new card causes a temporary minor drop due to a hard inquiry, but it increases your total credit limit and lowers your credit utilization ratio over time.
My Personal Pro Tip: Here is a personal lesson I learned after drowning in credit card point charts: managing five different category cards felt like a stressful accounting job. My pro tip is to stick with a simple two-card system—one flat-rate cash-back card for everyday purchases and one category card for groceries or fuel. This simple setup keeps your wallet organized and earns you steady rewards without any unnecessary stress.
Watch this helpful video guide to learn how to choose the right credit card for your personal financial goals:
Advanced Credit Card Optimization: Unlocking Pro-Level Value
Once you understand basic credit card categories, using advanced card management tactics can double your annual rewards while keeping your credit score in top shape. Choosing the right card is only half the battle; knowing how to manage it strategically completes your financial blueprint. I have helped many readers transform their credit cards from simple payment tools into reliable wealth-building engines. These pro-level secrets ensure that you extract maximum value from card issuers without falling into debt traps. One smart tactic is leveraging 0% APR intro periods for large planned purchases. If you plan to buy new home appliances, pay for home repairs, or finance a major life event, a credit card offering a 0% introductory APR period can serve as an interest-free loan for twelve to twenty-one months. To ensure your credit profile meets lender standards before applying for new financing accounts, you can review our guide on how to improve your credit score to prepare your file effectively.
Another powerful strategy is pairing your credit cards with cash emergency reserves. Credit cards provide fantastic convenience and reward perks, but they should never replace an emergency cash fund. Relying on credit cards for unexpected medical emergencies or job losses can quickly lead to maxed-out card limits and damaged credit scores. Maintain a dedicated savings account alongside your credit card setup to cover unexpected living expenses, and explore our step-by-step guide on building a bulletproof emergency fund to create a financial cushion. If you are balancing student loans or educational expenses alongside your card management strategy, reviewing insights on federal vs private student loans helps you manage overall debt obligations safely. For small business owners or freelancers managing commercial credit card accounts, you can explore resources on easy AI website builders for small businesses to establish professional online branding and extra revenue channels.
Furthermore, maintaining household protection against unexpected liability keeps your overall financial house in order. For related insights on safeguarding your personal assets and insurance standing, check out tips on how to choose your first home insurance policy without unnecessary anxiety. Keeping your financial records organized and your utilization ratios low protects your borrowing power for major life decisions. You will enjoy lower interest rates and smoother loan approvals whenever you need financing.
 Credit Card Pitfalls That Drain Your Bank Account
Even smart consumers make costly errors when choosing or using credit cards. Being aware of these traps helps you avoid unnecessary fees and protect your hard-earned credit score.
Carrying Balances on High-Interest Rewards Cards
The biggest trap in personal finance is carrying a monthly balance on a rewards card, as high variable interest rates quickly erase any points or cash back earned.
Using Credit Cards for Cash Advances
Taking a cash advance from an ATM using your credit card incurs immediate upfront processing fees and starts accumulating high-interest charges instantly without any grace period.
Simple Do's and Don'ts for Card Success
- Do set up automatic payments for the full statement balance every month.
- Do monitor your card accounts weekly through mobile apps for fraud alerts.
- Do redeem your earned cash back or travel points regularly before they expire.
- Don't treat your credit card limit as extra income or emergency cash.
- Don't carry a monthly balance on rewards cards with high APRs.
- Don't apply for store cards at checkout just to get a one-time ten percent discount.
Action Plan for Tomorrow: Select Your Perfect Credit Card
Choosing the right credit card is a powerful step toward taking complete control of your financial destiny. You do not need to feel confused by bank advertising or intimidated by credit card terms anymore.
- Check Your Credit Score: Know your exact score tier before browsing credit card offers online.
- Audit Your Monthly Expenses: Review your recent bank statements to identify your top two spending categories.
- Compare Net Reward Values: Calculate the actual dollar return after subtracting any annual fees.
Finding the right credit card is one of the most rewarding steps you can take to make your everyday money work for you. I know how confusing card terms and annual fees can feel at first, but taking just ten minutes to audit your spending today changes everything. Believe in your financial decisions, choose the card that fits your real lifestyle today, and enjoy the cash-back rewards you deserve!
Recommended Reading Resources
Explore these internal guides to master your overall financial strategy:
- How to Improve Your Credit Score Before Applying for a Mortgage
- Federal vs Private Student Loans Guide
- How to Choose Your First Home Insurance Policy Without Stress
- Easy AI Website Builders for Small Businesses Simple Setup Guide
Frequently Asked Questions
How many credit cards should the average person have?
Most financial experts recommend having two to three well-chosen credit cards to maximize rewards across key spending categories while keeping management simple.
Does applying for a new credit card hurt my credit score?
Submitting a formal credit card application triggers a hard credit inquiry that temporarily lowers your score by a few points before recovering quickly.
How do I know if an annual fee card is worth the cost?
An annual fee card is worth it if the monetary value of perks and rewards you actually use exceeds the annual fee price tag.
Should I carry a balance to build my credit score?
No, carrying a balance does not help your credit score; it only incurs high-interest charges. Always pay your balance in full every month.
What is a credit card balance transfer?
A balance transfer moves high-interest debt from one card to a new card offering a 0% introductory APR period to help pay down debt interest-free.
Disclaimer: This article is strictly for educational and informational purposes and does not constitute formal financial, legal, or credit counseling advice. Credit card terms, interest rates, annual fees, and reward structures vary depending on card issuers and individual applicant credit profiles. Always read the official credit card agreement and terms from the issuing bank before submitting a formal application.


