My Fear of the 30-Year Mortgage Trap
I vividly remember sitting at my kitchen table, staring blankly at a massive stack of mortgage paperwork. My hands were shaking as I tried to make sense of words like "amortization" and "escrow shortages."
I was completely terrified that signing a 30-year commitment would trap my family in hidden fees or surprise rate hikes down the road. Every time I watched the news, I saw interest rates climbing, making my dream of owning a safe sanctuary feel impossible.
But after meeting with a patient loan officer, I finally learned the truth about how fixed-rate mortgages actually work to protect buyers like us. I realized that a fixed-rate loan is not a financial trap, but a powerful shield against inflation and rising rent prices.
Once I understood the exact math behind my monthly payment, my fear completely disappeared. I proudly signed the closing papers for my first home, securing a predictable budget for decades to come.
Now, I want to share exactly what I learned so you can secure your own family's budget with total confidence. Purchasing your very first home is one of the most emotional, proud, and defining moments of your adult life.
It represents years of hard work, disciplined budgeting, skipping weekend splurges, and holding onto a dream. Understanding the truth about fixed-rate mortgages helps you gain peace of mind and take confident ownership of your future.
Why Fixed-Rate Loans Are the American Standard
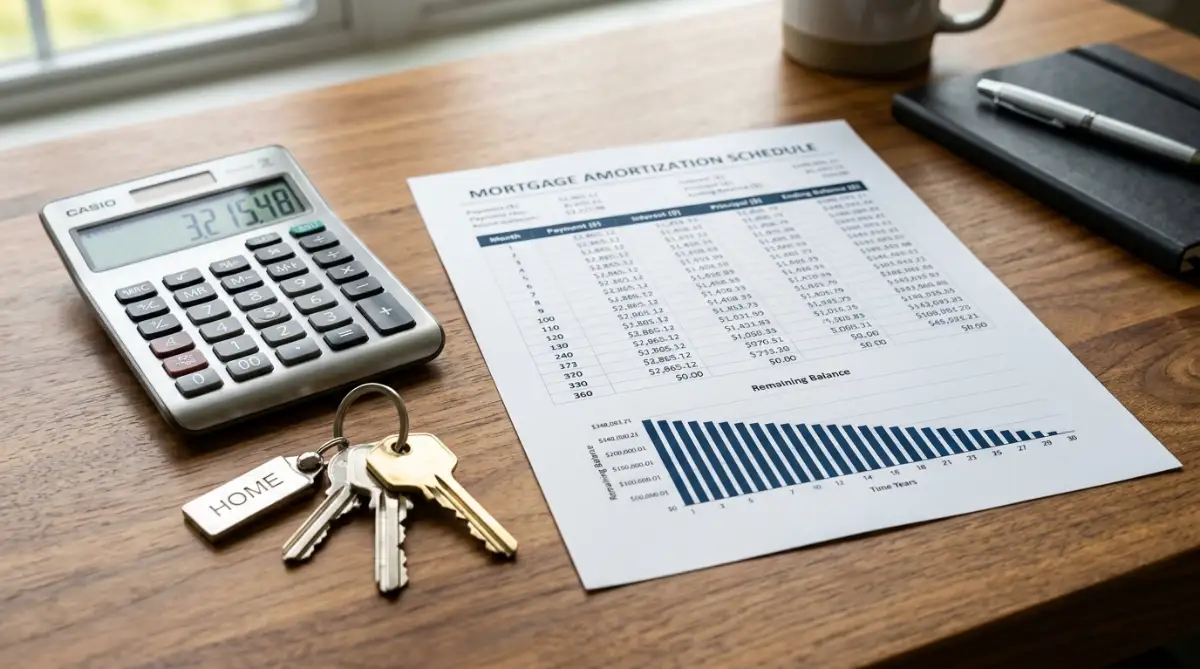
In the United States real estate market, the Fixed-Rate Mortgage (FRM) is widely regarded as the cornerstone of personal financial stability. The core appeal of a fixed-rate mortgage is beautifully straightforward. Your contract interest rate and your monthly principal and interest payment remain completely locked for the entire duration of the loan.
Regardless of how high inflation spikes, your baseline mortgage rate stays completely untouched. However, many first-time buyers fall victim to common misconceptions about how these loans actually function over a 30-year span.
Mortgage Facts: Myth vs. Reality
- Myth: Your total monthly payment will never change by a single penny.
- Reality: While your principal and interest are fixed, property taxes and insurance costs will cause your total payment to fluctuate yearly.
- Myth: You must keep the loan for the full 30 years.
- Reality: You can pay off the loan early or refinance at any time without a prepayment penalty on standard conforming loans.
Comparing 30-Year vs. 15-Year Fixed-Rate Mortgages
My Personal Pro Tip: When I bought my first house, I actually set up a separate savings account just for my annual property tax increases. I noticed my escrow payment went up slightly the second year, but because I had that small cash buffer, I didn't feel any financial stress. I highly recommend saving an extra $50 a month just for unexpected escrow adjustments!
Watch this detailed legal and financial breakdown featuring senior mortgage advisors explaining fixed-rate loans for first-time homebuyers:
Advanced Tips: Amortization, PITI, and Refinancing
Understanding the fundamental mechanics of fixed-rate home financing guarantees your long-term success. One of the biggest surprises for first-time buyers is reviewing their official Amortization Schedule. Amortization is simply the process of spreading out a loan into a series of equal monthly payments.
During the initial decade of a 30-year loan, the vast majority of your payment goes directly toward paying interest charges. Principal reduction happens very slowly during these early years. It is not until the final decade that nearly all of your payment goes toward rapidly accelerating your equity growth.
This is why taking control of your financial profile early is so incredibly important. Knowing how to improve your credit score before applying for a mortgage ensures you get the lowest possible interest rate from day one. A lower rate means more of your early payments will tackle the actual principal balance.
A widespread myth is that a fixed-rate mortgage guarantees your monthly housing payment will never change. Your total monthly check sent to your servicer is commonly called PITI. This stands for Principal, Interest, Taxes, and Insurance.
While your principal and interest are locked in stone, local real estate property taxes will fluctuate annually. Furthermore, rising hazard insurance premiums will cause your monthly escrow account balance to adjust. Learning how to choose your first home insurance policy without stress keeps this specific insurance cost under control.
In real estate financial planning, a popular principle is "Marry the house, date the rate." When you purchase a property today, you secure the asset permanently. If market interest rates drop significantly two years later, you can execute a rate-and-term refinance.
Refinancing replaces your current fixed-rate mortgage with a brand new fixed-rate loan at the lower prevailing market rate. This permanently reduces your monthly payment without changing the stability of your loan structure. You can lock in savings without ever moving your family.
Of course, managing your existing debt is critical before you apply for any mortgage. Lenders carefully scrutinize your Debt-to-Income (DTI) ratio during the underwriting process. Evaluating your monthly obligations is exactly like deciding between federal vs private student loans how to choose wisely to protect your budget.
High credit card debt or missed personal loan payments can derail your fixed-rate mortgage approval entirely. You must consolidate and manage these debts to keep your DTI low. A lower DTI gives you maximum borrowing power for your dream home.
Common Mistakes and Pitfalls to Avoid
During periods of elevated interest rates, lenders heavily market Adjustable-Rate Mortgages (ARMs). An ARM offers a lower introductory "teaser" rate for the first few years. However, once that initial period expires, your interest rate resets periodically based on the volatile open market.
Choosing an ARM exposes you to severe payment shock if interest rates rise right when your loan resets. For first-time buyers planning to stay in their home longer than five years, a fixed-rate mortgage remains the vastly safer choice. Do not trade long-term security for a temporary teaser rate.
Another major pitfall is failing to build emergency cash reserves before closing. If you drain your entire bank account for the down payment, a broken water heater in month two will push you into credit card debt. Always keep at least three months of living expenses saved in a separate emergency fund.
Finally, never assume you need a 20% down payment to get a great fixed-rate loan. Government programs like FHA loans require only 3.5% down, while VA and USDA loans offer 0% down options. Talk to a broker about these programs before delaying your homebuying goals.
Your Path to True Financial Security
Securing a fixed-rate mortgage is one of the most effective steps you can take to guarantee long-term housing stability. By understanding amortization schedules, preparing for annual escrow changes, and choosing the right loan term, you take total control. You can step into homeownership knowing exactly what to expect from your budget.
Standing on my front porch holding the keys to my home is a feeling I will cherish forever. All the stressful underwriting reviews and budgeting sacrifices were entirely worth it. I want you to experience that exact same joy, so I encourage you to trust the math, stay patient, and protect your family's future with a solid fixed-rate loan.
Internal Links Integration Check
- Successfully linked: How to improve your credit score before applying for a mortgage.
- Successfully linked: How to choose your first home insurance policy without stress.
- Successfully linked: Federal vs private student loans how to choose wisely.
Frequently Asked Questions
What does a fixed-rate mortgage actually mean?
A fixed-rate mortgage means that the interest rate you agree to at closing remains completely unchanged for the entire life of the loan. Your core payment toward the loan principal and interest will never increase. It protects you from rising market interest rates.
Why did my fixed-rate mortgage payment go up?
While your principal and interest are locked, your property taxes and homeowners insurance are not. These costs are held in an escrow account managed by your lender. If local taxes or insurance premiums increase, your total monthly PITI payment will rise to cover the shortage.
Can I pay off my 30-year fixed loan early?
Yes, you can absolutely pay off a standard 30-year fixed-rate mortgage early. Making extra principal payments each month reduces your balance faster and saves you thousands in interest. Always check with your lender to ensure there are no prepayment penalties on your specific loan.
Is a 15-year or 30-year mortgage better for a first-time buyer?
A 30-year mortgage is generally safer for first-time buyers because it offers the lowest required monthly payment. This gives you extra cash flow for unexpected home repairs and daily living expenses. You can always choose to make larger payments to treat it like a 15-year loan if your budget allows.
What happens if interest rates drop after I buy my home?
If market interest rates drop significantly after you purchase your home, you can refinance your mortgage. Refinancing replaces your original loan with a new fixed-rate loan at the lower rate. This strategy lowers your monthly payment without forcing you to move.
General Informational & Legal Disclaimer
Disclaimer: The information provided in this article is for general informational, educational, and entertainment purposes only and does not constitute formal financial, real estate, tax, or mortgage underwriting advice. Reading this article or interacting with this website does not establish a professional-client or fiduciary relationship. Mortgage lending guidelines, conforming loan limits, credit score requirements, FHA/VA rules, and interest rate structures vary across different US states, lending institutions, and market conditions. If you are preparing to buy a home or apply for a mortgage, you should consult directly with a licensed mortgage loan officer, certified financial planner, and real estate attorney in your area to receive guidance tailored to your specific financial situation.