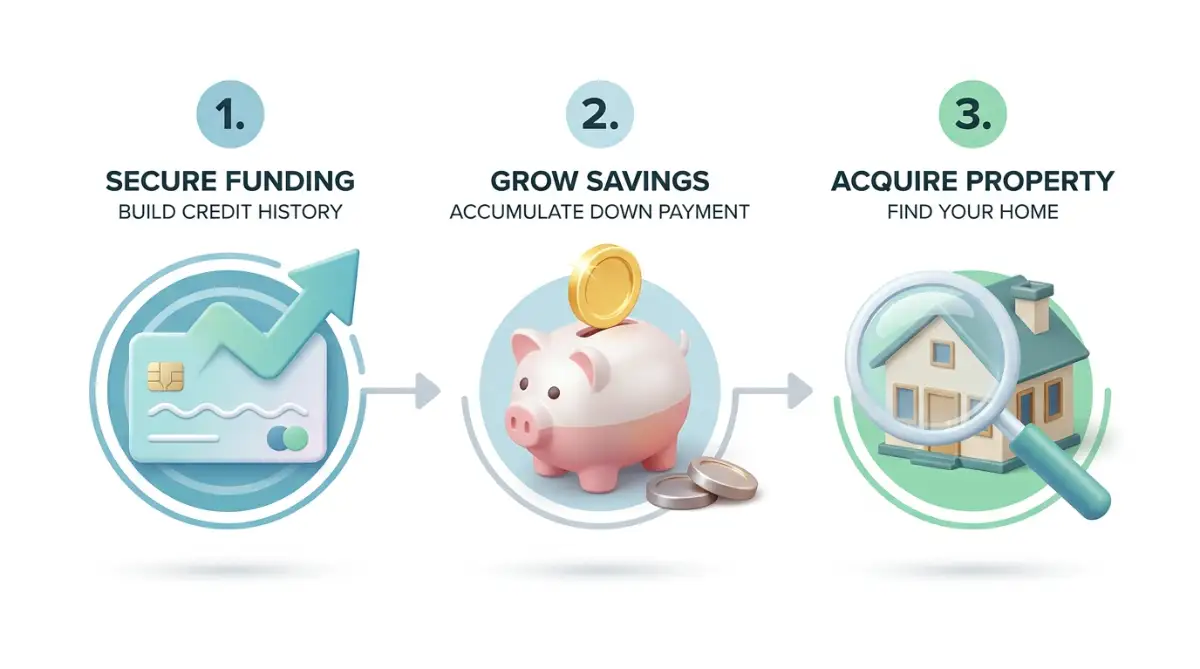
The Expensive Danger of Overpaying for Your Mortgage Rate
When I applied for my first home loan, I blindly accepted the interest rate offered by my local bank without taking the time to shop around and compare competing offers. A year later, I was devastated to realize my coworker secured a significantly lower rate simply by showing competing quotes to his lender, which saved his family over two hundred dollars every single month. Feeling deeply frustrated by my own costly mistake completely shifted my mindset and inspired me to master the hidden rules of mortgage negotiation. It truly hurts to imagine opening your banking app every month for thirty years and realizing a massive chunk of your payment goes straight to entirely avoidable interest charges. That unnecessarily high monthly housing expense severely squeezes your family budget, limits your lifestyle choices, and causes deep daily anxiety about your long-term financial stability. Fortunately, you do not have to fall into this common lending trap, because I am going to show you exactly how to take total control of your application and force banks to offer you their absolute best terms.
Over a standard thirty-year home loan, a tiny difference of just half a percent in your interest rate can cost you fifty thousand dollars or more. That is money that should be sitting securely in your family savings account or retirement fund instead of padding a bank's profit margins.
Most home buyers accept the very first rate quote from their local checking account bank without shopping around. Many buyers assume that having a decent credit score automatically qualifies them for the absolute lowest market rate available.
Higher monthly mortgage payments squeeze your household budget and leave less cash for monthly living expenses. Paying extra interest creates ongoing regret when you finally realize exactly how much money you are losing over time.
I know how overwhelming it feels to negotiate with bank loan officers who speak in complicated financial terms. Buying a house is already stressful enough without constantly worrying whether you are getting ripped off on your interest rate.
The good news is that bank underwriters use simple, strict mathematical formulas to set your exact interest rate. Once you understand what lenders look for, you can easily optimize your profile and force banks to compete for your business.
Proven Action Steps to Secure the Lowest Mortgage Interest Rate
Let us look at the exact steps you can take today to drive down your interest rate before signing loan papers. Taking these practical steps puts you in the driver's seat of your home financing journey.
Push Your Credit Score into the Top Tier
Your credit score is the single biggest factor that determines your final mortgage interest rate. Lenders group credit scores into specific brackets, and crossing into a higher bracket instantly drops your interest percentage.
While a credit score of 620 can get you approved for a loan, you need a score of 740 or higher to unlock top-tier rates. If you want to prepare your profile perfectly, check out our guide on how to improve your credit score before applying for a mortgage.
Lower Your Debt-to-Income (DTI) Ratio
Bank underwriters calculate your Debt-to-Income ratio by dividing your total monthly debt obligations by your gross monthly income. A high DTI ratio tells the bank that your monthly paycheck is already stretched too thin.
Even if you have great credit, a high DTI ratio can push your interest rate higher because the lender senses increased risk. Try to keep your total debt obligations below thirty-six percent of your gross income before applying for a mortgage.
Myth: "Your current checking account bank will always give you the lowest mortgage interest rate because you are a loyal customer."
Reality: Banks rarely offer their lowest rates to existing customers without aggressive rate matching against competing lender offers.
My Personal Pro Tip: I used to think that applying with multiple lenders would ruin my credit score, but I learned that credit bureaus group mortgage checks made within a short window into a single pull. Once I gathered four official loan estimates, I used the lowest offer to get my main lender to match the rate and drop their processing fees. Do not be afraid to shop around and make these banks fight for your business!
Watch this quick video walkthrough to discover proven ways to secure the absolute lowest mortgage interest rate before you sign your loan!
Advanced Rate-Slashing Secrets Used by Financial Pros
Once you have cleaned up your credit score and gathered your down payment savings, you can use advanced rate-slashing strategies. Experienced real estate investors use specific financial tactics to squeeze the lowest possible interest rate out of competitive mortgage lenders.
Most traditional home buyers wait until a seller accepts their purchase offer before locking in an interest rate. However, if market interest rates are rising rapidly, waiting until you find a property exposes you to daily rate increases.
Ask your mortgage lender for a Lock-and-Shop rate agreement before you even start touring open houses. A Lock-and-Shop program allows you to freeze current interest rates for thirty to ninety days while you comfortably shop for a home.
If you are currently juggling multiple loan types, managing your monthly obligations is essential to getting the best mortgage rate. Reviewing the differences between federal vs private student loans can help you structure your existing debt more efficiently before talking to a lender.
Interest rates are never set in stone, and lenders often have flexibility to adjust their pricing to close a deal. When comparing competing Loan Estimates, look closely at Box A charges, which include processing and origination fees.
If one lender offers a slightly lower interest rate but charges two thousand dollars in origination fees, ask a competing bank to match that rate without the extra fees. Lenders frequently issue lender credits to cover closing costs if they know you are actively comparing quotes with rival banks.
Another incredible option is a temporary rate buydown, where the home seller pays money upfront to reduce your interest rate for the first few years. The most common option is a two-one buydown, which lowers your interest rate by two percent in the first year and one percent in the second year.
By the third year, your mortgage rate resets to your permanent locked base rate for the remaining loan term. This temporary reduction gives you significantly lower monthly payments during your first two years in the home when moving expenses are highest.
Before committing all your cash to buy points or secure down payments, focus on building a bulletproof emergency fund. Protecting your new investment is just as important as getting a low rate, so be sure to check out how to choose your first home insurance policy without stress.
Severe Mistakes That Drive Up Your Mortgage Interest Rate
Trying to secure the lowest mortgage interest rate requires disciplined money management until the final closing papers are signed. Making simple errors during underwriting can cause lenders to raise your interest rate or cancel your rate lock completely.
Making Large Credit Purchases During the Rate-Lock Window
One of the most dangerous mistakes you can make after locking in your interest rate is applying for new credit lines. Buying new furniture, appliances, or a vehicle on credit triggers hard inquiries and increases your total monthly debt load.
Lenders perform a final credit check right before issuing your final loan approval. A sudden drop in your credit score or an increase in your monthly debt ratio can immediately invalidate your locked interest rate tier.
Focusing Only on Rates While Ignoring Origination Fees
A low interest rate quote can be incredibly misleading if the lender hides steep administrative charges in your closing disclosure paperwork. Some online lenders advertise eye-catching interest rates but charge thousands of dollars in hidden processing fees.
Always evaluate the Annual Percentage Rate (APR) alongside the advertised interest rate. The APR combines the base interest rate with lender fees, giving you a complete picture of the real, long-term loan cost.
Changing Employment or Income Structure Mid-Application
Bank underwriters calculate your interest rate based on verified, stable income streams covering two full years. Switching jobs, leaving a salaried position for commission-based pay, or starting a business mid-application creates massive underwriting red flags.
Even if your new job offers a higher salary, changing employers right before closing can void your pre-approval or increase your rate tier. Underwriters always treat job changes as added financial risk, which translates directly into higher borrowing rates.
Your Blueprint for Securing Maximum Mortgage Savings
Getting the lowest mortgage interest rate is not a matter of luck or timing the market perfectly. It is the result of taking deliberate, strategic steps to optimize your credit, lower lender risk, and force banks to compete for your loan.
- Request free credit reports from all major bureaus and dispute any reporting errors right away.
- Pay down revolving credit card balances to drop your credit utilization below ten percent.
- Save toward a larger down payment to lower your Loan-to-Value ratio and eliminate PMI costs.
- Request official Loan Estimates from at least four different lenders and compare total APR numbers.
- Lock in your rate with a float-down guarantee and keep your financial profile completely stable until closing day.
Getting a lower interest rate on my house changed my entire financial outlook, and seeing those monthly savings stay in my bank account gives me great comfort every day. I want you to experience that exact same peace of mind when you finally unlock your front door.
You do not need to settle for the first expensive quote you receive from a local bank. Pull your credit reports today, clean up your small debt balances, and confidently make lenders compete for your business right now!
Internal Links Integration Check
- How to Improve Your Credit Score Before Applying for a Mortgage
- Federal vs Private Student Loans Guide
- How to Choose Your First Home Insurance Policy Without Stress
Frequently Asked Questions
How often do mortgage interest rates change during the day?
Mortgage interest rates actually fluctuate daily based on national bond market movements and economic inflation reports. On highly volatile economic days, lenders may reprice their interest rates multiple times before the business day ends.
Is a 15-year mortgage rate always lower than a 30-year rate?
Yes, 15-year fixed mortgages almost always offer lower interest rates compared to 30-year mortgages. Because the lender gets their money back twice as fast, they take on much less long-term risk.
Should I pay for mortgage discount points to lower my rate?
Buying discount points makes sense if you plan to stay in the home for a long time. You should always calculate your breakeven point to ensure the upfront cost is worth the long-term monthly savings.
Can a lender change my rate after I lock it in?
Once you sign a rate lock agreement, your interest rate is protected from market increases for the duration of the lock period. However, if your credit score drops or your debt ratio changes before closing, the lender can still adjust your rate.
Does shopping with multiple lenders hurt my credit score?
No, shopping around for a mortgage will not destroy your credit score. Credit bureaus group multiple mortgage inquiries made within a short 14-to-45 day window into one single event to protect consumers.
Disclaimer
The information provided in this article is for educational and informational purposes only and should not be considered formal financial, legal, or lending advice. Mortgage interest rates, lender fees, underwriting criteria, and rate-lock policies change daily and vary based on individual creditworthiness, loan types, and market conditions. Always consult with a licensed mortgage professional or certified financial planner before making binding financial commitments.


