The Emotional Rollercoaster of Real Estate Escrow
I still remember the overwhelming panic I felt when my real estate agent told me to wire my life savings to a complete stranger. My hands were literally shaking as I stood in the bank lobby, terrified that my hard-earned money would simply vanish into a fraudulent account. The beautiful dream of buying a home quickly morphed into a stressful nightmare of confusing legal jargon and endless paperwork.
I kept hearing complex terms like "earnest money," but no one took the time to explain what they actually meant to my wallet. This intense fear of losing my deposit almost made me walk away from the perfect house for my growing family. Thankfully, I took a step back, educated myself on how these holding accounts actively protect buyers, and finally felt a massive wave of relief.
Understanding this system allowed me to sign my final closing papers with absolute confidence instead of paralyzing fear. Purchasing a home is a deeply emotional milestone filled with visions of creating a safe haven and building generational wealth. But as you navigate the homebuying journey today, confronting complex real estate terminology can easily cause sudden anxiety.
You worry whether your initial deposit is safe, who actually holds your funds, and if unexpected costs will derail your purchase. Understanding escrow is never about memorizing boring financial theory. It is about gaining complete confidence that your money is protected by a neutral authority while you step safely toward homeownership.
In United States real estate transactions, this specialized legal mechanism relies on a neutral third party. They hold financial funds, legal documents, or property assets on behalf of both the home buyer and the seller. This continues until specific contractual conditions are completely satisfied by everyone involved.
Think of this process as a mandatory financial safety net. Transferring hundreds of thousands of dollars directly to a seller before receiving clean legal ownership creates immense risk for the buyer. Conversely, handing over a property deed before receiving guaranteed funds creates equal risk for the seller.
Demystifying Escrow and the Closing Process
Escrow essentially eliminates transactional risk by ensuring that no money or property changes hands prematurely. Funds are securely locked until all legal contingencies, home inspections, title searches, and loan approvals are fully completed. To navigate the process smoothly, every homebuyer must understand that this system serves two completely distinct functions.
The first is Transactional Escrow, which occurs before closing day. This is the neutral holding account used during the purchase process to hold earnest money deposits and manage funds. The second is the Mortgage Escrow Account, which operates long after you move in.
Transactional vs. Mortgage Escrow
Escrow: Myth vs. Reality
- Myth: The seller gets to keep your deposit immediately if you change your mind.
- Reality: Your deposit is refunded if you cancel based on a valid contract contingency.
- Myth: You pay extra monthly fees to have a mortgage escrow account.
- Reality: Lenders do not charge administrative fees to run your tax and insurance impound account.
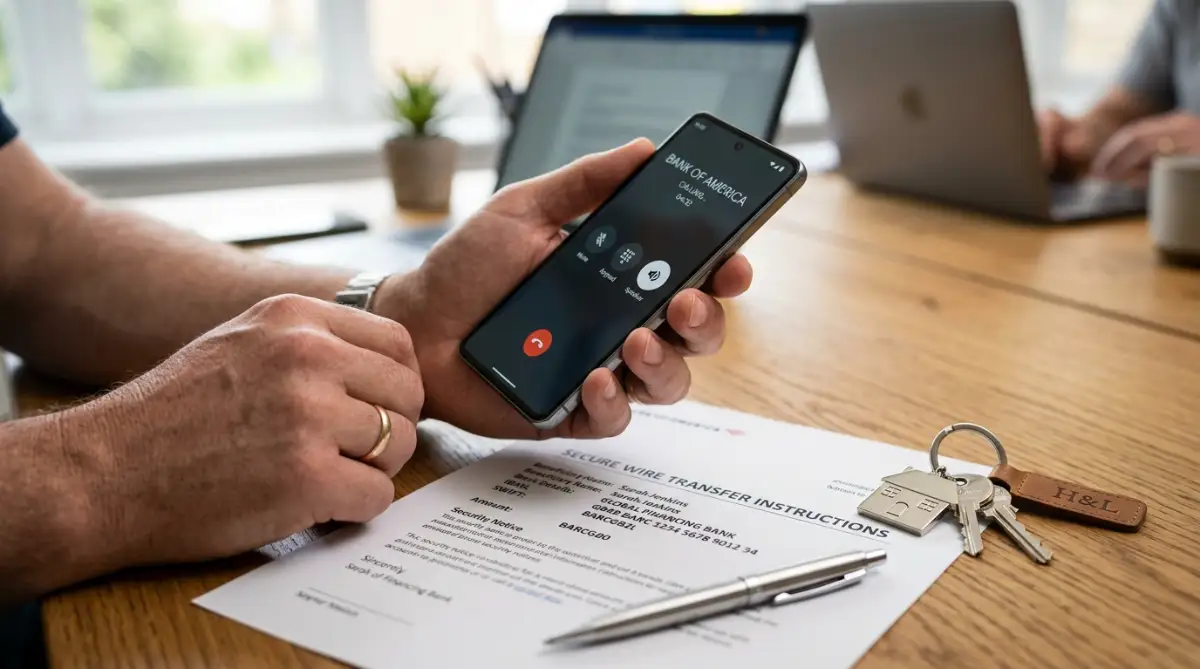
My Personal Pro Tip: When I was in the middle of closing on my house, I received an email with wire instructions that looked incredibly authentic. My gut told me to call my escrow officer directly, and I discovered the email was actually a sophisticated scam! I always tell my friends to verbally verify every single wiring instruction over the phone before sending a dime.
Watch this informative real estate video guide explaining the mechanics of escrow accounts:
Advanced Tips for Navigating the In-Escrow Phase
Being "in escrow" typically lasts between 30 and 45 days. During this active period, the closing officer and transaction team coordinate several essential milestones. Staying organized during this phase is the key to an on-time settlement.
The title company examines public land records to verify that the property is free of unrecorded liens. They also check for unpaid back taxes or boundary disputes before issuing title insurance commitments. This guarantees that nobody else can claim ownership of your new home.
Independent inspectors will evaluate the home's structural integrity, roof, plumbing, and electrical systems. Meanwhile, your lender orders a formal property appraisal and completes full loan underwriting. You must promptly submit any requested bank statements to keep this process moving.
Wiring closing funds and paying appraisal fees can temporarily strain your household liquidity. Ensuring you maintain adequate liquid cash cushions prevents panic while waiting for closing day. You never want to drain your savings account entirely before moving in.
Balancing your daily living expenses with these sudden real estate costs requires strict budgeting. Evaluating your household obligations is much like deciding between federal vs private student loans how to choose wisely to keep debt manageable. Managing your debt gives you the breathing room needed to navigate the closing process calmly.
Once you close on your home, transactional escrow ends, and your ongoing mortgage escrow account begins. Your lender wants absolute assurance that the property's annual real estate taxes and insurance premiums are paid. This protects their collateral from tax liens or fire damage.
Every month, your total mortgage payment includes a fraction of your annual property tax bill. It also includes a portion of your homeowners hazard insurance premium held safely in reserve. These funds sit untouched until the exact due date.
Knowing how to choose your first home insurance policy without stress helps keep this monthly payment low. When these annual bills come due, your mortgage servicer pays them directly out of your account. This takes the administrative burden completely off your shoulders.
Mortgage lenders are legally required to conduct an annual analysis every 12 months to review your balance. Because local municipal property tax rates fluctuate over time, your account balance will naturally adjust. These adjustments happen to almost every homeowner.
If property taxes or insurance premiums increase during the year, you will experience an escrow shortage. Lenders will notify you in writing, giving you options to pay the lump-sum shortage upfront. Alternatively, you can simply spread the shortage over the next 12 monthly payments.
Some experienced homeowners prefer to pay their property taxes and insurance bills directly. However, lenders enforce strict rules regarding these escrow waivers. Government-backed loans usually mandate these accounts for the entire lifetime of the mortgage.
You usually need a minimum 20% equity and a fantastic credit history to request this waiver. Understanding how to improve your credit score before applying for a mortgage is the best way to secure this option. Excellent credit proves to the lender that you are highly responsible.
Managing monthly credit card obligations alongside your newly adjusted mortgage payment is essential. A sudden tax shortage can catch even the most diligent savers entirely off guard. Protecting your long-term financial health requires anticipating these yearly adjustments.
If you receive a refund check due to an overage, resist the urge to spend it frivolously. Smart homeowners deposit these refunds directly into their emergency house fund. This simple habit protects you against future property tax hikes down the road.
On the actual closing day, the escrow officer compiles all financial adjustments into a final document. The buyer wires the remaining down payment and closing cost funds directly into the account. Once all funds are verified, the agent officially hands over the keys.
Dangerous Escrow Mistakes First-Time Homebuyers Must Avoid
Real estate wire fraud is one of the fastest-growing cybercrimes in the United States today. Cyber criminals hack into title company email accounts, sending fake wire instructions to unsuspecting buyers during closing week. Always call your escrow officer directly using an independently verified phone number before sending any money.
Making major credit purchases while under contract is another massive mistake. Buying cars or new furniture on credit increases your debt-to-income ratio instantly. This simple action can easily trigger a mortgage denial right before closing day.
Ignoring annual escrow analysis notices is a trap that hurts many new homeowners. Throwing away these lender statements means you might be blindsided by sudden monthly payment increases due to property tax hikes. Always open mail from your mortgage servicer immediately to review your balances.
Finally, never waive your inspection contingencies too early in the process. Releasing these protections before independent inspectors evaluate the electrical or roofing systems leaves you vulnerable to hidden damages. Let the process play out fully to protect your earnest money deposit.
Your Secure Path to Homeownership
Escrow is a fundamental protective structure in real estate that safeguards buyers, sellers, and lenders alike. By understanding how earnest money deposits are managed, verifying wire instructions carefully, and budgeting for annual adjustments, you protect your investment. You can easily navigate the home buying process with complete confidence.
I know firsthand how intimidating the closing process can feel when you are staring at stacks of legal paperwork. However, my personal journey taught me that educating yourself is the best way to protect your family's financial future. I hope this guide helps you approach your closing day with the exact same confidence I eventually found.
Internal Links Integration Check
- Successfully linked: Federal vs private student loans how to choose wisely
- Successfully linked: How to choose your first home insurance policy without stress
- Successfully linked: How to improve your credit score before applying for a mortgage
Frequently Asked Questions
What happens to my earnest money if the seller backs out?
If the seller defaults or backs out of the contract without a legal reason, your earnest money is fully protected. The escrow agent will refund your entire deposit back to you. You may also have grounds to sue the seller for breach of contract.
Do I earn interest on the money sitting in escrow?
In most states, transactional escrow accounts for earnest money do not pay interest to the buyer. However, a few states do require mortgage lenders to pay a small amount of interest on post-closing mortgage impound accounts. Check your local state laws to see if you qualify for these minor interest payments.
How much does the escrow company charge for their services?
Escrow fees typically range from 1% to 2% of the total home purchase price. These administrative costs are usually split evenly between the buyer and the seller, depending on local real estate customs. You will see the exact fee breakdown on your final Closing Disclosure.
Can an escrow account cause my mortgage payment to change?
Yes, your monthly payment will absolutely fluctuate over the years because of your impound account. If your local property taxes or insurance premiums increase, your lender will raise your monthly payment to cover the difference. This is completely normal and happens to most homeowners annually.
Who chooses which title or escrow company to use?
The choice of escrow company is entirely negotiable between the buyer and the seller. In many markets, the seller or their real estate agent will suggest a preferred company. However, the buyer always has the legal right to shop around and request a specific provider.
General Informational & Legal Disclaimer
Disclaimer: The information provided in this article is for general informational, educational, and entertainment purposes only and does not constitute formal real estate, legal, mortgage underwriting, tax, or financial advice. Reading this article or interacting with this website does not establish a professional-client or fiduciary relationship. Escrow laws, title insurance regulations, property tax assessment rules, and mortgage impound requirements vary significantly across different US states, counties, and local municipalities. If you are preparing to buy or sell real estate, you should consult directly with a licensed escrow officer, real estate broker, mortgage loan officer, and real estate attorney in your area to receive guidance tailored to your specific financial situation.