How a Sudden Home Emergency Taught Me the True Power of Fast Online Cash
Three years ago, my home heating system completely broke down in the middle of a freezing January in Chicago. I checked my checking account and realized I only had four hundred dollars to my name after paying monthly bills.
The HVAC repair company quoted me three thousand two hundred dollars for an immediate emergency replacement. My heart sank into my stomach as I stood in my freezing living room wondering how I was going to keep my family warm.
I walked into my local traditional bank branch the next morning hoping for a quick loan. The loan officer handed me a pile of paperwork and told me processing would take two to three business weeks.
I could not wait three weeks while my home temperature kept dropping below freezing every night. I felt completely trapped, stressed out, and terrified of taking on a predatory payday loan with crazy interest rates.
That evening, a close friend recommended I look into soft-credit online personal loan platforms. I filled out a digital pre-qualification form on my phone, got approved in two hours, and had funds deposited the next morning.
That experience completely changed how I view modern financial technology. Today, I want to walk you through how fast approval unsecured personal loans work so you can handle unexpected emergencies safely.
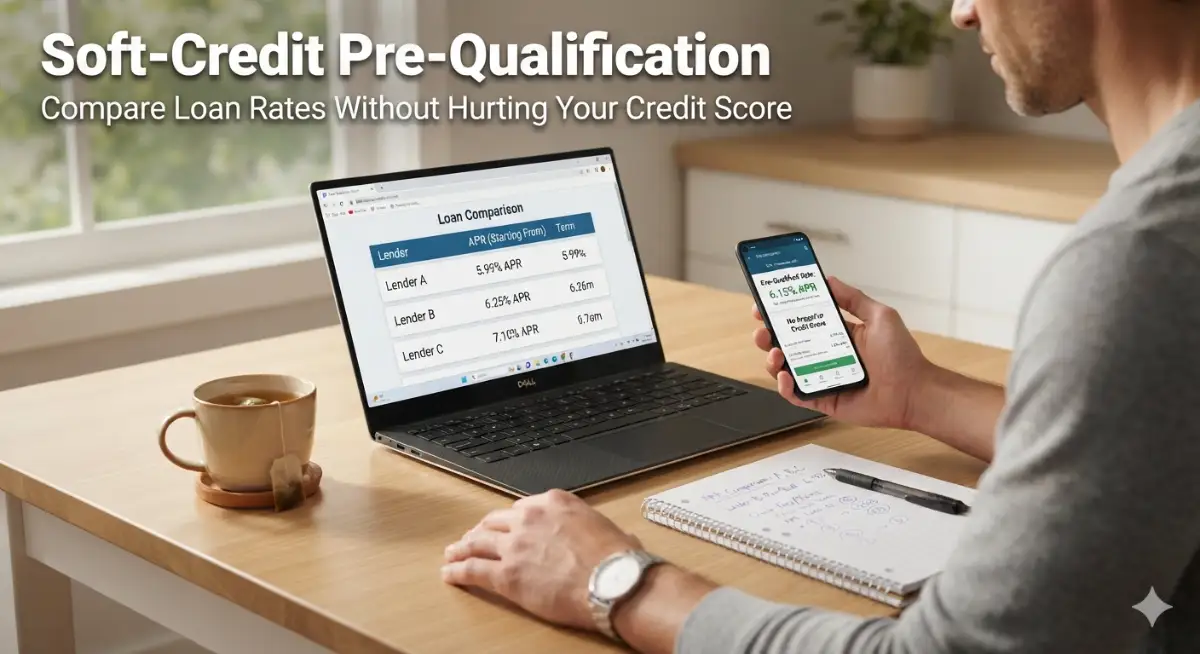
Unexpected financial turning points happen to almost every household in the United States at some point. Whether you are facing a sudden medical bill, an unexpected car repair, or high-interest credit card debt, quick funding options matter.
Traditional bank loan processes with paper applications and long waiting periods are often completely impractical during emergency situations. When bills are due immediately, waiting weeks for a credit decision causes unnecessary panic and stress.
This operational delay explains why millions of American consumers rely on fast approval unsecured personal loans online. Powered by modern fintech platforms, online personal loans have transformed how people borrow money in times of need.
Online lenders use automated underwriting systems to evaluate creditworthiness quickly. They offer soft-credit pre-qualification in minutes and deposit funds directly into your bank account as fast as the same day.
Best of all, unsecured loans require zero physical collateral. You do not have to risk your house, car, or personal savings account just to secure emergency funding.
In this guide, we will break down how online personal loans work, evaluate Annual Percentage Rates, explain credit checks, and help you find a safe lender.
Understanding Unsecured Personal Loans and No-Collateral Borrowing
To borrow money safely, you must understand the legal difference between secured loans and unsecured loans. Knowing how these two loan types work protects your personal property from unexpected risk.
A secured loan requires you to pledge a physical valuable asset as collateral before receiving money. If you fail to make your payments, the lender can legally seize your asset through repossession or foreclosure.
An unsecured personal loan is approved based on your income stability, credit score, and financial history. Zero physical assets are pledged, which keeps your home and vehicle completely safe if financial hardship happens.
Secured Loans vs. Unsecured Personal Loans
Secured loans include vehicle title loans, home equity loans, and pawn shop loans. While they may offer lower credit requirements, the risk of losing your car or home is very high if you face job loss.
Unsecured loans offer a safer alternative for consumers who want clear payment terms without putting personal property on the line. You receive a fixed lump sum of cash up front and repay it through equal monthly payments over a fixed timeframe.
Most reputable online lenders also offer soft-credit pre-qualification before you submit a formal application. A soft credit check lets you view your personalized interest rates and monthly payment options without hurting your FICO score.
Evaluating Key Financial Metrics: APRs, Fees, and Credit Tiers
When comparing online personal loan offers, looking beyond the monthly payment number is essential. Evaluating the total cost of borrowing ensures you choose an affordable loan that fits your budget.
The Annual Percentage Rate (APR) represents the true cost of borrowing money over a full year. Unlike simple interest rates, the APR includes the base interest charge plus any required lender fees like origination charges.
Some online lenders charge an upfront origination fee ranging from 1% to 8% of your total loan amount. This fee covers administrative processing and is deducted directly from your initial loan deposit.
For example, if you borrow $10,000 with a 5% origination fee, the lender deposits $9,500 into your account while you repay the full $10,000 balance. Always look for lenders that offer zero prepayment penalties so you can pay off your loan early to save money.
Online Personal Loan Rates by FICO Credit Tier
Debunking Common Personal Loan Myths
- Myth 1: Checking your personalized loan rates online will damage your credit score.
- Reality: Soft-credit pre-qualification allows you to check rates with multiple online lenders with zero impact on your credit score. A hard credit inquiry only happens when you formally accept a loan offer.
- Myth 2: Online lenders are not as safe or regulated as traditional brick-and-mortar banks.
- Reality: Reputable online lenders are fully licensed, subject to state lending caps, and protected by bank-level encryption standards just like major traditional institutions.
- Myth 3: You can only use a personal loan for home improvements or car repairs.
- Reality: Unsecured personal loans offer flexible usage, allowing you to pay medical bills, consolidate high-interest credit cards, or cover emergency household expenses.
My Personal Pro Tip: Whenever I need emergency cash or want to consolidate debts, I always fill out soft-credit pre-qualification forms with at least three different online lenders first. Comparing multiple pre-qualification offers side-by-side lets me pick the lender with the absolute lowest APR and zero origination fees before any hard credit check happens!
If you want a detailed video breakdown on how fast approval online personal loans work, watch this video below:
Advanced Strategies to Lower Your Borrowing Costs and Pay Off Debt Faster
Securing a fast approval unsecured personal loan is a major milestone, but using advanced management strategies helps you save even more money over time. Strategic planning transforms emergency borrowing into a stepping stone toward long-term financial stability.
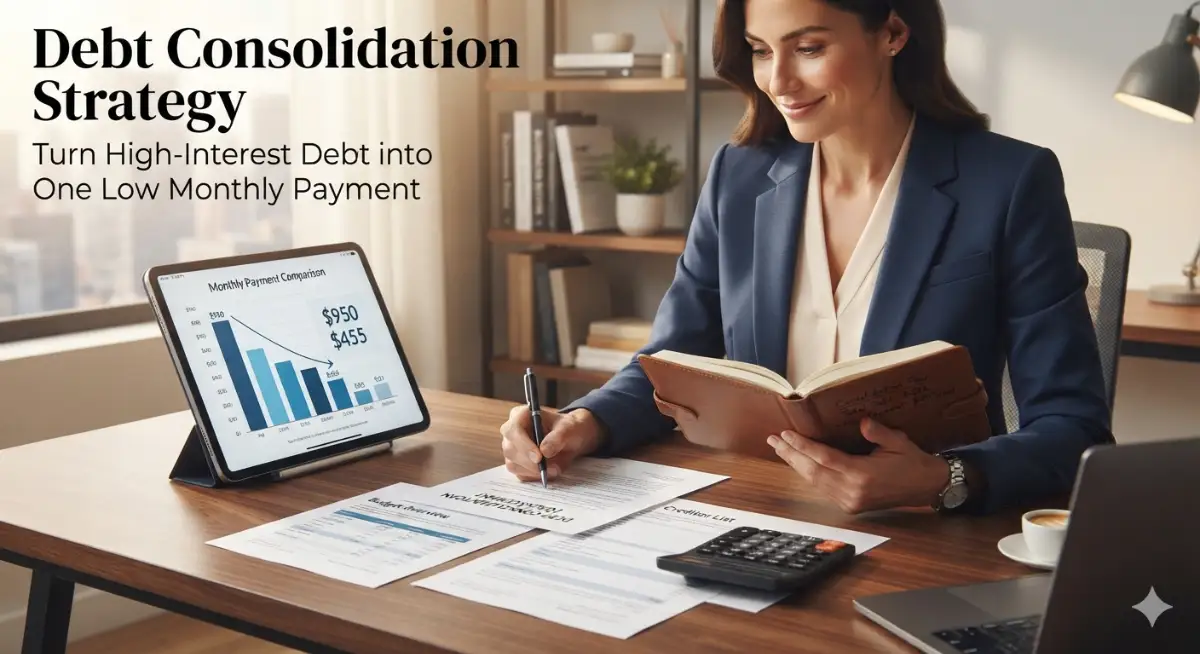
The first advanced strategy is using an unsecured personal loan for high-interest credit card debt consolidation. Credit cards usually carry variable interest rates that can exceed 25% to 30% APR, making minimum payments almost useless.
By replacing multiple high-interest credit card balances with a single fixed-rate personal loan at 11% or 14% APR, you immediately reduce your monthly interest expenses. This strategy locks in a predictable monthly payment schedule, allowing you to become completely debt-free much faster.
The second strategy is setting up automatic monthly loan payments from your checking account. Most major online personal loan platforms offer a 0.25% to 0.50% APR discount when you enroll in automated autopay systems.
Automated payments ensure you never miss a due date, which protects your credit score from late-payment marks while lowering your overall interest charges. It removes the hassle of remembering due dates every single month.
The third strategy is working to improve your credit standing before applying whenever possible. Raising your credit score by just thirty points can move you into a better credit tier with significantly lower APR offers.
If you are planning major life financial goals, learning how to improve your credit score before applying for a mortgage provides valuable insights into building a healthier credit profile.
Similarly, taking time to safeguard your physical assets gives you ongoing peace of mind during emergency situations. Learning how to choose your first home insurance policy without stress protects your property against sudden structural damage or storm loss.
If you are balancing educational expenses or family budgets alongside personal loans, organizing your debts is necessary. Reviewing federal vs private student loans: how to choose wisely helps you make smart decisions about higher education debt.
Students enrolled at the best community colleges in the USA for affordable education often avoid heavy student loan burdens by keeping their tuition costs low from the start.
Finally, if you manage a small business or side hustle to earn extra income, keeping overhead low protects your monthly cash flow. Utilizing easy AI website builders for small businesses allows you to build a professional website quickly without spending thousands on developers.
Major Pitfalls to Avoid When Borrowing Personal Loans Online
While fast approval online personal loans offer incredible convenience, making hasty decisions during an emergency can lead to costly mistakes. Being aware of common borrowing traps protects you from predatory loan offers.
The most dangerous pitfall is falling for high-cost payday loans or car title loans that promise no credit checks. These predatory lenders often charge hidden fees and interest rates exceeding 300% to 400% APR, trapping borrowers in endless cycles of debt.
Always verify that an online lender is legally licensed to operate in your state and follows official state interest rate caps. Reputable lenders always require income verification and display their APR disclosures clearly.
Another common mistake is submitting formal loan applications to five or six different lenders all at once. Every formal application triggers a hard credit inquiry, which temporarily lowers your credit score by a few points.
Instead, use soft-credit pre-qualification tools to compare rates safely without damaging your credit profile. Only submit one formal application after selecting the offer with the best terms.
Lastly, avoid borrowing more money than you actually need for your emergency expense. Taking on extra debt just because a lender approves a higher limit increases your monthly payment burden unnecessarily.
Taking Control of Your Financial Journey Today
Fast approval unsecured personal loans online offer a safe, transparent, and flexible way to handle life's unexpected financial challenges. By choosing no-collateral options, you protect your valuable personal property while securing necessary emergency cash.
Remember to compare APRs, check for origination fees, and use soft-credit pre-qualification to find the best lender for your situation. Replacing high-interest credit card debt with a fixed-rate loan gives you a clear path toward financial freedom.
I know how stressful it can feel when unexpected emergency expenses pop up out of nowhere. Taking control of your personal finances with smart, transparent borrowing gives you peace of mind, and I am always here to help you navigate your journey toward total financial freedom!
Frequently Asked Questions About Fast Approval Online Personal Loans
How quickly can I receive funds from an online personal loan?
Many leading online personal loan platforms offer same-day approval and can deposit funds into your bank account as fast as the next business day. Approval speed depends on how quickly you verify your income and banking details.
Can I get an unsecured personal loan with a fair or bad credit score?
Yes, many online lenders specialize in fair or bad credit personal loans for borrowers with FICO scores below 670. These lenders focus on your income stability and debt-to-income ratio, though APRs will be higher than for excellent-credit borrowers.
Will pre-qualifying for a personal loan affect my credit score?
No, pre-qualifying for a personal loan uses a soft credit inquiry, which has zero impact on your credit score. A hard credit inquiry only occurs when you formally accept the loan offer and submit your final application.
What is the difference between an interest rate and an APR on a personal loan?
An interest rate measures only the base percentage charged on the borrowed money. An Annual Percentage Rate (APR) includes both the interest rate and any required lender fees (such as origination fees), showing the true total cost of the loan.
Can I pay off my online personal loan early to save on interest?
Yes, most reputable online personal loan lenders allow you to pay off your loan early without charging any prepayment penalties. Paying off your principal balance early reduces total interest charges over the life of the loan.
Category Disclaimer
The information provided in this article is for educational and informational purposes only and does not constitute formal financial, legal, or lending advice. Personal loan interest rates, APRs, lender terms, and eligibility requirements vary based on individual credit profiles and state laws. Always consult with a certified financial planner or licensed loan advisor before signing binding loan contracts.