The Credit Card Confusion: Why Most People Pick the Wrong Card
When I applied for my first credit card, I spent hours staring at flashy travel reward ads thinking I was going to fly around the world for free. I ended up signing up for a card with a sixty-dollar annual fee that I barely used, and my points expired before I could even redeem them. That embarrassing mistake taught me a big lesson about choosing simple cash back over complicated points when you are just starting out. I remember sitting at my desk feeling completely tricked by marketing hype, wishing I had chosen a straightforward card. That frustrating journey pushed me to understand how card terms actually function behind the scenes. Once I learned to align my plastic with my real budget, managing my money became completely stress-free.
Imagine opening your banking app or walking into a bank branch, ready to build your credit score. You are immediately flooded with flashy advertisements promising travel points, free flight upgrades, and cash bonuses.
You feel excited at first, but that excitement quickly turns into deep confusion. You wonder if those fancy reward points are actually worth anything or if plain cash back in your account is better.
Why finding the truth about credit cards is so hard:
- Marketing campaigns push high-fee travel points cards to beginners who do not spend enough to cover those fees.
- Complex point valuation systems trick cardholders into thinking thousands of points equal thousands of dollars.
- Confusing redemption rules lead people to forfeit unused points or spend them on low-value gift cards.
- Online financial forums offer conflicting advice that leaves first-time cardholders overwhelmed and stuck.
How reward confusion impacts your peace of mind:
- Fear of making the wrong financial decision prevents people from starting their credit-building journey.
- Anxiety over hidden annual fees creates constant stress every time a monthly statement arrives.
- Feeling foolish after redeeming thousands of hard-earned points for barely any real-world value.
- Comparing your basic credit card to luxury travel cards on social media creates unnecessary regret.
I understand how confusing this choice feels when you are starting from scratch. Credit card companies design their reward programs using complicated terms on purpose.
They want you to focus on shiny sign-up bonuses so you overlook annual fees and redemption limits. When you do not understand the mechanics of points versus cash back, you risk picking a card that hurts your budget.
You end up spending extra money on things you do not need just to earn a small handful of reward points. What you need is a plain-English explanation that cuts through the marketing hype and gives you complete control over your money.
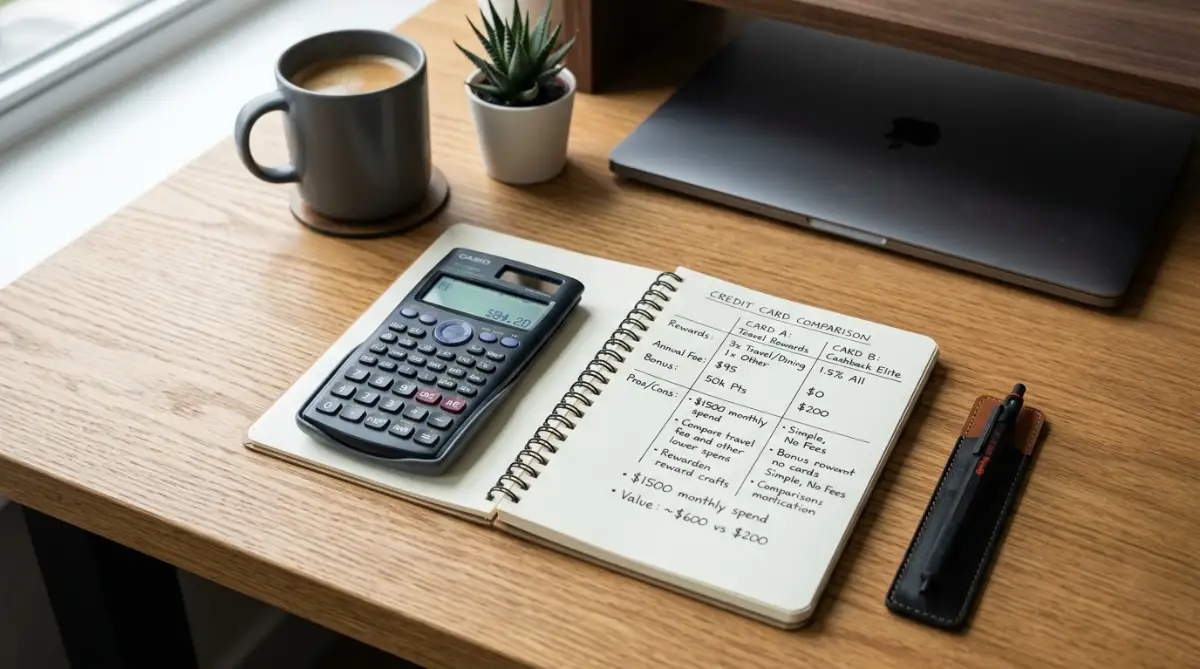
A Clear Breakdown of Cash Back vs Rewards Points
Let us strip away the clever advertising and look at how these two main types of credit cards actually work in the real world. Once you see how cash back and reward points function side by side, your choice becomes simple.
Core Reward System Mechanics
Evaluating value certainty, annual fee structures, and redemption flexibility ensures you select a card that aligns with your real everyday budget.
Comparing Cash Back and Reward Points
Myth vs Reality: Credit Card Rewards
Myth: "Reward points cards are always superior because they offer luxury travel perks and flight upgrades."
Reality: For beginner cardholders with standard monthly budgets, cash back cards usually provide higher net savings and far fewer hidden fees.
My Personal Pro Tip: As a beginner, I always recommend avoiding cards with annual fees during your first year of building credit. Choosing a no-fee cash back card lets you build a strong credit history without paying a single dollar in mandatory annual charges. To ensure your profile is fully prepared before submitting applications, you can also review our guide on how to improve your credit score.
Watch this quick video to learn how to choose the right credit card based on your spending habits and financial goals:
Smart Maximization Tactics for First-Time Cardholders
Once you decide between cash back and reward points, you need practical strategies to get the highest value out of your new card. Managing your card wisely ensures you collect maximum benefits while protecting your financial health. One of the easiest ways to use cash back earnings is applying them directly as a statement credit against your monthly bill. I used to hoard my earned cash back for months thinking I would save it for something special, but I completely forgot about it until my account almost got marked inactive. Now, I set up automatic statement credit redemptions every time my balance hits twenty dollars so my rewards reduce my monthly balance automatically. If you are balancing student loans or educational expenses alongside your card management strategy, reviewing insights on federal vs private student loans helps you manage overall debt obligations safely.
As your credit score grows over time, you can upgrade your setup by pairing two complementary cards together. A two-tier strategy helps you earn higher rewards on big spending categories while capturing baseline cash back on everything else. For small business owners or freelancers managing commercial credit card accounts, you can explore resources on easy AI website builders for small businesses to establish professional online branding and extra revenue streams. Furthermore, pairing low credit card usage with a solid financial safety net keeps you prepared for sudden life expenses. Spending time building a bulletproof emergency fund fast gives you the cash cushion needed to avoid carrying a credit card balance during unexpected emergencies.
For students or young adults looking into affordable ways to continue their education without accumulating toxic debt, researching options like best community colleges in the USA provides affordable avenues for academic growth. For related insights on safeguarding your personal assets and insurance standing against unexpected liability, check out tips on how to choose your first home insurance policy without unnecessary anxiety. Keeping your financial records organized and your reward strategies focused protects your purchasing power for major life decisions.
 Credit Card Pitfalls That Cost Beginners Hundreds
Getting your first credit card is an exciting financial milestone, but small mistakes can quickly cost you real money. Avoiding these common traps keeps your credit rating high and prevents costly interest charges.
Carrying a Balance Just to Earn Reward Points
The biggest trap for beginners is spending extra money on a card just to collect cash back or points while carrying a monthly balance subject to heavy interest rates.
Applying for Multiple Credit Cards at the Same Time
When beginners get excited about building credit, they often apply for three or four different credit cards in a single week, triggering hard inquiries that lower their credit score.
Simple Do's and Don'ts for Card Success
- Do pay your full statement balance before the due date every single month.
- Do choose cards that match your top spending categories naturally.
- Do track your points so you can redeem them before they expire.
- Don't buy extra things just to earn bonus points or sign-up rewards.
- Don't carry a monthly balance or pay credit card interest fees.
- Don't pay high annual fees for travel perks you will not use.
Your Action Plan for Choosing the Right Card Today
Choosing between cash back and rewards points comes down to knowing your personal spending style and financial goals. You do not need to overcomplicate your decision to build a strong credit foundation.
- Check Your Credit Score: Know your exact score tier before browsing credit card offers online.
- Audit Your Expenses: Review recent bank statements to identify your top spending categories.
- Compare Net Values: Calculate the actual dollar return after subtracting any annual fees.
Choosing your first credit card can feel scary at first, but taking control of your daily spending is the absolute best way to build strong credit. You do not need a complex points strategy to win with credit cards, so pick a simple card today and watch your confidence grow every single month. Believe in your financial decisions, choose the card that fits your real lifestyle today, and enjoy the cash-back rewards you deserve!
Recommended Reading Resources
Explore these internal guides to master your overall financial strategy:
- How to Improve Your Credit Score Before Applying for a Mortgage
- Federal vs Private Student Loans Guide
- How to Choose Your First Home Insurance Policy Without Stress
- Easy AI Website Builders for Small Businesses Simple Setup Guide
- Best Community Colleges in the USA for Affordable Education
Frequently Asked Questions
Can I change my mind after picking a rewards card?
Yes, you can change your card strategy at any time by calling your bank and asking to switch your account to a different product version.
Does redeeming cash back count as taxable income?
In most cases, credit card cash back is treated as a purchase discount rather than taxable income by tax authorities.
Is cash back better than points for beginners?
Yes, cash back is ideal for beginners because the value is guaranteed and simple with zero complex redemption rules.
Should I close my first credit card after upgrading?
No, keep your oldest card open to maintain your credit history length and overall available credit limit, especially if it has no annual fee.
How many credit cards should I have?
Most financial experts recommend having two to three well-chosen credit cards to maximize rewards across key spending categories safely.
Disclaimer: This article is strictly for educational and informational purposes and does not constitute formal financial, tax, or legal advice. Credit card terms, interest rates, annual fees, and reward structures vary depending on card issuers and individual applicant credit profiles. Always read the official credit card agreement and terms from the issuing bank before submitting a formal application.


