The Stressful Crossroads of Choosing a Home Loan Structure
When I bought my first house, I spent sleepless nights staring at loan paperwork, terrified that choosing the wrong interest rate would wreck my monthly budget. My bank officer kept pushing a low introductory rate, but I was scared that a sudden rate increase down the road would make my house unpayable. That stressful experience forced me to break down how fixed and adjustable loans actually work so I could protect my family's financial future. I remember feeling paralyzed by all the conflicting opinions online while my house offer deadline ticked closer. Taking the time to master mortgage math gave me the clarity I needed to sign my loan papers with confidence. That journey taught me how to choose a home financing structure that brings absolute peace of mind.
Imagine sitting at your kitchen table surrounded by stacks of home loan application forms and financial projections. You are thrilled to purchase your dream house, but choosing between a fixed-rate mortgage and an adjustable-rate mortgage feels completely terrifying.
You wonder if picking the wrong loan will lock you into unnecessarily high payments or trigger a sudden rate hike that ruins your monthly budget. This nagging doubt leaves thousands of homebuyers paralyzed during the financing process.
Why finding the right mortgage answers feels so hard:
- Lenders push adjustable-rate options with low teaser rates without clearly explaining future rate caps and adjustment periods.
- Popular financial forums offer conflicting advice that assumes every homebuyer plans to stay in their home for thirty full years.
- Online mortgage calculators often hide long-term interest rate adjustments beneath overly optimistic economic assumptions.
- Assuming interest rates will always fall leads buyers to take unnecessary financial risks with adjustable loan structures.
How loan uncertainty ruins your peace of mind:
- Fear of fluctuating monthly mortgage payments creates constant sleep-depriving financial anxiety.
- Uncertainty over long-term home costs makes it almost impossible to plan family budgets or retirement savings.
- Doubt over choosing an adjustable loan makes every economic news headline feel like a threat to your home security.
- Feeling overwhelmed by complex lending jargon damages your confidence during real estate offer negotiations.
I know how overwhelming this decision feels when you are standing on the brink of homeownership. Selecting a mortgage structure is far more than picking a simple interest percentage on a sheet of paper.
It is a choice that dictates your monthly cash flow, your family savings rate, and your long-term peace of mind. When you do not understand how fixed and adjustable loan mechanics work, you feel vulnerable to predatory lending traps.
You end up worrying whether a future economic shift will force you out of your home. The good news is that you do not need to be a financial expert to master these loan types.
Once you understand how rate caps, adjustment intervals, and fixed terms work, picking the right mortgage becomes simple, predictable, and stress-free.
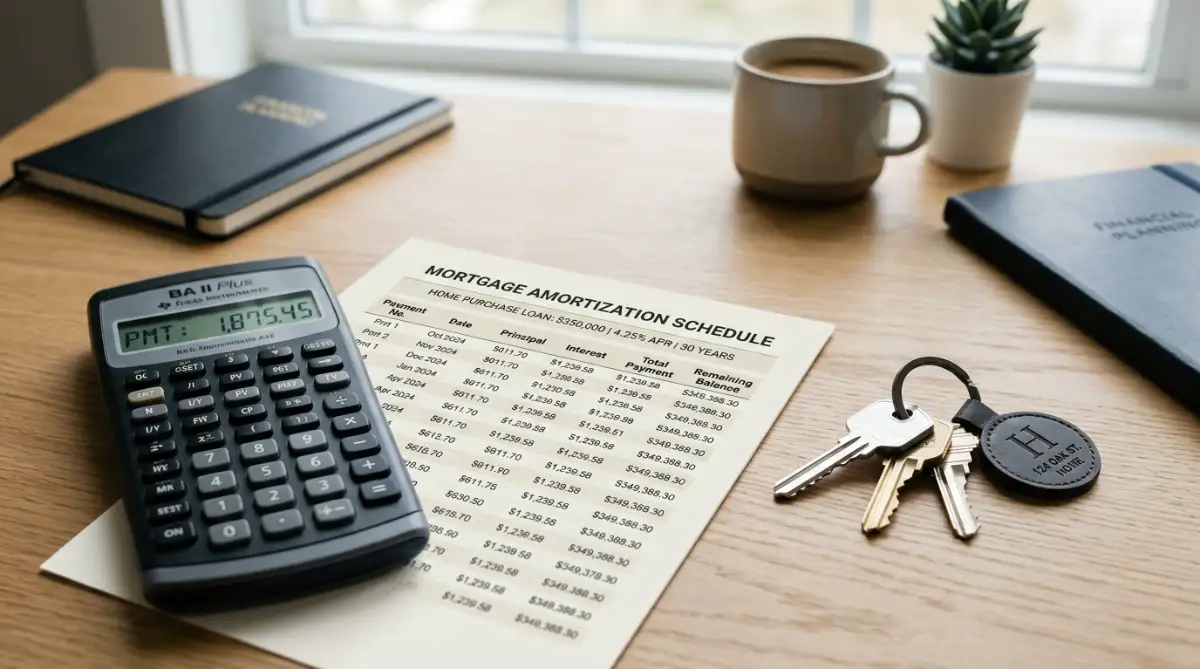 Understanding the Mechanics of Fixed and Adjustable Mortgages
Let us look at the fundamental mechanics that separate fixed-rate mortgages from adjustable-rate mortgages. Breaking down how interest rates behave over time gives you complete control over your home financing strategy.
A fixed-rate mortgage keeps your interest rate locked at the exact same percentage for the entire lifespan of the loan, while an adjustable-rate mortgage (ARM) starts with a lower teaser rate that changes periodically based on market indexes.
Core Mortgage Mechanics Breakdown
To ensure your overall financial foundation is sound before applying for a mortgage, you can review our guide on how to improve your credit score to secure the lowest possible interest rate tiers.
Comparing Fixed-Rate and Adjustable-Rate Mortgages
Myth vs Reality: Home Loan Structures
Myth: "Adjustable-rate mortgages are dangerous traps that always cause home foreclosure."
Reality: ARMs with strict rate caps can be smart, money-saving financial tools for disciplined buyers with short ownership timelines.
My Personal Pro Tip: Never assume you must put down twenty percent cash to buy a house. Millions of first-time buyers purchase their homes using low down payment programs that require only three to five percent down, freeing up cash for emergencies. To ensure your profile is fully prepared before submitting applications, you can also review our guide on how to improve your credit score.
Watch this helpful video guide to understand how fixed-rate and adjustable-rate mortgages work so you can select the ideal structure for your home financing needs:
Smart Strategies to Master Your Mortgage Structure
Once you understand the basic differences between fixed and adjustable mortgages, you can use smart financial tactics to maximize your savings. Experienced homebuyers use specific strategies to lower their total interest costs and protect their long-term wealth. One of the most powerful moves is shopping around with multiple institutions rather than trusting just one bank. Each lender must give you a standardized three-page document called a Loan Estimate, which lets you compare interest rates, closing costs, and origination fees side by side. For small business owners or freelancers organizing their income documentation before a home purchase, our tutorial on easy AI website builders for small businesses offers great tips on establishing clear digital business footprints.
Another great way to save money is switching to a bi-weekly payment schedule, meaning you pay half of your monthly mortgage payment every two weeks. Because there are fifty-two weeks in a year, you end up making twenty-six half-payments, which equals thirteen full monthly payments each year instead of twelve. That single extra payment each year goes directly toward your principal debt balance, shaving up to five full years off your mortgage without hurting your wallet. If you are balancing student loans or educational financing alongside your housing search, reviewing insights on federal vs private student loans helps you manage overall debt obligations safely. For students or young adults looking into affordable ways to continue their education without accumulating toxic debt, researching options like best community colleges in the USA provides affordable avenues for academic growth.
Protecting your personal finances after moving in is just as important as securing a low rate. Before taking on a massive monthly mortgage payment, spend a few months building a robust emergency fund to handle surprise home repairs. For related insights on safeguarding your personal assets and insurance standing against unexpected liability, check out tips on how to choose your first home insurance policy without unnecessary anxiety. Taking a disciplined, structured approach ensures your homebuying journey remains smooth and successful.
Pitfalls That Can Instantly Wreck Your Mortgage
Even smart buyers with great income can fall into sudden financial traps during the home buying journey. Avoiding these common mistakes keeps your loan application moving smoothly toward final approval.
Opening New Lines of Credit Before Final Closing
One of the worst mistakes you can make is opening new credit accounts right before your mortgage closes, as lenders perform a final credit check right before releasing loan funds.
Emptying Every Cent from Your Savings Account
Putting every dollar of your liquid savings toward a down payment leaves you completely exposed to unexpected risks and surprise costs right at the closing table.
Simple Do's and Don'ts During Your Loan Application
- Do respond to lender requests for tax papers or bank statements within twenty-four hours.
- Do keep working at your current job and keep your main income completely stable.
- Do save extra cash in your bank account for closing costs and surprise home repairs.
- Don't make sudden cash deposits into your bank accounts without clear paper receipts.
- Don't co-sign loans for friends or relatives while waiting for your mortgage approval.
- Don't miss any bill due dates or open new retail credit card lines.
Your Simple Day-One Homebuyer Action Plan
Securing your first mortgage loan does not have to feel like an impossible puzzle. When you take control of your credit score, budget wisely, and compare lender options, you put yourself in the driver's seat.
- Check Credit Early: Review your credit reports and clean up past reporting errors right away.
- Compare Multiple Lenders: Always collect official loan estimates from at least three different financial institutions.
- Maintain Stability: Keep your job and credit profile completely stable until final paperwork is signed.
Taking that first step toward getting a mortgage felt terrifying to me, but owning my home turned out to be the absolute best decision I ever made for my family's financial future. You do not need to feel scared of the complicated bank paperwork because regular people just like us successfully get approved every single day. Trust your preparation, take action today, and claim the keys to your new home!
Recommended Reading Resources
Explore these internal guides to master your overall financial strategy:
- How to Improve Your Credit Score Before Applying for a Mortgage
- Federal vs Private Student Loans Guide
- How to Choose Your First Home Insurance Policy Without Stress
- Easy AI Website Builders for Small Businesses Simple Setup Guide
- Best Community Colleges in the USA for Affordable Education
Frequently Asked Questions
What is the difference between a fixed-rate and adjustable-rate mortgage?
A fixed-rate mortgage keeps your interest rate locked for the life of the loan, while an adjustable-rate mortgage (ARM) changes periodically after an initial fixed period.
Why should I compare multiple mortgage lenders?
Comparing at least three lenders allows you to negotiate lower origination fees and secure a lower interest rate, saving thousands over time.
What are mortgage closing costs?
Closing costs cover third-party processing fees, home appraisals, title insurance, and lender charges, typically running 2% to 5% of the purchase price.
Can I open new credit cards while waiting for mortgage closing?
No, opening new credit accounts changes your debt-to-income ratio and can cause lenders to pause or deny your loan at the last minute.
What is a bi-weekly mortgage payment plan?
A bi-weekly plan involves paying half your mortgage every two weeks, resulting in 26 half-payments (or 13 full payments) a year to pay off the loan faster.
Disclaimer: The information provided in this article is for educational and informational purposes only and should not be construed as professional financial, legal, or real estate advice. Mortgage loan terms, interest rates, and approval criteria vary based on individual financial profiles, lender policies, and government regulations. Always consult with a licensed mortgage broker, financial advisor, or qualified professional before making major real estate decisions.


