How Auto Loan Interest Rates Work: A Simple Guide to Saving Money
I still vividly remember sitting across from a slick dealership finance manager, holding a pen over a ten-page auto loan contract. My hands were literally shaking because I felt too embarrassed to ask basic questions about the massive interest rate printed at the bottom. I signed the papers just to get out of there, but six months later, I discovered a terrifying financial reality.
Almost half of my monthly payment was going straight into the bank's pocket as high compounding interest. That sickening realization of losing thousands of my hard-earned dollars kept me awake at night with deep financial regret. I realized that my ignorance in that tiny glass office was the most expensive mistake I had ever made in my adult life.
That painful, frustrating experience pushed me to aggressively study how auto financing truly works behind closed doors. Now, I want to share exactly what I learned so you can protect your wallet and drive home with absolute financial peace of mind. You never have to feel overwhelmed or cheated by a car dealership ever again.
Walking into a car dealership is one of the most exciting consumer experiences you can have today. The bright showroom lights and the intoxicating smell of a brand-new interior make you feel successful and accomplished. You find the vehicle that fits your style and tell yourself that your years of hard work have finally paid off.
But the second you step out of the vehicle and are escorted into the finance manager’s office, the atmosphere changes completely. You are suddenly pressured to agree to complex loan durations, high interest percentages, and confusing legal disclaimers.
Inside that small glass office, the initial excitement of car shopping is abruptly replaced by overwhelming confusion. Lenders purposefully use complicated terminology designed to make buyers feel overwhelmed so they surrender control. You are handed a stack of thick contracts and pressured to sign on the dotted line before you understand what you are agreeing to.
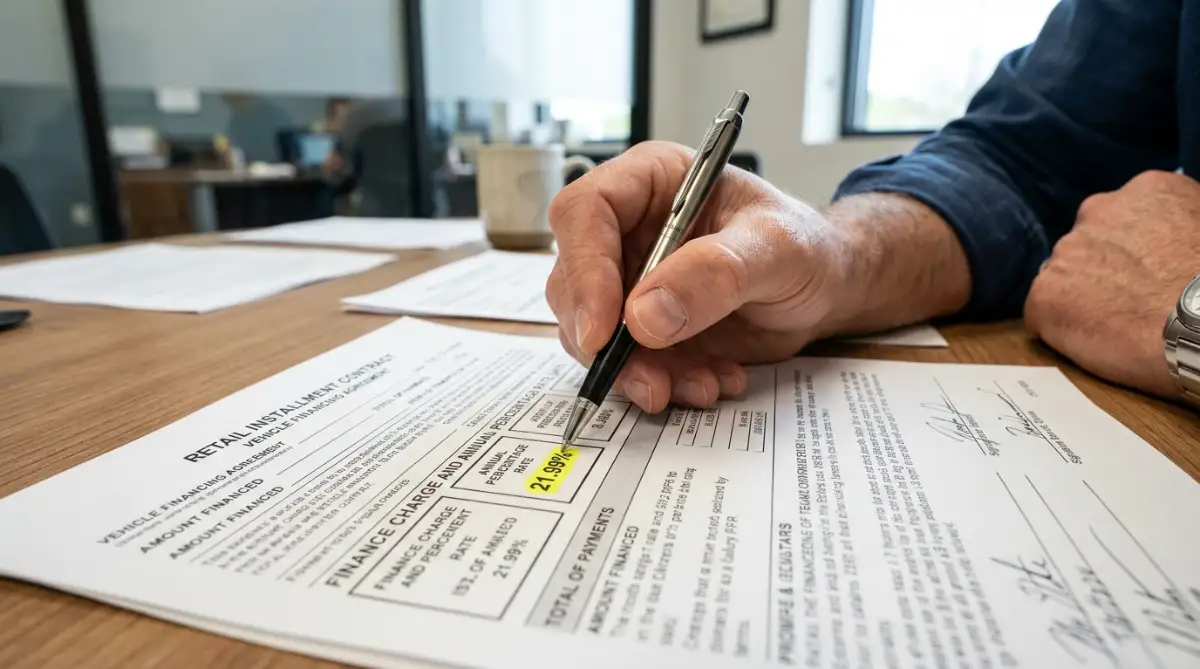
A few months later, the excitement completely vanishes when you stare at your monthly bank statement. You discover that a massive portion of your monthly check is not actually paying down the price of the car. Instead, you have fallen into the exact same trap that costs millions of buyers thousands of dollars every year.
Understanding the Mechanics of Auto Financing
To take back control of your financial decisions, you must master the core mechanisms that drive car financing. Think of an interest rate as the specific "rent" you pay to borrow the bank’s capital. If you do not shop around for the lowest rent, you end up paying a massive premium for absolutely no reason.
Many buyers mistakenly believe that the base interest rate and the Annual Percentage Rate (APR) are the exact same thing. The base interest rate is simply the raw percentage fee charged by the lender on the principal balance. The APR represents the true total cost of borrowing, including the base rate plus all hidden dealer origination charges.
How Credit Scores Dictate Your Auto Loan Cost
Debunking Common Car Financing Myths
Myth: "You must get your financing directly through the dealership's finance department to buy a car."
Reality: Dealerships function as middlemen who often markup bank rates to earn a secret commission. Independent credit unions and banks almost always offer significantly lower baseline interest rates.
My Personal Pro Tip: When I bought my second car, I completely ignored the dealer's finance office and walked in with a blank check from my local credit union. That one simple move dropped my APR by three percent and saved me over two thousand dollars. I always tell my friends that if you want to win at the dealership, you must absolutely secure your own financing before ever test-driving a car.
Watch this eye-opening breakdown by an auto industry insider to see how dealership finance offices quietly mark up interest rates to extract thousands in extra profit!
Advanced Strategies to Secure the Lowest Rates
Getting a great deal on an auto loan does not happen by luck; it happens by careful, strategic design. Execute these practical steps before visiting any dealership lot to guarantee you receive the absolute lowest interest rate possible.
Three to six months before shopping for a vehicle, order your official credit reports from the major credit bureaus. Thoroughly inspect your history for errors, incorrect late payment marks, or fraudulent accounts. Fixing these small errors can quickly boost your credit score by thirty to fifty points.
A higher score shifts you into a significantly cheaper interest tier almost instantly. If you want to prepare your financial profile perfectly, read our simple guide on how to improve your credit score before applying for a mortgage or an auto loan.
Putting down at least twenty percent in cash heavily lowers the total loan-to-value ratio. Lenders always view borrowers with substantial equity as low-risk, highly reliable clients. This directly unlocks lower interest rates and protects you from becoming underwater on your loan due to rapid vehicle depreciation.
If you need extra income to build your down payment, consider launching a digital side hustle. You can use our easy AI website builders for small businesses simple setup guide to start generating extra cash online quickly.
When a salesperson asks what monthly payment you are aiming for, firmly decline to answer. State clearly that you are only interested in negotiating the total Out-of-the-Door cash price of the vehicle. By locking down the total price first, you stop the sales team from hiding inflated interest rates inside a confusing monthly payment structure.
Lenders carefully look at your monthly debt obligations before approving a competitive interest rate. If you are currently juggling multiple loan payments, getting your existing finances organized is absolutely essential. Taking time to understand your federal vs private student loans how to choose wisely can help you restructure your debts effectively.
Building long-term wealth means minimizing unnecessary expenses whenever possible across your entire life. For young adults trying to save for a dependable car, reducing higher education costs is a massive financial advantage. Attending one of the best community colleges in the USA for affordable education keeps your overall living expenses remarkably low.
Credit unions are non-profit financial cooperatives completely owned by their local members. Because they do not have to generate massive corporate profits, they consistently offer some of the lowest auto loan interest rates in the country.
Always obtain a written pre-approval letter from a local credit union before stepping foot near a dealership. Having a blank check in your pocket turns you into a cash buyer instantly and completely removes the dealership's ability to manipulate your interest rate.
Expensive Traps That Destroy Your Finances
Even highly cautious buyers occasionally fall victim to last-minute traps inside the finance office. Keep an incredibly close eye out for these costly mistakes to protect your hard-earned wealth.
High-Margin Dealer Add-Ons
In the final stage of signing paperwork, finance managers often pitch extra products like extended warranties, tire protection packages, and paint sealants. These products are heavily marked up and completely unnecessary for most drivers.
Rolling an extra two thousand dollars of add-ons into your loan means you will pay compound interest on those accessories for five to seven years! Always decline these extras and strictly focus on the base price of the vehicle.
Overpriced Dealer GAP Insurance
GAP insurance covers the gap between your car's actual market value and your loan balance if the car is totaled. Dealerships routinely charge eight hundred to twelve hundred dollars for simple GAP coverage.
However, your existing auto insurance provider can usually add GAP coverage to your policy for just a few dollars a month. Before buying a car, you should also review how to choose your first home insurance policy without stress to learn how insurance bundling saves you massive amounts of money.
Your Roadmap to Financial Peace
Equipped with this knowledge, you are no longer a vulnerable consumer walking blindly into a dealership finance office. You possess the exact tools, strategies, and mathematics required to negotiate with complete, unwavering confidence.
- Order your official credit reports and correct any hidden errors.
- Apply to two or three credit unions and obtain a competitive pre-approval letter.
- Accumulate a twenty percent cash down payment to absorb early vehicle depreciation.
- Lock down the final Out-of-the-Door cash price before revealing your financing details.
- Reject overpriced dealer warranties, paint sealants, and marked-up GAP policies.
I know exactly how stressful it feels to carry the heavy burden of an overpriced car loan month after month. Taking the time to educate myself completely changed my financial trajectory, and I want the exact same success for you.
By mastering these auto loan rules, you can confidently protect your hard-earned money from greedy dealerships. You finally have the power to enjoy your daily drive without an ounce of financial regret!
Internal Links Integration Check
- How to Improve Your Credit Score Before Applying for a Mortgage
- Easy AI Website Builders for Small Businesses Simple Setup Guide
- Federal vs Private Student Loans Guide
- Best Community Colleges in the USA for Affordable Education
- How to Choose Your First Home Insurance Policy Without Stress
Frequently Asked Questions
Can I refinance my car loan immediately after buying it?
Yes, in most cases you can refinance your auto loan as soon as the state title registration processes. Refinancing early allows you to replace a high dealer interest rate with a competitive credit union rate right away.
How much money does a lower interest rate actually save?
On a standard five-year loan, lowering your interest rate by just two percent saves you thousands of dollars in total interest. Always fight for the lowest rate possible to keep your monthly payments easily affordable.
What is the difference between simple and precomputed interest?
Almost all standard auto loans use simple daily interest, where interest is charged only on your remaining unpaid principal balance. Precomputed interest calculates all interest upfront, meaning you save zero money even if you pay the loan off early.
Why do dealerships push 72 or 84-month car loans?
Dealerships push long loan terms because it artificially lowers the monthly payment, making an expensive car look affordable. However, a seven-year loan guarantees you will pay massive amounts of unnecessary bank interest.
Does applying for multiple auto loans ruin my credit score?
No, modern credit scoring systems treat all auto loan inquiries made within a short 14-to-45-day window as a single credit check. This allows you to rate-shop freely with multiple banks without damaging your score.
Disclaimer
This article is published exclusively for educational, informational, and personal empowerment purposes. It does not constitute professional financial, legal, or investment advice. Auto lending policies, interest rates, and regulatory frameworks vary by region and individual financial profile. Always consult with a certified financial planner, licensed accountant, or qualified financial advisor prior to executing major loan contracts or automotive purchase agreements.


