The Hidden Metric That Controls Your Borrowing Power
A few years ago, when I decided to apply for my first major residential home loan, I felt completely invincible. I had spent six years meticulously building my credit profile, keeping my credit card utilization below 5%, and maintaining a credit score well over 780. I assumed walking into the bank would be a mere formality. Imagine my utter shock when the underwriting department placed my application on conditional hold. The culprit was my Debt-to-Income ratio sitting at a staggering 47%. Despite my high credit score, my modest gross income was overburdened by a heavy monthly automobile payment, a high minimum credit card balance, and student loan bills. I was forced to step back, delay my home purchase by four months, and strategically pay down specific recurring obligations to bring my DTI under 35%. That humbling experience taught me a lesson every borrower must learn: a stellar credit score gets you through the front door, but a healthy Debt-to-Income ratio actually closes the deal.
When prospective borrowers in the United States begin preparing for major financial milestones—such as purchasing a first home, refinancing an existing mortgage, acquiring a fuel-efficient automobile, or securing a personal line of credit—they almost universally focus on a single financial metric: their credit score. It is easy to understand why. For decades, personal finance literature, television commercials, and credit monitoring mobile applications have conditioned consumers to believe that a credit score above 750 is an absolute golden ticket to unconditional financial approval. However, when your application lands on the desk of an experienced mortgage underwriter or bank loan officer, they look far beyond your credit score. They evaluate a much more crucial indicator of your ongoing cash flow stability: your Debt-to-Income (DTI) ratio.
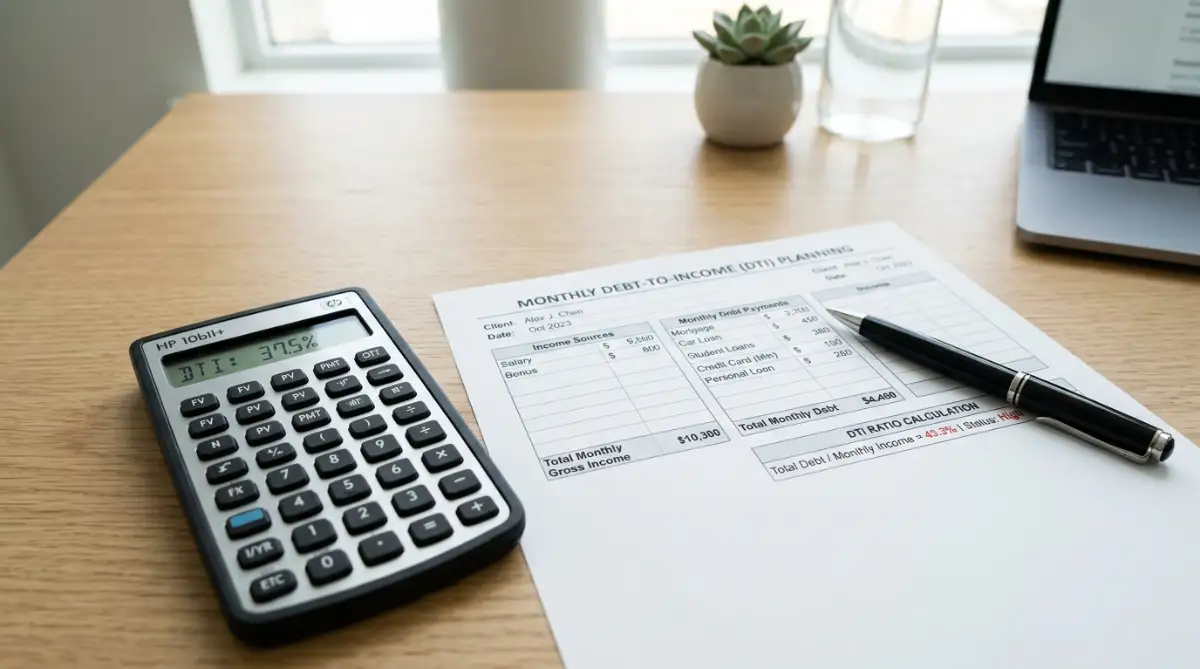
Understanding how your Debt-to-Income ratio impacts your loan approval is essential because DTI serves as the ultimate yardstick of your monthly financial capacity. While your credit score demonstrates your historical willingness to pay back borrowed money on time, your DTI ratio proves your physical ability to afford new monthly debt obligations alongside your existing financial commitments. In fact, mortgage industry statistics reveal that an excessively high Debt-to-Income ratio is responsible for nearly half of all loan application rejections in America—surpassing bad credit scores as the leading cause of mortgage denials. In this ultimate masterclass guide, we will unpack every single aspect of DTI, explore how underwriters calculate it, dissect front-end versus back-end thresholds, and reveal actionable strategies to optimize your DTI ratio before submitting a credit application.
What Is a Debt-to-Income (DTI) Ratio and Why Do Lenders Care?
At its core, a Debt-to-Income (DTI) ratio is a mathematical percentage that compares your total mandatory recurring monthly debt payments against your gross monthly income before taxes and deductions are withheld. Expressed simply, DTI measures how much of your incoming paycheck is already claimed by pre-existing debt obligations before you spend a single dollar on discretionary living expenses.
Financial institutions and mortgage lenders care deeply about your DTI ratio because it serves as an empirical risk assessment tool. Lenders are inherently risk-averse institutions seeking firm mathematical assurance that you have sufficient unencumbered monthly cash flow to absorb a new loan payment without defaulting under financial strain.
Core DTI Benchmarks Breakdown
It is important to note that when evaluating creditworthiness, underwriters analyze both your credit history and your income structure. While learning why your credit score matters for unsecured loans is essential for setting your interest rate tier, your DTI ratio dictates the absolute maximum dollar amount a bank is willing to lend you.
Comparing Front-End and Back-End DTI Standards
Myth vs Reality: Debt-to-Income Ratios
Myth: "If my credit score is 800, my Debt-to-Income ratio does not matter to lenders."
Reality: Federal lending rules legally prohibit banks from exceeding strict DTI ceilings, regardless of how high your credit score is.
My Personal Pro Tip: When I committed to lowering my DTI ratio, I realized I had been making a classic financial mistake: I was throwing extra cash at my largest long-term balances while ignoring small recurring monthly obligations. I sat down with a spreadsheet and highlighted every single line item that generates a mandatory monthly bill. Wiping out two small retail credit card balances and a minor personal loan instantly shaved nearly 4 percentage points off my DTI ratio without needing a massive salary raise.
Watch this comprehensive video explainer to see how mortgage underwriters and bank loan software evaluate your Debt-to-Income numbers in real-world scenarios:
7 Proven Strategies to Lower Your Debt-to-Income Ratio Fast
If your initial DTI calculations reveal that you are hovering near or above the danger zone for loan approval, do not panic. Unlike credit scores, which can take six to twelve months of patient credit rebuilding to move significantly, your Debt-to-Income ratio can be improved rapidly with targeted, strategic financial moves. One of the most effective tactics is targeting payment elimination over simple balance reduction. When trying to improve your credit score, paying down large credit card balances is effective, but when trying to lower your DTI, eliminating whole monthly payments entirely delivers the biggest impact. Focus on paying off smaller loans or credit cards that carry high minimum monthly payments relative to their total remaining balance. To ensure your credit standing remains strong during this restructuring phase, you can review our guide on how to improve your credit score to prepare your file effectively.
Another powerful strategy involves consolidating high-interest monthly debts. If you are juggling multiple credit cards, store accounts, and high-rate personal loans, combining them into a single streamlined financing structure can drastically reduce your aggregate monthly output. Analyzing debt consolidation and personal loan options shows that rolling four high-interest credit card payments into a single structured loan with a lower fixed interest rate instantly frees up cash flow and cuts your DTI percentage significantly. If you are balancing student loans or educational financing alongside your debt restructuring strategy, reviewing insights on federal vs private student loans helps you manage overall debt obligations safely. For small business owners or freelancers managing commercial credit profiles, you can explore resources on easy AI website builders for small businesses to establish professional online branding and extra revenue channels.
Furthermore, maintaining household protection against unexpected liability keeps your overall financial house in order. For related insights on safeguarding your personal assets and insurance standing, check out tips on how to choose your first home insurance policy without unnecessary anxiety. For students or young adults looking into affordable ways to continue their education without accumulating toxic debt, researching options like best community colleges in the USA provides affordable avenues for academic growth. Keeping your financial records organized and your DTI ratio low protects your borrowing power for major life decisions.
 Misconceptions and Pitfalls Regarding DTI Calculations
Because financial terminology can often be confusing, several persistent myths surround DTI calculations. Recognizing these hidden hazards helps you avoid sudden loan application rejections.
Assuming Living Expenses Count Toward DTI
Routine everyday living expenses—such as groceries, electricity, water, internet, cell phone service, or streaming memberships—are never included in your official DTI calculation, which focuses strictly on debts and housing.
Relying on Net Take-Home Pay Instead of Gross Income
Underwriters calculate DTI using your gross monthly income before taxes, not your net take-home pay. Failing to account for pre-tax calculations can give borrowers a false sense of security regarding their true borrowing capacity.
Simple Do's and Don'ts for DTI Management
- Do eliminate small recurring monthly bills entirely to drop your DTI numerator fast.
- Do document additional steady income streams like overtime or second jobs with W-2s.
- Do keep your back-end debt ratio below 36% to 43% for smooth mortgage processing.
- Don't take on new monthly credit obligations or finance vehicles before applying for a home.
- Don't assume a high credit score exempts you from strict bank DTI ceilings.
- Don't forget to factor property taxes and homeowners insurance into your housing calculations.
Your Action Plan for Long-Term Financial Dignity
Mastering your Debt-to-Income ratio is one of the most empowering, highly effective financial skills you can develop as a modern consumer. While credit scores reflect your past reliability, your DTI ratio represents your present financial breathing room.
- Calculate Your Baseline DTI: Add up all mandatory monthly debt payments and divide by your gross monthly income.
- Eliminate Small Obligations: Wipe out minor recurring bills to shrink your monthly debt numerator.
- Maintain Cash Reserves: Keep a healthy post-closing savings buffer to satisfy lender risk requirements.
Looking back on my journey, learning to respect and manage my Debt-to-Income ratio did far more than just help me secure a mortgage approval. It fundamentally transformed my entire relationship with money and debt leverage. When you keep your fixed recurring monthly debts low, unexpected car repairs or economic shifts no longer cause overwhelming panic. Maintaining a low DTI is not merely about pleasing bank underwriters—it is about gifting yourself and your family long-term financial dignity, flexibility, and absolute peace of mind.
Recommended Reading Resources
Explore these internal guides to master your overall financial strategy:
- How to Improve Your Credit Score Before Applying for a Mortgage
- Federal vs Private Student Loans Guide
- How to Choose Your First Home Insurance Policy Without Stress
- Easy AI Website Builders for Small Businesses Simple Setup Guide
- Best Community Colleges in the USA for Affordable Education
Frequently Asked Questions
Can I get approved for a mortgage with a DTI over 45%?
Yes, government-backed programs like FHA loans routinely approve back-end DTI ratios up to 50% or higher with strong compensating factors.
How do student loans in deferment affect my DTI ratio?
Underwriters must calculate a monthly payment for deferred student loans—often 0.5% to 1% of the balance—to include in your back-end DTI ratio.
Does closing a credit card account lower my DTI ratio?
No, closing a credit card does not change your required minimum monthly payment if a balance remains, and it can actually harm your credit score.
Is DTI calculated using gross or net income?
Lenders calculate your Debt-to-Income ratio using your gross monthly income before taxes and payroll deductions are withheld.
How quickly can I lower my DTI ratio?
You can lower your DTI ratio immediately by paying off recurring monthly debt obligations and providing official payoff verification letters.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute professional financial, legal, or mortgage advice. Loan approval guidelines, Debt-to-Income requirements, and interest rates vary based on individual financial circumstances and lender policies. Always consult with a licensed mortgage broker, certified financial planner, or legal advisor before making major borrowing decisions.


