The Hidden Cash Emergency: Why Small Businesses Struggle for Capital
A couple of years ago, I found myself in a terrifying spot when my main supplier demanded immediate payment before releasing a massive inventory shipment. I spent three sleepless nights panicking, frantically searching online, and making endless phone calls to banks that kept asking for endless paperwork. That painful experience taught me firsthand how overwhelming a sudden cash crunch can be when you do not have a clear action plan. I remember sitting at my desk staring at dwindling reserves, wondering how I would make payroll and keep operations afloat. That trial-by-fire forced me to figure out how modern commercial financing works without relying on slow traditional banks. Once I learned how to organize my digital financial records, securing working capital became entirely manageable.
Running a business comes with sudden financial demands that can catch you off guard. You might face an unexpected bill, an emergency payroll gap, or a massive equipment repair. When you need money right away, every passing hour creates intense anxiety and pressure.
Many owners spend days endlessly searching for financing options online without getting clear answers. The constant uncertainty can make you feel completely helpless in your own company.
Why do business owners fail to find quick financing? Relying entirely on old traditional banks causes massive delays because traditional banks move slowly and require mountains of paperwork that take weeks to process. Applying with bad cash flow records makes lenders get spooked when bank statements show low average balances or frequent overdrafts. Falling for predatory loan schemes happens when urgent stress leads many owners to sign agreements with hidden fees and daily interest traps. Applying to too many lenders at once blasts applications everywhere, lowers credit scores, and signals financial desperation.
How funding delays damage your peace of mind is also clear. Loss of sleep over pending bills means worrying about making payroll or paying suppliers ruins your health and focus. Strained vendor relationships cause delayed payments that reduce trust with suppliers who keep your inventory moving. Missed growth opportunities happen because without quick capital, you lose lucrative orders and expansion deals to competitors.
I have seen countless hard-working entrepreneurs face this exact wall. You built a great service, yet a short-term cash shortage threatens to pull everything down. When you do not know where to turn, panic sets in.
You start guessing what paperwork lenders want or hoping for a miracle from your local bank branch. Understanding how modern financing works changes the game completely. You can take control of your financial destiny today by applying a smart, step-by-step approach.
The Fast-Track Strategy: Prepare Your Business for Immediate Approval
Getting money fast is not about luck or secret shortcuts. It comes down to presenting your financial profile in a way that modern underwriting algorithms love.
Let us look at Marcus, who owns a bustling neighborhood bakery. When his main commercial oven broke on a busy morning, he needed $20,000 within forty-eight hours to replace it. Instead of walking into a traditional bank branch, Marcus organized his bank statements digitally and matched his needs with an online lender. He received funding approval by the next afternoon because he had everything ready.
Core Fast-Track Requirements
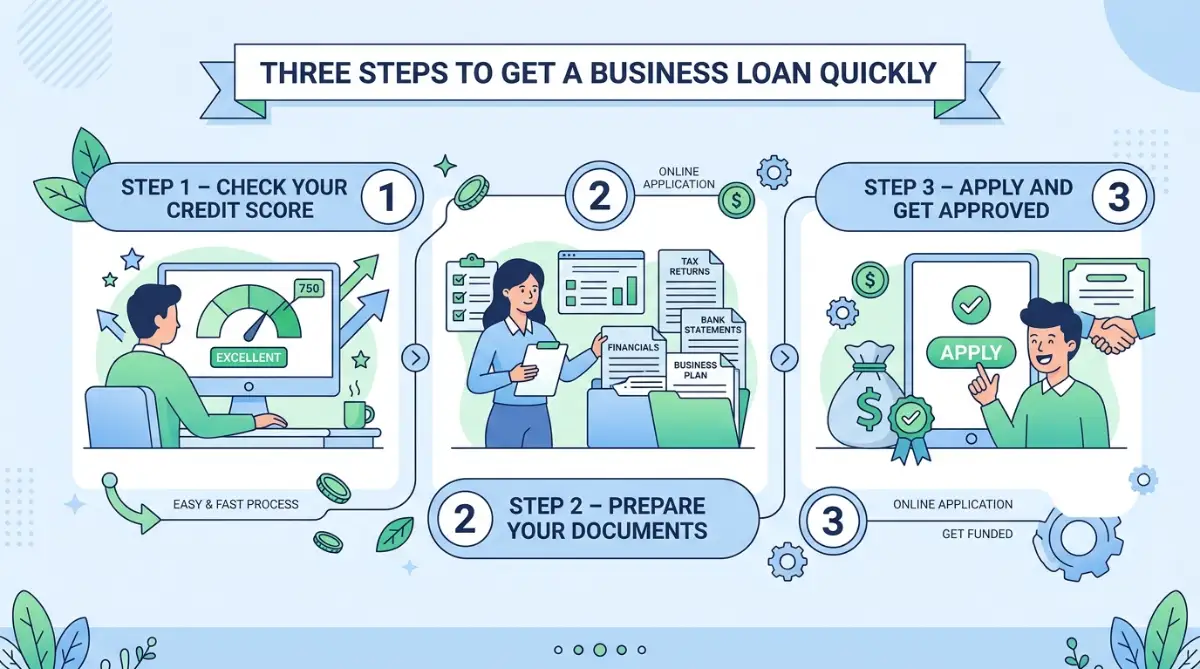
- Step 1: Organize your digital financial paperwork into a clear PDF folder.
- Step 2: Choose the right fast loan option matching your immediate cash need.
- Step 3: Optimize your bank account profile by avoiding low average balances.
Comparing Fast Business Funding Options
Myth vs Reality: Quick Business Financing
Myth: "Online lenders are always untrustworthy or predatory."
Reality: Many reputable online financial institutions offer competitive rates and operate under strict regulations to support small business owners safely.
My Personal Pro Tip: Here is a personal mistake I made early on: I used to let my business account balance drop down to a few dollars near the end of the month. When I first applied for capital, an underwriter pointed out that low average daily balances make a business look high-risk. Once I started keeping a modest cash buffer in my account throughout the entire month, my approval speed and funding offers improved immediately.
Watch this short breakdown to see how fast small business loans work and how you can get funded in as little as 24 hours:
Advanced Insider Strategies to Maximize Your Business Funding Velocity
Once you master the basic preparation steps, you can use high-level strategies that give you an edge over other applicants. Getting approved quickly is not just about filling out a form; it is about proving that your enterprise is low-risk and highly profitable. I have worked with dozens of business owners who turned their cash flow around by making small adjustments to their daily banking habits. These advanced tactics will help you secure higher loan amounts and lower interest rates. One effective strategy is building direct relationships with digital underwriters. Many modern financial platforms have dedicated account managers assigned to evaluate commercial applications. Opening a direct line of communication with an underwriter can speed up your loan approval dramatically. When you submit an application online, send a polite follow-up message to customer support immediately. To ensure your business foundation is fully protected while scaling up operations, you can review our guide on how to choose your first home insurance policy to safeguard your personal and commercial assets.
Another powerful move is leveraging existing accounts receivable for rapid cash injections. If you run a business that bills clients on thirty-day terms, outstanding unpaid invoices are sitting assets waiting to be used. You can convert those unpaid bills into immediate capital without waiting for customer checks to clear by using invoice acceleration platforms. This approach prevents you from taking on traditional long-term balance sheet debt while providing a flexible way to handle sudden payroll spikes. If you are managing educational expenses or looking for affordable ways to train your staff, exploring resources on best community colleges in the USA offers cost-effective professional development programs. Furthermore, maintaining an emergency cash buffer secures long-term stability. You should aim to hold at least three months of core operating expenses in a separate business savings account so you can negotiate from a position of strength when dealing with lenders. You can read more about building a bulletproof emergency fund to protect your business against unforeseen market dips.
Additionally, keeping your digital footprint clean and professional is essential for modern fintech underwriting. If you need to establish a strong digital presence or showcase your commercial services online, reviewing our tutorial on easy AI website builders for small businesses helps you set up professional web pages quickly. For entrepreneurs also managing personal credit scores or prior consumer obligations, understanding tips on how to improve your credit score ensures your background profile stays clean. By taking a methodical approach, your company gains access to prime rates whenever new expansion opportunities arise.
 Operational Mistakes That Can Destroy Your Funding Chance
Even well-established companies make silly mistakes when rushing to secure quick capital. Being aware of these traps helps you avoid costly delays and rejections.
Mixing Personal and Business Bank Accounts
Using a personal checking account to run commercial transactions is a major reason lenders reject applications because underwriters cannot evaluate true business revenue.
Accumulating Multiple High-Cost Micro-Loans
Taking on several daily-draw merchant cash advances can drain your bank account overnight, a practice known as loan stacking that signals extreme financial distress.
Simple Do's and Don'ts for Commercial Funding
- Do maintain a clean digital folder of tax returns and clear business bank statements.
- Do monitor your business credit profile on trusted reporting platforms regularly.
- Do choose lenders that report your positive repayment history to commercial credit bureaus.
- Don't stack multiple daily-draw micro-loans on top of each other.
- Don't hide existing debts or late payments from your underwriting officer.
- Don't draw funds without a clear operational plan to generate revenue from them.
Action Plan for Tomorrow: Take Charge of Your Business Cash Flow
Getting a fast business loan is entirely doable when you follow a structured system. You do not need to feel stressed or overwhelmed by sudden cash shortages ever again.
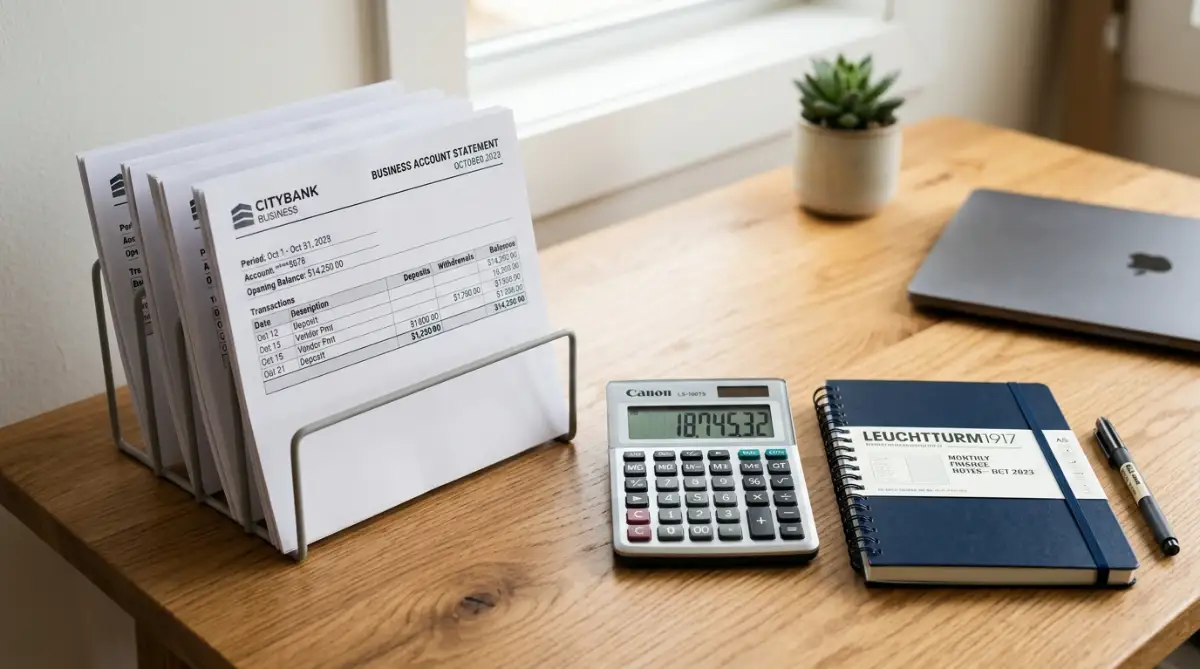
- Clean Up Digital Records: Merge your last six months of business bank statements into neat PDF files.
- Review Account Balances: Eliminate unnecessary personal draws to keep your daily account balance healthy.
- Select the Right Match: Choose an online line of credit or invoice loan based on your specific operational needs.
Taking control of your cash flow is one of the most empowering steps you can take for your business growth. I know how stressful it feels when funds are tight, but taking just ten minutes to organize your bank statements today changes everything. Trust your ability to succeed, take action right now, and give your business the financial peace of mind it deserves.
Recommended Reading Resources
Explore these internal guides to master your overall business and financial strategy:
- How to Choose Your First Home Insurance Policy Without Stress
- Best Community Colleges in the USA for Affordable Education
- Easy AI Website Builders for Small Businesses Simple Setup Guide
- How to Improve Your Credit Score Before Applying for a Mortgage
Frequently Asked Questions
Will applying for a fast business loan hurt my credit score?
Initial soft credit checks performed by online lenders do not hurt your credit score at all, as only formal hard inquiries affect scores slightly.
How fast can cash land in my business checking account?
Many online fintech lenders transfer funds within twenty-four hours of final document approval, sometimes arriving by the same afternoon.
Can I get a fast business loan with poor credit?
Yes, many online lenders focus on your monthly gross revenue and bank cash flow rather than personal credit scores.
Why do lenders require business bank statements?
Bank statements allow automated underwriting software to verify your daily revenue, cash flow trends, and overall business stability.
What is invoice financing?
Invoice financing is a funding option where lenders advance cash against your unpaid business invoices to bridge short-term cash gaps.
Disclaimer: This article is strictly for educational and informational purposes and does not constitute formal financial, legal, or investment advice. Business loan terms, interest rates, and approval speeds vary based on individual credit profiles, business revenue, and lender policies. Always consult with a licensed financial advisor or certified accountant before entering into any commercial credit agreement.


