How a Two-Week DTI Adjustment Saved David's $12,000 Home Project
I recall working with David, an accountant who applied for a $12,000 personal loan to finance necessary home repairs. Despite having a steady salary, his initial application was denied because his Debt-to-Income ratio was slightly above the bank's 40% threshold.
I sat down with him to review his finances, and I saw that paying off two small card balances would fix the problem immediately. David took my advice and paid off two small credit card balances totaling $600, which instantly dropped his monthly debt obligations by $115.
When I helped him re-apply through a soft-pull pre-qualification process, his reduced DTI ratio triggered an immediate approval at a competitive 9.5% APR. My heart felt light seeing how a small two-week financial adjustment saved his project and gave him complete peace of mind.
Applying for a personal loan can feel like a stressful experience, especially when you are counting on those funds for major goals. Whether you need capital to consolidate debts, pay medical bills, or fix a vehicle, having an application denied disrupts your plans.
Many borrowers assume that loan approval is entirely a matter of luck or that lenders make decisions randomly. In reality, financial institutions rely on strict underwriting algorithms to evaluate your application based on quantifiable risk factors.
Understanding what underwriting systems look for allows you to optimize your financial profile before submitting a formal request. By taking proactive steps, you can dramatically increase your approval odds and secure competitive interest rates.
Optimizing your financial profile before applying for credit saves you time, stress, and money. When you understand how lenders calculate risk, you can address weaknesses in your application before any banker sees it.
Taking simple actions—such as lowering your Debt-to-Income (DTI) ratio, correcting credit bureau errors, and gathering income documents—transforms your profile. You present lenders with a clean, low-risk application that triggers fast approvals.
In this comprehensive guide, we unpack the primary metrics lenders use to evaluate borrowers, share actionable steps to optimize your profile, and outline a proven framework for success.
Let's examine how you can take total control of your loan application process starting today.
Optimize Your Debt-to-Income (DTI) Ratio First
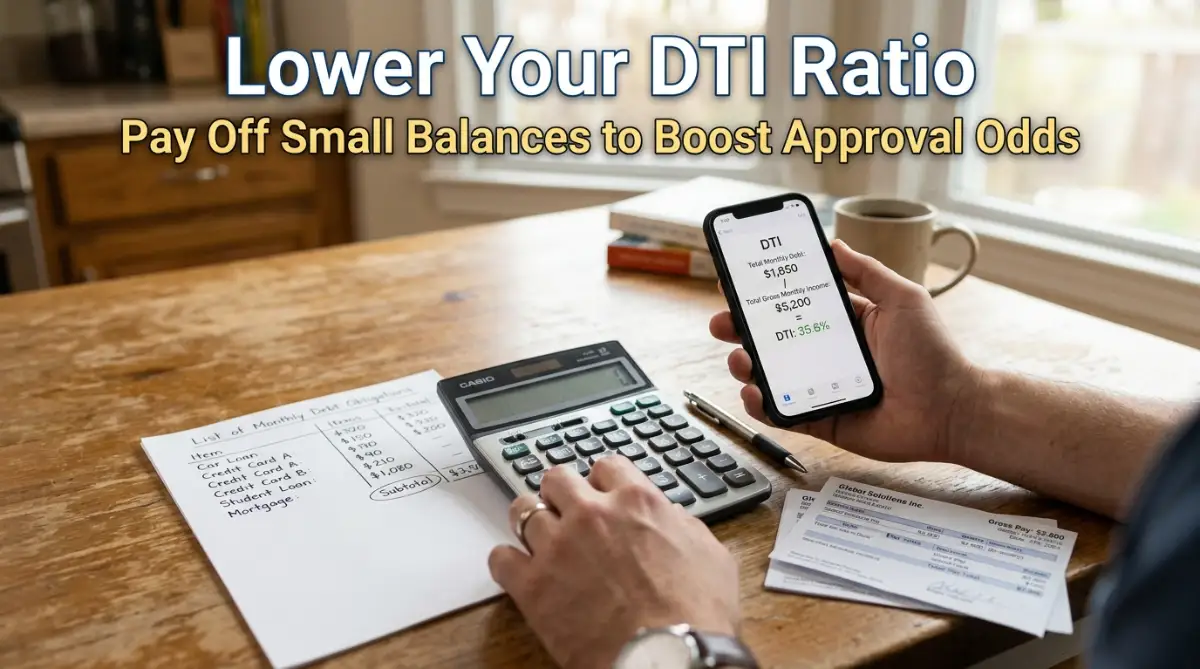
Your Debt-to-Income (DTI) ratio is one of the most significant metrics lenders use to evaluate your financial health. This calculation compares your total monthly debt payments against your gross monthly income.
Lenders want to see that you have plenty of breathing room in your budget to handle a new loan payment safely. If your monthly debt payments consume more than forty percent of your income, automated underwriting systems will flag your file as high-risk.
To improve your DTI ratio quickly, focus on paying off small credit card balances right before submitting your application. This simple step eliminates minimum monthly obligations, quickly raising your approval odds and helping you qualify for lower borrowing rates.
Leverage the Fast-Track Soft-Pull Prequalification Method
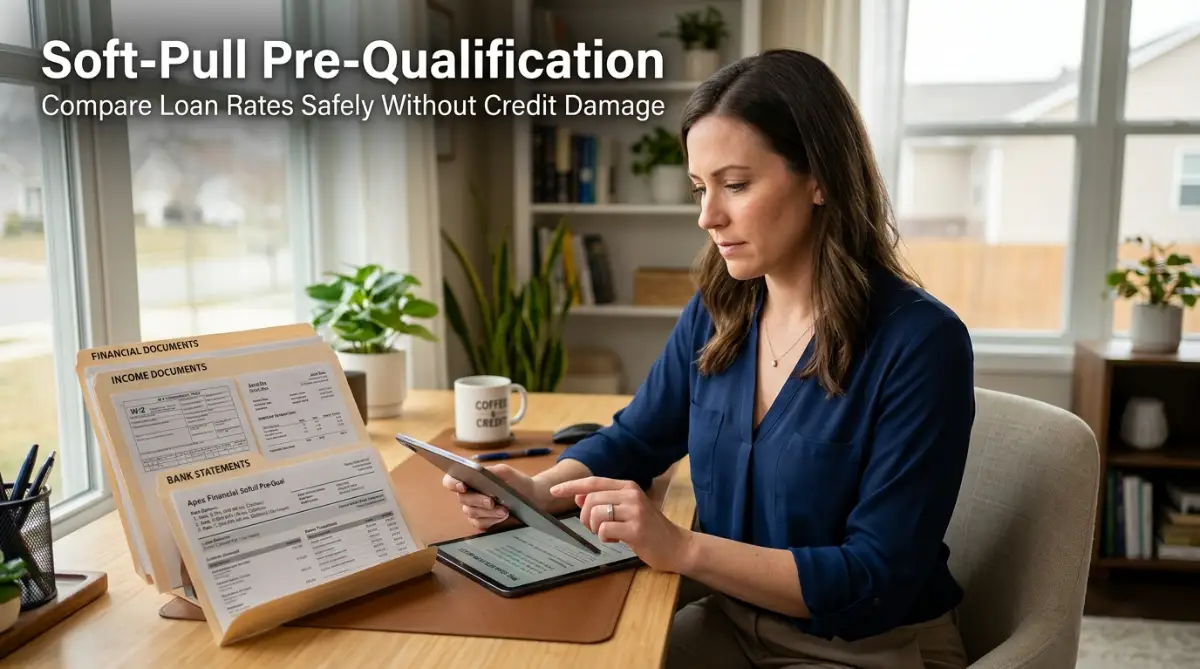
One of the most effective strategies for maximizing loan approval chances without risking credit score damage is using soft-inquiry pre-qualification tools. Many modern online lenders allow you to submit preliminary financial details to view customized rate offers without triggering a hard credit pull.
By pre-qualifying across multiple platforms, you can gauge where your application stands before granting permission for a hard inquiry. Comparing pre-qualification offers lets you evaluate Annual Percentage Rates (APRs) and fee terms side-by-side safely.
Once you identify the best pre-qualification offer, you can submit a formal application with high confidence that you will be approved.
Key Underwriting Metrics That Determine Loan Approval
Practical Strategies to Lower Your DTI Ratio Quickly
If your DTI ratio is hovering near or above 40%, taking steps to lower it before applying for a loan will significantly boost your approval chances:
- Pay Off Small Revolving Balances: Focus on paying off credit card accounts with small balances that carry high minimum monthly payments to eliminate the entire obligation.
- Include All Verifiable Income Sources: Include all legitimate income sources on your application, such as freelance earnings, side hustle revenue, or annual bonuses.
- Apply for a Debt Consolidation Loan: Some lenders factor in that your existing credit card payments will be paid off directly upon loan disbursement, which lowers your calculated DTI ratio.
Debunking Common Loan Approval Myths
- Myth 1: You must have a perfect 800 credit score to get approved for an unsecured personal loan.
- Reality: Most mainstream online lenders approve applicants with credit scores in the Good range (670+), provided their income is stable and DTI is low.
- Myth 2: Applying to ten different banks at once increases your chances of getting approved.
- Reality: Submitting multiple formal applications creates multiple hard inquiries, which lowers your credit score and signals financial desperation to underwriters.
- Myth 3: Income amount is the only thing lenders care about when reviewing loan applications.
- Reality: Lenders care more about your Debt-to-Income ratio than your total income, as existing debt obligations reduce your ability to repay new loans.
My Personal Pro Tip: Before you click apply on any official loan application, focus on paying off your smallest credit card balances first! When I was prepping my own application, dropping a couple of small card balances instantly lowered my monthly debt obligations and boosted my credit score. This quick adjustment helped me qualify for a much lower interest rate within a single week!
If you want a detailed video breakdown explaining how your debt-to-income ratio works, watch this video below:
Advanced Strategies to Optimize Your Financial File for Instant Verification
Even if your credit score and DTI ratio meet lender benchmarks, missing or inconsistent documentation can cause application delays or rejections. Having your documentation organized before applying streamlines the underwriting verification process.
Digital lenders use automated document readers to verify income and identity. Having clean PDF copies of your recent pay stubs, W-2 forms, bank statements, and government ID ready ensures your application moves through automated queues without manual holds.
Self-employed applicants should gather two years of signed federal tax returns, 1099 statements, and recent business bank statements. Demonstrating consistent net monthly deposits reassures underwriters that your cash flow is steady.
If you are working on improving your broader financial profile for major long-term goals, staying organized is essential. Learning how to improve your credit score before applying for a mortgage provides a valuable step-by-step framework for credit optimization.
Similarly, taking steps to safeguard your physical household assets provides ongoing financial stability. Learning how to choose your first home insurance policy without stress protects your property against unexpected storm or fire damage.
If you are managing student debt alongside personal loans, organizing your commitments is necessary. Reviewing federal vs private student loans: how to choose wisely helps you make informed choices about higher education debt.
Students attending the best community colleges in the USA for affordable education often avoid heavy loan burdens by keeping tuition costs low from day one.
Finally, if you run a small business or side hustle to increase your income, keeping overhead low protects your monthly cash flow. Utilizing easy AI website builders for small businesses allows you to build a professional website quickly without spending thousands on developers.
 Major Pitfalls That Lead to Sudden Loan Rejections
While preparing your application improves your odds, falling into common traps can lead to sudden denials. Knowing what triggers automated rejections protects your financial file.
The most common mistake is applying for a new loan immediately after receiving a rejection from another lender. Applying frantically creates a cluster of hard inquiries, which lowers your credit score further and signals financial distress.
Instead, review the lender's "Adverse Action Notice" to identify the exact reason for denial. Take thirty days to correct the issue—such as paying down small card balances to lower your DTI—before re-applying through soft-pull pre-qualification.
Another major mistake is guessing your income or debt figures on the application. Discrepancies between your self-reported income and your uploaded pay stubs will trigger manual fraud holds and application rejections.
Achieving Financial Control Through Proactive Preparation
Improving your chances of personal loan approval requires a proactive, strategic approach to managing your financial profile. By optimizing your Debt-to-Income ratio, paying down credit card balances, and gathering income documents, you present lenders with a low-risk application.
Taking time to prepare your finances in advance ensures you secure swift loan approval while locking in the most competitive interest rates available. Preparing your profile is the single most effective way to protect your long-term independence.
I know how stressful it feels when an unexpected loan rejection threatens your plans. Taking control of your financial profile through simple, deliberate steps gives you immediate confidence, and I am always here to guide you toward safe, affordable borrowing success!
Frequently Asked Questions About Personal Loan Approval
What is the minimum credit score needed for personal loan approval?
While some bad-credit lenders consider scores as low as 580, most mainstream personal loan lenders require a minimum credit score of 610 to 660. Scores above 720 qualify for the lowest interest rates and highest borrowing limits.
Can I get approved for a personal loan if I am self-employed?
Yes. Self-employed applicants can secure approvals by providing two years of signed tax returns, 1099 forms, and 3 to 6 months of bank statements demonstrating steady net monthly income.
How does adding a co-signer improve loan approval chances?
Adding a creditworthy co-signer with a strong credit score and steady income reduces lender risk. Underwriters evaluate both applicants' financial profiles, helping you qualify for a lower interest rate if your own credit score or DTI ratio is marginal.
How long should I wait after a loan rejection before applying again?
It is best to wait 30 to 60 days before submitting a new application. Use this time to address the specific reasons for rejection listed in your Adverse Action Notice and allow recent hard inquiries to age.
Does a soft-pull pre-qualification guarantee final loan approval?
Pre-qualification estimates are based on soft credit checks and unverified income. Final approval occurs after you submit a formal application, grant permission for a hard credit check, and verify your income documents.
Category Disclaimer
The information provided in this article is for educational and informational purposes only and does not constitute formal financial, credit, legal, or lending advice. Personal loan interest rates (APRs), underwriting criteria, origination fees, and approval odds vary based on individual creditworthiness, income verification, lender policies, and regional regulations. Always consult with a certified financial planner or credit counselor before entering into binding loan agreements.