The Credit Card Reward Dilemma: Why Consumers Struggle to Decide
A few years ago, I spent over two years hoarding thousands of travel points, dreaming of a free luxury vacation with my family. When I finally tried to book the flights, I was shocked to find strict blackout dates, unexpected booking fees, and point devaluations that erased half the value. That frustrating experience taught me that holding onto points for too long can cost you real money compared to simple, instant cash back. I remember sitting at my laptop late at night, watching award availability vanish right before my eyes while customer service offered no help. That painful lesson forced me to study the math behind reward structures so I could stop guessing and start earning real value. Once I learned how to calculate true redemption ratios, my credit card rewards strategy became completely stress-free.
Every time you open a credit card app or apply for a new card, you face a major decision: should you choose guaranteed cash back or accumulate reward points and travel miles?
Marketing campaigns make travel points look like free luxury vacations, while cash-back cards promise simple dollars returned to your bank account. Trying to calculate whether a point is worth one cent, two cents, or half a cent leaves most spenders feeling completely confused.
Why spenders struggle to choose between points and cash back:
- Confusing point valuation systems: Credit card companies use complex point structures that vary depending on how and where you redeem them.
- Falling for blackout dates and restrictions: Reward point programs often hide transfer limitations, seat availability rules, and point expiration dates in fine print.
- Overestimating travel frequency: Consumers often hoard travel points for years without redeeming them, allowing inflation and airline program changes to erode their value.
- Ignoring annual fee costs: Premium travel point cards often carry heavy annual fees that wipe out gains unless you spend tens of thousands of dollars yearly.
How reward confusion drains your peace of mind:
- Frustration over point devaluation: Watching an airline or bank reduce point values overnight makes you feel cheated out of your hard-earned rewards.
- Anxiety over complicated redemptions: Spending hours searching travel portals just to use earned miles turns a fun benefit into a frustrating chore.
- Regret over missed cash savings: Realizing you paid steep annual fees for points you never used creates immediate financial regret.
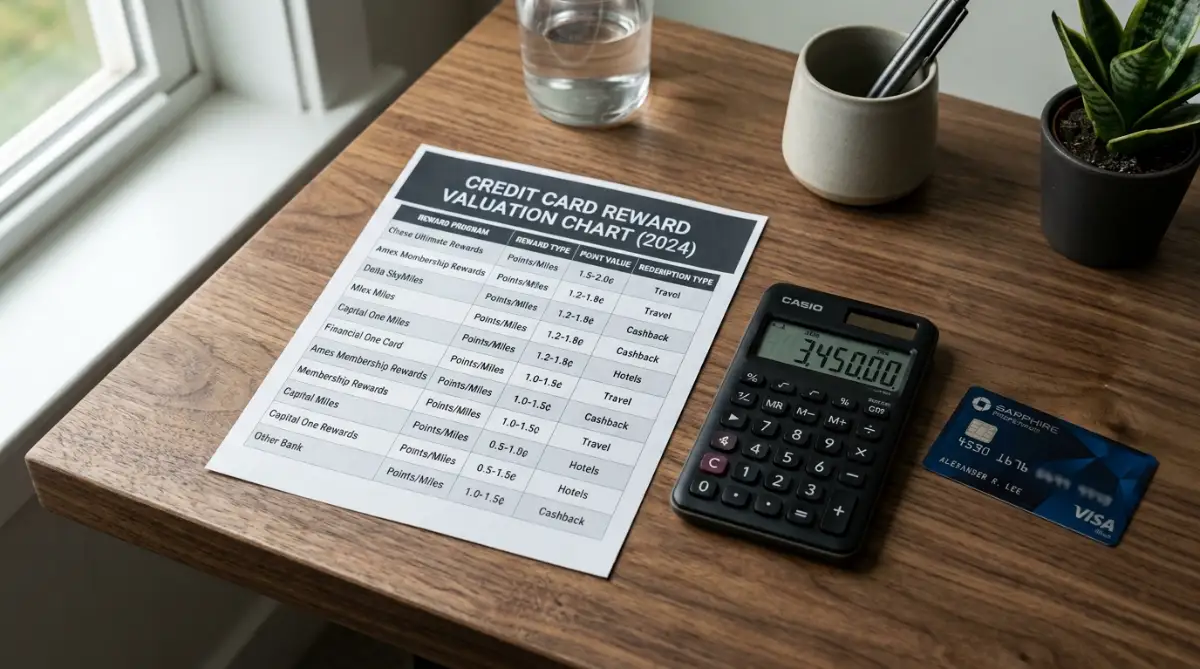
I have worked with hundreds of credit card users who faced this exact confusion. You swipe your card daily expecting real financial returns, only to realize your earned points are locked inside a complex redemption system.
When you do not understand the math behind reward structures, choosing a card feels like guessing. You wonder if you are leaving free money on the table by picking simple cash back over flexible points.
The truth is that neither option is universally better for everyone. By analyzing your real spending habits and understanding reward math, you can select the card model that delivers maximum dollar value into your pocket.
Cash Back vs. Reward Points: The Complete Breakdown
Understanding the fundamental differences between cash back and reward points is essential before filling out any credit card application. Each system targets a completely different financial mindset and spending lifestyle.
Let us examine how these two reward models compare across key operational categories.
Core Operational Factors
Evaluating value certainty, redemption flexibility, and annual fee risks ensures you choose a reward currency that matches your everyday financial habits.
Comparing Cash Back and Reward Points
Myth vs Reality: Credit Card Rewards
Myth: "Travel reward points are always more valuable than cash back."
Reality: Points are only more valuable if you redeem them for high-value travel; redeeming points for cash back often results in terrible conversion rates.
My Personal Pro Tip: Here is a personal mistake I made early on: I used to redeem my travel reward points for Amazon purchases and gift cards at a terrible valuation. An experienced cardholder pointed out that I was getting less than half a cent per point, which completely defeated the purpose of a travel card. My pro tip is to use travel points strictly for flights or hotel transfers, and stick to a flat-rate cash-back card if you prefer statement credits. If a redemption offers less than 1.0 cent per point, use cash back instead.
Watch this short breakdown from NerdWallet to see how travel rewards compare against cash back credit cards:
Advanced Strategies to Maximize Every Dollar Spent
Once you understand the basic differences between cash back and reward points, adopting expert optimization strategies helps you get the maximum value from your credit cards. Managing your cards strategically ensures that card companies pay you, rather than the other way around. I have helped many credit card holders double their annual earnings simply by changing how they align their daily spending with specific card products. These pro-level secrets will help you extract top value while protecting your financial profile. One effective approach involves building an automated cash-back savings engine. If you prefer simplicity, you can automate your cash-back rewards to build passive wealth effortlessly. Most modern credit card portals allow you to set up automatic monthly cash-back redemptions directly into a linked high-yield savings account. To ensure your financial foundation remains secure while expanding your credit portfolio, you can review our guide on how to improve your credit score to prepare your file effectively.
Another powerful tactic is mastering the hybrid credit card strategy. You do not have to limit yourself strictly to cash back or travel points, as a hybrid strategy combines the consistency of cash back with the high upside of travel reward points. Use a flat-rate cash-back card for everyday bills like insurance and home repairs, while using a flexible points card for high-bonus categories like flights and dining. If you are balancing student loans or educational financing alongside your rewards journey, reviewing insights on federal vs private student loans helps you manage overall debt obligations safely. For small business owners or freelancers managing commercial credit card portfolios, you can explore resources on easy AI website builders for small businesses to establish professional online branding and extra revenue streams.
Furthermore, maintaining household protection against unexpected liability keeps your overall financial house in order. For related insights on safeguarding your personal assets and insurance standing, check out tips on how to choose your first home insurance policy without unnecessary anxiety. For students or young adults looking into affordable ways to continue their education without accumulating toxic debt, researching options like best community colleges in the USA provides affordable avenues for academic growth. Keeping your financial records organized and your reward strategies focused protects your purchasing power for major life decisions.
Mistakes That Destroy the Value of Your Rewards
Earning credit card rewards is exciting, but simple mistakes can instantly wipe out all your hard-earned gains. Knowing what pitfalls to avoid keeps your credit card setup profitable and stress-free.
Carrying Balances and Paying High APR Interest
The single fastest way to lose money on a rewards credit card is carrying a monthly balance, as high interest rates quickly erase any points or cash back earned.
Redeeming Flexible Travel Points for Low-Value Options
Redeeming travel points directly for statement credits or gift cards often yields terrible conversion rates, wasting the high potential value of your accumulated miles.
Simple Do's and Don'ts for Reward Optimization
- Do redeem cash back regularly to prevent funds from sitting idle in reward portals.
- Do transfer travel points to partner airlines during promotional bonus periods.
- Do monitor your card accounts monthly to ensure bonus categories register properly.
- Don't buy unnecessary items just to reach a sign-up bonus spending threshold.
- Don't redeem travel reward points for Amazon purchases or statement credits.
- Don't pay annual fees on cards whose perks you fail to use regularly.
Final Decision Blueprint: Pick Your Winner Today
Choosing between credit card rewards and cash back comes down to honest self-assessment. Neither option is superior on its own; the right choice depends on your lifestyle, travel habits, and financial goals.
- Choose Cash Back if: You want hassle-free savings, do not travel frequently, and want to deposit extra dollars straight into your bank account.
- Choose Reward Points if: You fly at least two or three times a year, stay in hotels regularly, and enjoy transferring points to airline loyalty partners.
- Choose a Hybrid Setup if: You want baseline cash-back savings on groceries and gas, alongside a single travel card for annual family trips.
Choosing the right reward model is one of the easiest ways to make your everyday spending work for your financial goals. I know how confusing point valuation charts and transfer rules can feel at first, but taking ten minutes to audit your spending today gives you instant clarity. Trust your instincts, pick the strategy that fits your real lifestyle today, and enjoy the rewards you earn!
Recommended Reading Resources
Explore these internal guides to master your overall financial strategy:
- How to Improve Your Credit Score Before Applying for a Mortgage
- Federal vs Private Student Loans Guide
- How to Choose Your First Home Insurance Policy Without Stress
- Easy AI Website Builders for Small Businesses Simple Setup Guide
- Best Community Colleges in the USA for Affordable Education
Frequently Asked Questions
Which option is better for beginners: cash back or points?
Cash back is significantly better for beginners because it provides clear, guaranteed value with zero learning curve or complex redemption rules.
Do cash-back earnings count as taxable income?
No, standard credit card cash back and reward points are classified by tax authorities as purchase discounts rather than taxable income.
Should I cancel a rewards card if I no longer use it?
If the card has no annual fee, keep the account open to maintain your credit age; if it carries a fee, ask to downgrade to a zero-fee version.
What is the Cents Per Point (CPP) formula?
CPP is calculated by dividing the monetary value of a reward in dollars by the total points required, then multiplying the result by 100.
Do credit card reward points expire?
Points on cash-back cards rarely expire, but travel points can expire or lose value if airline or bank loyalty programs change their terms.
Disclaimer: This article is strictly for educational and informational purposes and does not constitute formal financial, tax, or legal advice. Credit card reward programs, point valuations, redemption ratios, and annual fees are subject to change by card issuers at any time. Always review official card terms and conditions from issuing banks before submitting a formal application.


