How a Broken Winter Furnace Taught Me the Value of Fast Emergency Cash
I remember working with Alex, a freelance software developer whose home heating furnace completely broke down in the middle of a harsh winter. With repair costs estimated at $3,500 and freezing temperatures forecasted, waiting two weeks for a traditional bank loan was out of the question.
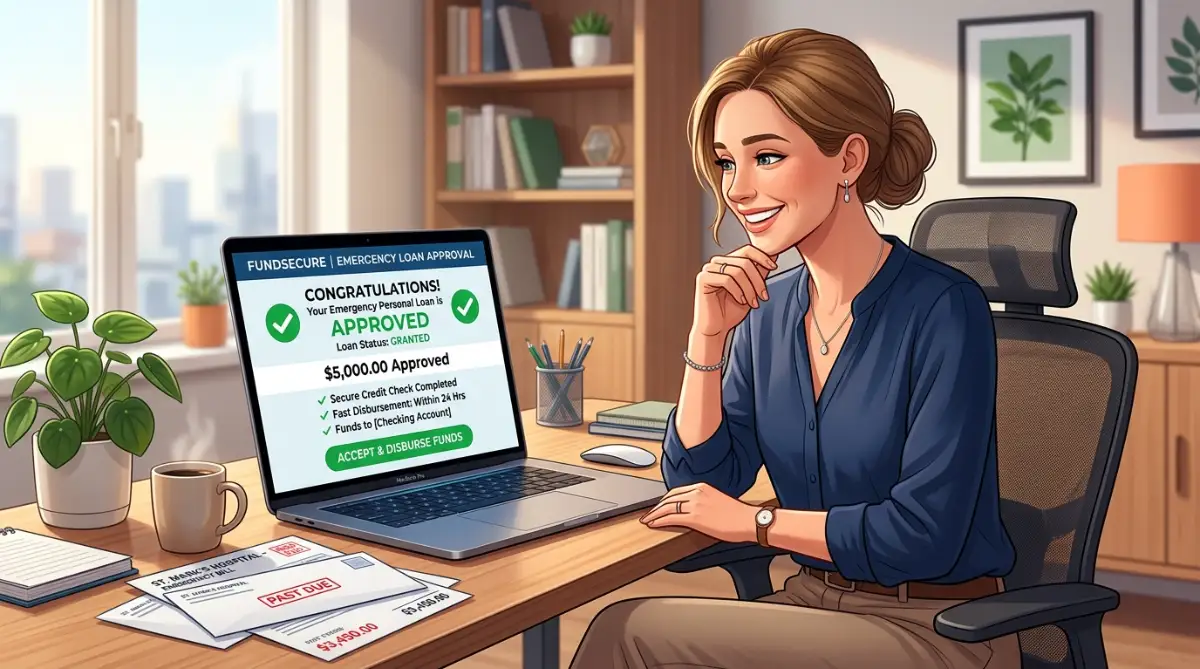
Fearing high-interest credit card cash advances, I helped Alex complete a soft-pull pre-qualification form on a reputable online lending platform. Within ten minutes, he reviewed three pre-qualified offers, selected an unsecured personal loan with a 9.8% APR, and received direct deposit funding in his checking account by noon the next day.
My heart felt light seeing him repair his furnace immediately while keeping his monthly budget completely stable. His story demonstrates how personal loans can serve as a dependable financial bridge during unexpected crises.
Life is filled with unexpected financial turning points that require immediate attention. Whether you face an urgent hospital bill, a car breakdown, or home repairs during a storm, emergency cash needs require rapid solutions.
During moments of sudden cash distress, traditional bank loan processes with paper application delays often prove completely impractical. When an urgent bill arrives, waiting weeks for a credit decision is simply not an option for working families.
Fortunately, understanding how emergency personal loans work allows you to secure fast funding safely without putting your personal property at risk. Let's explore how you can handle unexpected bills without falling into expensive debt traps.
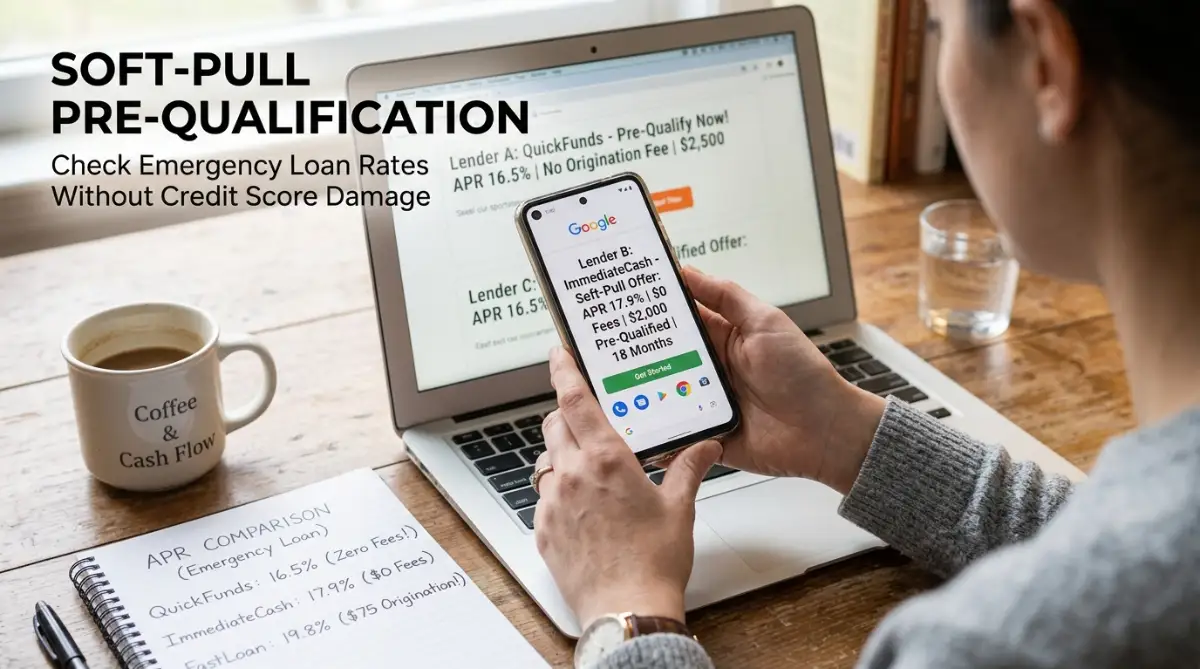
The operational delay of traditional banks explains why millions of consumers turn to online personal loans for emergency expenses. Powered by modern financial technology platforms, online emergency loans offer digital pre-qualification within minutes.
Approved funds are deposited directly into your checking account as fast as the same day or next business day. Most importantly, unsecured emergency personal loans require zero physical collateral, keeping your home, car, and savings safe.
In this comprehensive personal finance guide, we unpack the mechanics of emergency personal loans, evaluate key borrowing metrics, explain soft pre-qualification, and share a practical framework for safe borrowing.
Taking time to understand interest rates and fee structures ensures you pick an affordable loan even during a high-pressure crisis.
Let's step through the fundamental principles of emergency borrowing so you can protect your financial stability.
Understanding Personal Loans for Emergency Expenses
An emergency personal loan is an unsecured installment loan designed to cover unexpected household bills quickly. Unlike a mortgage or auto loan, it does not require you to pledge any physical property as collateral.
When you qualify, the lender deposits a lump sum of cash directly into your checking account, often within 24 hours. You then pay back this balance in fixed monthly installments over a set period of years.
Because there is no collateral involved, lenders rely heavily on your credit profile and income to determine your interest rate. Maintaining a healthy credit score ensures you qualify for the lowest borrowing rates when a crisis hits.
The Fast-Track Soft Pre-Qualification Method
When facing an urgent bill, using soft-pull pre-qualification allows you to view customized loan offers across multiple lenders in a single afternoon. A soft credit pull checks your rate options with zero impact on your credit score.
Comparing pre-qualification quotes lets you evaluate Annual Percentage Rates (APRs) and fee terms side-by-side before submitting any binding application. Once you select the best offer, a single hard credit check is performed to finalize your loan documents.
This soft-check comparison method protects your credit score during rate shopping, ensuring you do not trigger multiple hard inquiries during an emergency.
Key Financial Metrics by Borrower Credit Tier
Evaluating APRs, Origination Fees, and Prepayment Terms
In the rush to secure fast cash for an emergency bill, it is easy to overlook critical loan terms. Comparing competing loan offers requires looking beyond the monthly payment figure to evaluate total borrowing costs.
The Annual Percentage Rate (APR) represents the true annual cost of borrowing money. Unlike simple interest rates, APR includes both the base interest rate and any mandatory lender fees, such as origination fees.
Some emergency lenders charge an upfront origination fee (typically 1% to 8% of the loan amount) to cover administrative processing. This fee is deducted directly from your initial loan deposit (for example, a $5,000 loan with a 5% fee yields a $4,750 deposit).
Always prioritize lenders that charge zero prepayment penalties. Lenders with no early payoff penalties allow you to pay off your balance early to save money on interest once your emergency passes.
Debunking Common Emergency Borrowing Myths
- Myth 1: Emergency personal loans always take weeks to disburse cash to your bank.
- Reality: Modern digital lenders use automated verification systems to approve applications and disburse funds within 24 to 48 hours.
- Myth 2: You must put up your car title to get a fast emergency loan online.
- Reality: Unsecured emergency personal loans require zero collateral, keeping your vehicle and home completely safe from repossession risk.
- Myth 3: Credit card cash advances are cheaper than personal loans for emergency cash.
- Reality: Credit card cash advances carry immediate cash advance fees and high interest rates (25%+ APR) with no grace period, making unsecured personal loans far cheaper.
My Personal Pro Tip: Whenever I face an urgent emergency bill, I never apply directly to multiple lenders at once! I always use soft-pull pre-qualification forms to check rates across three or four licensed online lenders in under ten minutes without hurting my credit score. It allows me to choose the absolute lowest APR safely before any hard credit check touches my report!
If you want a detailed video breakdown explaining how emergency personal loans work and how to get funded safely, watch this video below:
Advanced Strategies to Manage Emergency Loans and Build Credit
Handling an emergency expense safely is the immediate goal; managing your loan responsibly is what builds long-term financial strength. Once your loan is approved, making consistent, on-time monthly payments transforms your emergency debt into a credit-building tool.
The first advanced strategy is setting up automated monthly auto-pay through your checking account. Most online lenders offer a 0.25% APR discount when you enroll in automatic drafts, keeping your payments punctual while lowering interest costs.
The second strategy is using a fixed-rate personal loan to replace high-interest credit card debt accumulated during emergencies. Consolidating variable credit card debt into a structured installment loan lowers your credit utilization ratio, which often boosts your credit score within a few months.
If you are working on improving your credit profile for major life goals, staying proactive is essential. Learning how to improve your credit score before applying for a mortgage provides a valuable step-by-step framework for credit optimization.
Similarly, taking steps to safeguard your household against physical accidents protects your finances. Learning how to choose your first home insurance policy without stress safeguards your living space from storm damage or unexpected repairs.
If you are managing student debt alongside family expenses, organizing your commitments is necessary. Reviewing federal vs private student loans: how to choose wisely helps you make smart decisions about educational debt.
Students attending the best community colleges in the USA for affordable education often avoid heavy debt burdens by keeping their tuition costs low from the start.
Finally, if you run a small business or side hustle to earn extra income, keeping overhead low protects your monthly cash flow. Utilizing easy AI website builders for small businesses allows you to build a professional website quickly without spending thousands on developers.
 Major Pitfalls to Avoid During Emergency Borrowing
While emergency personal loans offer fast relief, making hasty decisions during a crisis can lead to financial mistakes. Knowing common borrowing traps protects your family budget.
The most dangerous pitfall is falling for high-cost payday loans or car title loans that advertise "no credit check." These predatory products carry interest rates exceeding 300% APR and threaten your vehicle with immediate repossession.
Another major mistake is borrowing more money than you actually need for your emergency expense. Requesting extra cash just because a lender approves a higher limit increases your monthly payment burden unnecessarily.
Lastly, avoid signing loan contracts with heavy origination fees and prepayment penalties. Always verify that your lender allows penalty-free early payoff so you can clear your debt early when extra funds become available.
Navigating Financial Emergencies with Complete Confidence
Unsecured personal loans offer a fast, flexible, and transparent financial tool for bridging life's unexpected emergencies. By eliminating collateral requirements, providing soft pre-qualification, and offering fast direct deposit, online lenders help families manage cash gaps safely.
Remember to calculate your exact need, compare pre-qualification offers, and choose a transparent lender. Taking a structured approach to emergency borrowing protects your long-term financial health while resolving short-term crises.
I know how stressful it feels when an unexpected emergency expense threatens your family's budget. Taking control of your personal finances with a clean, transparent emergency loan gives you immediate peace of mind, and I am always here to guide you toward safe, affordable financial choices!
Frequently Asked Questions About Emergency Personal Loans
How fast can I get direct deposit funding for an emergency personal loan?
Many digital lenders offer automated verification systems that process applications within hours, depositing approved funds directly into your checking account as fast as the same business day or the next business day.
Can I get an emergency personal loan if I have bad or fair credit?
Yes, many online lenders evaluate applicants with fair or rebuilding credit (scores below 670). Pre-qualifying online allows you to review real approval options without affecting your credit score, and applying with a co-signer can lower your interest rate.
Are emergency personal loans better than credit card cash advances?
Yes. Credit card cash advances carry immediate cash advance fees, high interest rates (25% to 30%+ APR) with no grace period, and variable monthly payments. Personal loans offer fixed APRs, lower overall borrowing costs, and structured payoff dates.
What documents do I need to apply for an emergency personal loan?
Most digital lenders require a government-issued photo ID, proof of income (recent pay stubs, W-2s, or bank statements), active checking account details for direct deposit, and proof of residence.
Does pre-qualifying for an emergency personal loan hurt my credit score?
No, soft-pull pre-qualification allows you to check customized rates across multiple lenders with zero impact on your credit score. A hard credit inquiry occurs only when you formally accept a loan offer.
Category Disclaimer
The information provided in this article is for educational and informational purposes only and does not constitute formal financial, credit, legal, or lending advice. Personal loan interest rates (APRs), origination fees, funding speeds, and approval criteria vary based on individual creditworthiness, income verification, lender underwriting policies, and regional regulations. Always consult with a certified financial planner or credit counselor before signing binding loan agreements.