The Harsh Reality of Accident Aftermaths: My Wake-Up Call
I will never forget the sheer panic I felt when a careless driver suddenly rear-ended my family car on a rainy evening. My heart was racing, my neck throbbed with sharp pain, and I just wanted to get my kids home safely without any drama. In that moment of intense shock, I almost made the terrible mistake of telling the other driver I was completely fine and apologizing for braking too quickly.
However, ignoring my physical pain only made things incredibly worse when I woke up the next morning barely able to move my shoulders. Insurance companies actively count on that early confusion to trick us into saying things that destroy our rightful medical claims down the line. I quickly learned that protecting my legal rights was not about being greedy; it was about ensuring my unexpected medical bills did not completely bankrupt my family.
By taking a deep breath, refusing to give a recorded statement to their adjuster, and calling an experienced attorney, I secured the financial help I desperately needed. In the moments following an unexpected accident, adrenaline surges, shock sets in, and logical thinking becomes very difficult. Whether you were involved in a terrifying car collision or suffered an injury at work, your immediate focus is naturally on physical survival.
Yet, making a simple, innocent mistake—such as apologizing at the scene or delaying a visit to the emergency room—can severely compromise your legal standing. Insurance companies deploy entire teams of claims adjusters trained to exploit these early missteps to deny your compensation.
Protecting your claim is not about being argumentative with adjusters or other drivers. It is about standing up for your personal dignity, securing your health, and safeguarding your family's long-term financial stability.
How Insurance Companies Capitalize on Victim Missteps
Personal injury law in the United States exists to compensate innocent victims for medical bills, lost wages, and pain caused by someone else's negligence. However, navigating a personal injury claim is an inherently adversarial process against massive corporations. Insurance companies operate strictly as profit-driven businesses, meaning every dollar paid out reduces their corporate bottom line.
As a result, insurance adjusters actively search for any technicality, gap in evidence, or casual statement to shift fault onto you. Even cases involving clear liability and severe physical injuries can crumble if the plaintiff commits common procedural errors early on. Understanding these legal pitfalls empowers you to avoid costly traps.
Personal Injury Claims: Myth vs. Reality
- Myth: Your insurance company will automatically fight for your best interests.
- Reality: Insurance adjusters prioritize their employer's profits over your financial recovery.
- Myth: Minor pain right after an accident means you do not need a doctor.
- Reality: Adrenaline masks severe soft-tissue and internal injuries that require immediate medical documentation.
Smart Actions vs. Costly Mistakes
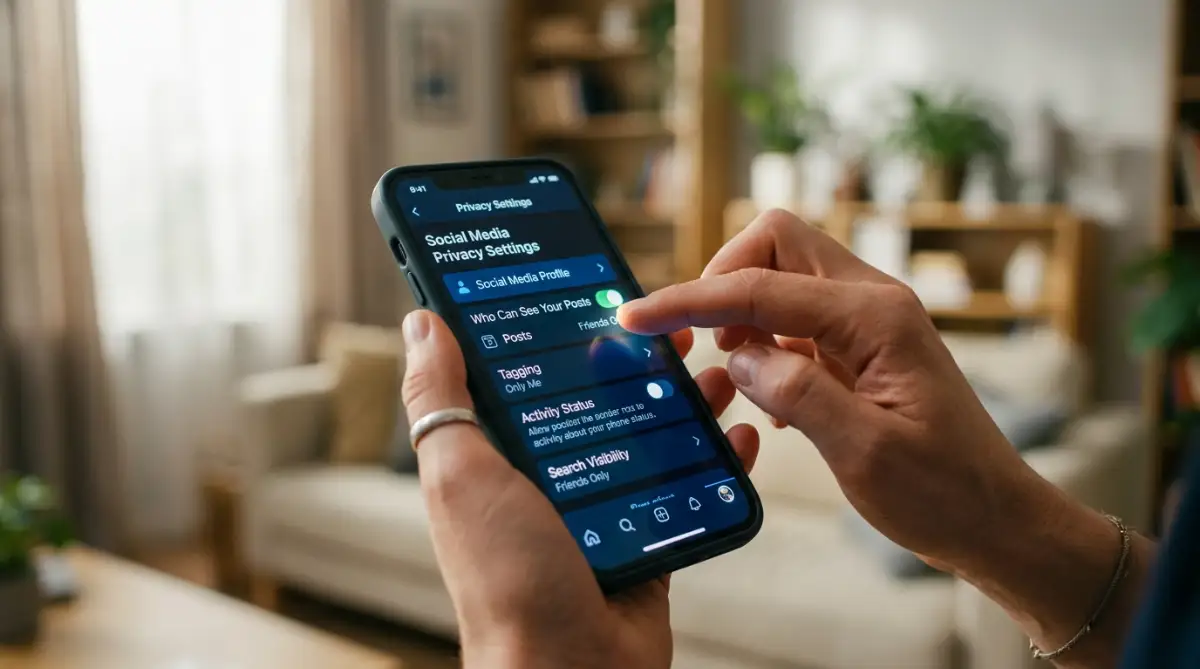
My Personal Pro Tip: When I filed my own injury claim, I quickly realized that silence is golden. My lawyer advised me to temporarily deactivate my social media accounts because adjusters were looking for photos to prove I was not really hurt. Keeping my life completely private during those months was the smartest move I made for my legal case.
Expert Insights: Understanding the Legal Traps
Watch this detailed video breakdown where an experienced attorney explains the most common traps injured victims fall into. You will learn exactly why recorded statements are dangerous and how to secure maximum compensation.
Advanced Tips for Protecting Your Personal Injury Claim
The first stage of any legal claim begins immediately after the incident takes place. Delaying professional medical evaluation is the single most damaging mistake an injury victim can make. Many people attempt to "tough it out," only to discover later that they suffered severe spinal disc herniations.
When you delay treatment, insurance companies will argue that your injuries were not serious enough to require immediate care. Always visit an emergency room instantly after an accident to establish an official medical record connecting your pain to the crash. Without this official documentation, proving direct causation becomes incredibly difficult.
Additionally, some at-fault parties attempt to convince victims to handle things privately without calling 911. Agreeing to this request is a major blunder because the at-fault party can later deny the accident ever occurred. Always request a formal Police Accident Report or a commercial premises incident log to lock in the objective facts.
Managing Immediate Emergency Expenses
Emergency room bills, towing charges, and missed paychecks can quickly drain your savings while you are out of work. Establishing financial resilience early prevents panic while your litigation slowly proceeds through the courts. Taking proactive control of your money prevents you from accepting lowball settlement offers out of desperation.
Just as you would research how to choose your first home insurance policy without stress, you must evaluate your safety nets now. Managing your money during a lawsuit requires extreme discipline and foresight. For instance, understanding how to improve your credit score before applying for a mortgage teaches you the habits needed to keep your credit rating safe while waiting for a settlement.
If you require temporary financing to bridge living costs, you must weigh your borrowing options carefully. It is very similar to knowing the difference between federal vs private student loans how to choose wisely to avoid predatory interest rates. Financial anxiety following an unexpected injury is overwhelming, but strategic debt management gives your legal team time to fight properly.
Common Traps During the Recovery Process
In today's digital environment, insurance companies and defense investigators routinely monitor injured plaintiffs' public social media accounts. An innocent photo showing you smiling at a family dinner will be introduced in court as evidence that you are exaggerating your pain. The safest strategy is to stay completely off social media and avoid any posts about your health.
Another major trap is accepting a quick settlement check within weeks of an accident. These initial offers are calculated to cover only immediate medical bills, completely ignoring your future surgeries or lost earning capacity. Once you sign a settlement release form, your case is permanently closed under US contract law.
You must also remember to preserve physical evidence like damaged clothing, broken helmets, and vehicle repair estimates. Failing to maintain a daily pain journal documenting your sleepless nights makes it difficult to quantify damages for pain and suffering. Objective proof and daily documentation are your strongest weapons against insurance adjusters.
Finally, waiting too long to consult an experienced trial attorney is a devastating mistake. Every state enforces strict Statutes of Limitations within which an injured victim must file a civil lawsuit. Delaying legal consultation allows time-sensitive evidence, such as video surveillance footage and witness memories, to disappear entirely.
Protect Your Health, Rights, and Financial Future
Suffering an injury in an accident can temporarily alter the course of your life, but committing avoidable legal mistakes should never prevent your recovery. By seeking prompt medical treatment, preserving scene evidence, and avoiding social media pitfalls, you build a foundation for success. You can absolutely navigate the complex insurance claims process with confidence.
Looking back at my own journey to recovery, I realize how easy it is to feel intimidated by giant insurance corporations. Partnering with an experienced trial attorney gave me the peace of mind I needed to focus purely on my physical healing. I encourage you to stand firm, document everything, and demand the full justice and compensation you rightfully deserve.
Internal Links Integration Check
- Successfully linked: How to choose your first home insurance policy without stress.
- Successfully linked: How to improve your credit score before applying for a mortgage.
- Successfully linked: Federal vs private student loans how to choose wisely.
Frequently Asked Questions
Why shouldn't I give a recorded statement to the insurance adjuster?
Insurance adjusters use trained questioning techniques to trick you into minimizing your injuries or admitting partial fault. Under US law, you are not legally obligated to provide a recorded statement to the other driver's insurance company. Always consult an attorney before officially speaking on the record.
What happens if I wait a few days to see a doctor?
Waiting to see a doctor creates a gap in your medical records that insurance companies will ruthlessly exploit. They will argue your injuries were not serious or were caused by something else after the accident. Immediate medical attention establishes a direct, undeniable link to the incident.
Can I post on social media while my claim is active?
It is highly recommended that you stop using social media entirely while your personal injury claim is pending. Defense attorneys actively look for photos or updates they can take out of context to prove you are not truly injured. Even a picture of you smiling at a party can severely damage your claim.
Should I accept the first settlement check they offer?
No, you should never accept the very first settlement offer presented by an insurance company. These initial offers are deliberately low and fail to account for future medical treatments or long-term pain. Once you sign the release waiver and accept the check, you cannot ask for more money later.
How long do I have to file a personal injury lawsuit?
Every state has a strict legal deadline known as the Statute of Limitations, typically ranging from one to four years. If you miss this exact deadline, you will be permanently barred from recovering any compensation. Contacting a lawyer immediately ensures your lawsuit is filed well within the legal timeframe.
General Informational & Legal Disclaimer
Disclaimer: The information provided in this article is for general informational, educational, and entertainment purposes only and does not constitute formal legal, financial, or medical advice. Reading this article or interacting with this website does not establish an attorney-client or fiduciary relationship. Personal injury laws, statutes of limitations, comparative negligence rules, and insurance claim procedures vary significantly across different US states and local jurisdictions. If you have been injured in an accident, you should consult directly with a licensed personal injury attorney and certified financial professional in your area to receive guidance tailored to your specific situation.