The Complete Guide to Renters Insurance: Protecting Your Apartment
Moving into a new apartment or rental home is an incredibly exciting transition. Whether you are renting your first studio apartment, sharing a townhome with roommates, or leasing a quiet suburban space, placing your personal furniture, artwork, and electronics inside transforms those four walls into your personal sanctuary. It is the place where you relax after long workdays, host friends, and store everything you hold dear.
However, many tenants live under a dangerous financial misconception. They mistakenly assume that if an upstairs neighbor's washing machine overflows, a grease fire breaks out in the kitchen, or a burglar forces entry through a window, their landlord's property insurance policy will automatically pay to replace their personal belongings. This is one of the most widespread and expensive mistakes in the rental world.
A landlord's insurance policy covers strictly the physical building structure—the brick walls, roof, and plumbing pipes. It pays zero dollars to replace your clothes, furniture, laptop, or personal valuables. Without dedicated renters insurance, a single plumbing burst or apartment break-in can wipe out your entire personal net worth in minutes. Let us explore how simple, inexpensive renters insurance works and how you can protect your rental space with total confidence.
I still vividly remember coming home on a rainy Tuesday evening during my second year of renting, opening my apartment door, and hearing water dripping from my ceiling light fixture. The upstairs neighbor's bathroom pipe had burst, soaking my work laptop, couch, and vintage guitar. When I called my building manager, he bluntly told me, "Our insurance covers the drywall, but your personal stuff isn't our responsibility." Standing in two inches of water holding a ruined laptop was a devastating lesson. The next morning, I purchased a $15 monthly renters insurance policy, promising myself I would never leave my personal life unprotected again, and I want to help you avoid that same heartbreak.
Why Understanding Renters Insurance Feels So Confusing
Despite being one of the cheapest financial safety nets available, millions of tenants remain uninsured or underinsured due to persistent industry roadblocks:
- The Landlord Coverage Illusion: Property managers rarely explain the boundaries of building insurance, leaving tenants falsely believing their personal possessions are protected under the lease agreement.
- Roommate Policy Misunderstandings: Tenants assume a single renters policy automatically covers everyone living under the same roof, leading to denied claims when a roommate's belongings are stolen.
- Confusion Over Payout Valuation: Most renters don't know the difference between Actual Cash Value (ACV) and Replacement Cost Value (RCV), unknowingly buying cheap policies that pay pennies on the dollar for damaged items.
- Redundant Device Warranties: People waste hundreds of dollars annually on separate store warranties for phones and laptops, unaware that a standard $15/month renters policy covers ALL their electronics simultaneously!
The Emotional Toll of Unprotected Rental Living
Living without renters insurance creates an underlying background noise of vulnerability that impacts your daily peace of mind:
Travel and vacation anxiety leaves you constantly worried about apartment break-ins, pipe leaks, or electrical fires whenever you leave your apartment empty over the weekend. Furthermore, the fear of liability lawsuits—worrying that a guest slipping on a wet kitchen floor or a dog nip on a visitor will result in thousands of dollars in out-of-pocket medical bills—adds a heavy layer of stress.
The true worth of renters insurance isn't just getting a check after a fire—it's the everyday feeling of security inside your home. It's locking your front door before going on a two-week vacation and knowing that even if the worst happens, your clothes, electronics, and furniture can be replaced without wiping out your savings. For the cost of three cups of coffee a month, renters insurance buys complete financial freedom in your living space.
Visual Insight: What Is Renters Insurance?
Watch this clear and concise educational guide from The Hartford to understand the core pillars of renters insurance, personal property limits, liability shields, and average monthly costs!
The 3 Core Pillars of Renters Insurance
A standard HO-4 renters policy provides three primary layers of financial protection:
1. Personal Property Protection (Coverage C)
This pillar reimburses the cost of repairing or replacing your personal possessions—including clothing, furniture, TVs, laptops, kitchen appliances, and bicycles—if damaged by covered perils like fire, smoke, explosion, windstorm, or theft.
Bonus Feature: Most high-quality policies include "off-premises coverage," meaning your belongings are protected from theft even when outside your apartment, such as in your car trunk or hotel room!
2. Personal Liability Coverage (Coverage E)
Liability protection acts as your legal shield if you accidentally cause property damage or bodily injury to others. For example, if you accidentally leave a kitchen tap running and cause $10,000 in water damage to the apartment below you, your liability coverage pays for their structural repairs and legal fees, preventing personal financial ruin.
3. Loss of Use / Additional Living Expenses (Coverage D)
If a severe fire or storm renders your rental unit uninhabitable during major repairs, loss of use coverage pays for temporary hotel stays, short-term apartment rentals, restaurant meal price differences, and moving storage fees until your apartment is restored.
The Roommate Trap & Police Report Requirements
Avoid these two critical operational blunders that result in immediate claim denials:
1. The Roommate Laptop Trap
Standard renters insurance policies strictly cover the personal property of the specific policyholder named on the contract. If your roommate's laptop is stolen or their bedroom furniture is ruined by water, your policy will NOT pay a single dollar to replace their items!
To protect your roommate, they must be officially added to your policy as an "additional insured," or they must purchase their own independent policy. Having separate, individual policies is almost always safer because joint claims can complicate payout checks and claims records.
2. The Mandatory Police Report Rule
If your apartment is burglarized or your bicycle is stolen from your balcony, you must contact local police immediately. Insurance companies will automatically reject any theft claim that lacks an official Police Report Number.
The police report serves as the legal proof required by claims adjusters to verify that a crime took place. Always file a police report before submitting theft documentation to your insurer.
Replacement Cost Value (RCV) vs. Actual Cash Value (ACV)
Pay close attention to how payouts are calculated when setting up your policy limits:
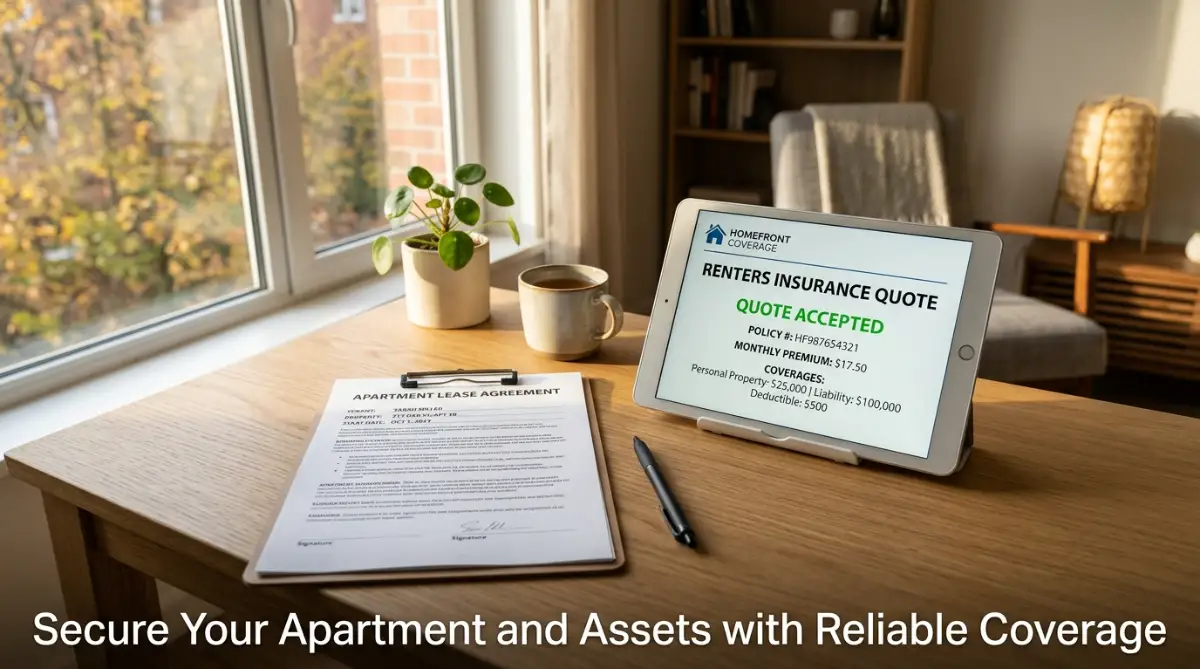
Choosing Replacement Cost Value (RCV) adds only $1 to $3 per month to your premium but guarantees complete replacement power during a claim.
Step-by-Step Blueprint to Secure the Best Coverage
Follow this actionable step-by-step checklist to set up an airtight renters policy:
Step 1: Conduct a Smartphone Video Walkthrough
Walk through your apartment filming open closets, shoe racks, electronics, furniture, and kitchen tools. State purchase dates and estimated values on video. Upload this file to secure cloud storage so it remains accessible if your phone is destroyed.
Step 2: Establish an Emergency Buffer for Deductibles
Select a policy deductible (typically $500 or $1,000) that aligns with your cash savings. Take time to read our complete guide on building financial readiness and credit health to maintain liquid cash reserves that cover your deductible comfortably during an emergency.
My Personal Pro Tip: When I updated my renters policy last year, I chose to bundle it with my car insurance carrier. Doing this instantly knocked 20% off my renters insurance bill, making the upgraded replacement cost coverage practically free while keeping my budget clean.
Step 3: Bundle Auto and Renters Policies for Discounts
If you own a car, buy your renters insurance from your auto insurer. Multi-policy bundling discounts routinely save 15% to 20% across both accounts, making your renters policy nearly free! For more ideas on handling multi-asset protection, check out our comprehensive property security advice.
Dangerous Pitfalls That Put Your Finances at Risk
Protect your wallet by avoiding these critical financial mistakes:
1. Using High-Interest Credit for Emergency Replacement: Uninsured property theft forces renters onto 25%+ credit cards. If you carry existing personal debts, studying smart debt restructuring and repayment options will help you streamline monthly obligations and preserve healthy cash flow.
2. Rushing Into Predatory Emergency Loans: Taking out rushed personal loans to replace lost gear without checking interest rates triggers severe financial stress. Review standard personal loan mistakes you must avoid before taking on debt, and ensure you know what happens if you miss an EMI payment to safeguard your credit score during unexpected financial challenges.
Reclaiming Joy in Your Living Space
At the end of the day, your rental home should be a place of relaxation, warmth, and peace—not a source of hidden financial anxiety. When you take fifteen minutes to set up proper replacement cost coverage, record a digital video walkthrough, and set liability limits to $100,000+, you build a solid wall around your personal life. You can invite guests over, travel with confidence, and sleep soundly knowing your sanctuary is 100% secure.
I feel a deep sense of gratitude knowing my space is secure, and I truly want you to experience that same effortless peace of mind in your apartment.
Quick Guide: Renters Insurance Do's and Don'ts
Helpful Q&A for Apartment Tenants
Is renters insurance required by law in the United States?
No, renters insurance is not mandated by state or federal laws. However, private landlords and property management companies legally require tenants to show proof of active coverage before signing a lease agreement.
Does renters insurance cover items stolen from my car trunk?
Yes! Most renters policies include "off-premises coverage," meaning your personal belongings are protected from theft even when outside your apartment, such as in your vehicle or hotel room.
Does renters insurance pay for a hotel if my apartment floods?
Yes, the Loss of Use (Additional Living Expenses) coverage pays for temporary hotel lodging, restaurant meals, and storage fees if your rental unit becomes temporarily uninhabitable due to a covered disaster.
Are my roommates automatically covered under my renters policy?
No, standard renters policies only cover the named policyholder. Roommates must either be explicitly listed as additional insured parties or maintain their own separate policies.
What is the difference between RCV and ACV coverage?
Replacement Cost Value (RCV) pays what it costs to buy a brand-new item today, whereas Actual Cash Value (ACV) subtracts depreciation for age and wear, giving you a much smaller payout.
Disclaimer: This article is published exclusively for educational and informational purposes. It does not constitute professional insurance, legal, or financial underwriting advice. Property insurance regulations, liability limits, and coverage rules vary by jurisdiction and carrier. Always consult with a licensed independent insurance agent or certified financial advisor prior to making changes to your renters insurance coverage.