Smart Guide to Shopping for Home Insurance Quotes
Every single year, millions of homeowners face a familiar, deeply stressful moment of financial anxiety. You open your annual home insurance renewal statement, quietly hoping for a stable rate, only to see a massive price increase staring right back at you. You have never filed a single property claim, you maintain your roof in pristine condition, and you pay your monthly bills on time, yet your annual premium continues to climb relentlessly.
You desperately want to find simple, reliable ways to reduce this monthly bill, but the thought of shopping around and comparing quotes leaves you feeling completely overwhelmed. You worry that if you choose a cheaper policy, you might accidentally strip away necessary protections, leaving your family stranded and vulnerable during a natural disaster.
When looking for a way to compare insurance rates safely, homeowners routinely run into a wall of confusion and bad advice. The commercial insurance market is intentionally structured to keep you from easily comparing different quotes side-by-side. But learning how to decode policy disclosures and conduct apples-to-apples comparisons empowers you to protect your wallet and your home at the exact same time.
I still vividly remember opening my home insurance renewal statement last year and seeing a $580 sudden price increase. I felt an immediate wave of anger and frustration. I had paid my premium faithfully for five years without filing a single claim, yet my reward for loyalty was a massive rate penalty. I spent that evening sitting at my kitchen table with three different quote comparison sheets, feeling completely lost because each company used different terminology and hidden deductible structures. Realizing that loyalty to an insurance carrier often costs you money was the wake-up call that pushed me to master the art of quote comparison, and I want to share those lessons with you.
Why Shopping for Home Insurance Quotes Feels Like a Maze
Most homeowners give up on shopping for better insurance rates because the comparison process is designed with frustrating hurdles:
- Confusing Policy Jargon: Quote sheets are written in dry, dense legalese that obscures what coverages you are actually comparing between different insurance carriers.
- The "Apples-to-Oranges" Trap: Shady comparison websites show you deceptively cheap rates by quietly lowering your necessary dwelling limits or stripping away water damage protection behind your back.
- Pushy Sales Call Attacks: Many online quote generators sell your personal contact info to lead brokers, resulting in a barrage of annoying sales calls and relentless spam emails.
- Hidden Deductible Jumps: Companies display low monthly premium prices by secretly raising your out-of-pocket deductibles to five or ten thousand dollars.
The Emotional Toll of Unchecked Premium Inflation
Living with rising housing overhead and unclear insurance options wears down your confidence as a homeowner, turning your greatest physical asset into a source of daily anxiety:
Constant premium anxiety—worrying about whether you can afford rising home insurance alongside increasing utility and grocery bills—is physically exhausting. Furthermore, feeling forced to pay whatever arbitrary price your current insurer demands creates a deep sense of helplessness and financial loss of control.
The hardest part of dealing with rising home insurance premiums isn't just writing the bigger check—it's the feeling that your home is holding your monthly budget hostage. It's cutting back on family activities or delaying basic home repairs just to cover an inflated insurance bill. But once you learn how to standardize coverage limits and demand true apples-to-apples quotes, you regain complete control over your household expenses.
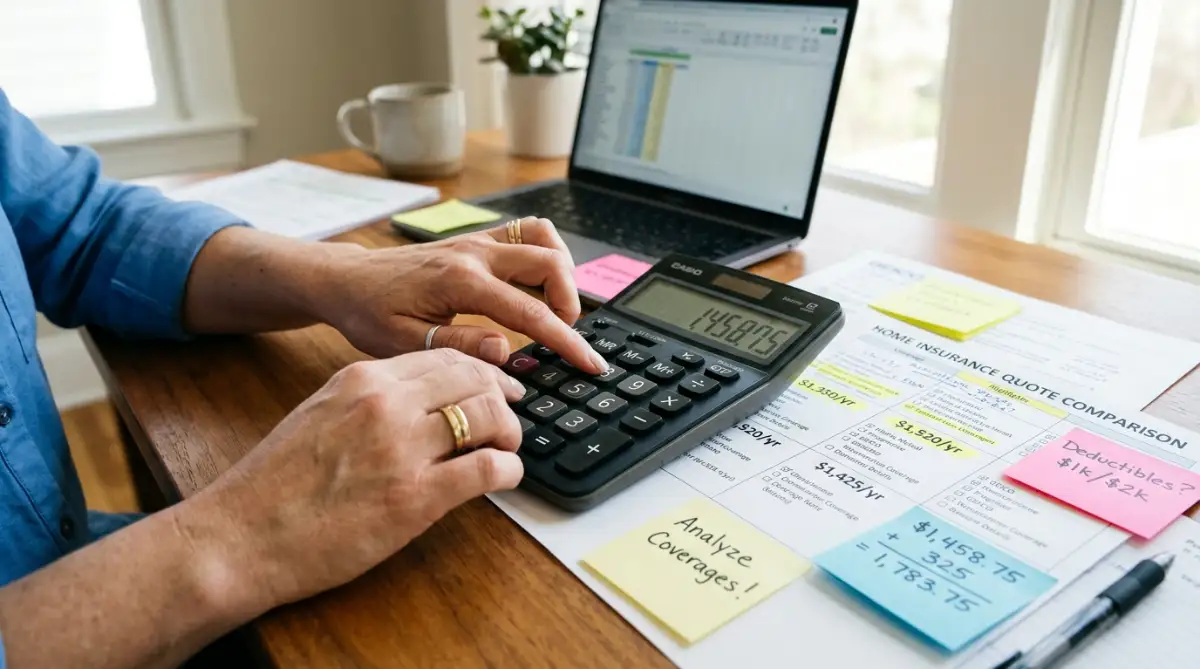
Visual Insight: How to Compare Home Insurance Quotes
Watch this expert video guide from eHowFinance as a licensed insurance agent explains how to compare homeowners insurance quotes side-by-side, verify dwelling limits, and spot hidden policy differences!
A Practical Blueprint to Compare Quotes Safely
Reducing your annual home insurance premium does not require sacrificing basic family protections. Focus on these three core structural comparison steps:
Step 1: Standardize Your Coverage Limits (Apples-to-Apples)
Before requesting new quotes, pull out your current policy Declarations Page and establish a fixed baseline. Use the exact same dollar limits for Dwelling (Coverage A), Personal Property (Coverage C), and Liability (Coverage E) across every quote request.
Comparing quotes with mismatched coverage limits is like comparing a compact sedan to a heavy pickup truck—they serve entirely different purposes. Standardizing your baseline numbers ensures you identify genuine price savings rather than dangerous coverage cuts.
Step 2: Decode the True Deductible Structure
When an online quote sheet displays a strikingly low monthly price, inspect the deductible immediately. Carriers often generate cheap estimates by quietly raising your flat deductible to $5,000 or substituting a 2% percentage-based storm deductible.
Ensure every quote uses the exact same flat deductible (e.g., $1,000) so you are comparing real numbers.
Step 3: Verify Policy Valuation (RCV vs. ACV)
Ensure all competing quotes utilize Replacement Cost Value (RCV) payouts rather than Actual Cash Value (ACV). ACV subtracts depreciation for age, leaving you with pennies on the dollar during a personal property claim.
Advanced Methods: Calculating Your Deductible Break-Even
To determine if raising your deductible to lower your annual premium makes financial sense, execute a simple Break-Even Calculation:
Low Deductible Plan: $1,000 Deductible | Premium: $1,200/year
High Deductible Plan: $2,500 Deductible | Premium: $900/year
Annual Savings: $300 | Extra Out-of-Pocket Risk: $1,500
Break-Even Calculation: $1,500 Risk ÷ $300 Annual Savings = 5 Years
If you remain claim-free for five years, your annual premium savings completely cover your extra out-of-pocket risk. Every claim-free year beyond year five is pure profit for your household budget!
My Personal Pro Tip: When I recalculated my break-even timeline, I realized that taking on a slightly higher deductible saved me enough cash annually to fund my emergency account faster. However, I always make sure that cash stays untouched in savings so I am never caught off guard if a sudden claim happens.
However, never raise your deductible unless you hold liquid cash reserves in reserve. Take time to read our guide on improving your overall financial posture and credit score to establish a cash shield before increasing out-of-pocket deductible limits.
If you have ongoing educational expenses or student debt considerations, you can also explore managing alternative household financing options effectively.
Severe Premium Traps That Can Drain Your Savings
Avoid these critical borrowing and policy pitfalls when shopping for coverage:
The Cumulative Deductible Illusion: Property deductibles apply per claim, NOT per calendar year! Filing three storm claims in a single season means paying your full deductible three separate times.
Filing Small Claims Below Deductibles: Filing a $1,200 fence repair claim with a $1,000 deductible nets you $200 from your insurer but triggers multi-year premium rate surcharges that cost thousands overall.
Because credit-based insurance scores impact annual rates, paying down high-interest balances directly lowers your home insurance bills. Studying smart budgeting and digital financial management tactics allows you to streamline credit card debts and improve your insurance tier.
Furthermore, taking out high-interest credit lines to pay for home repairs during emergency claim delays can trigger financial distress. Review standard personal loan mistakes you must avoid before taking on debt, and make sure you understand what happens if you miss an EMI payment to protect your credit health during unexpected financial slumps.
Reclaiming Joy and Financial Control
At the end of the day, managing your home insurance isn't about giving in to fear—it's about taking active control of your family's financial security. When you standardize your quote comparisons, insist on Replacement Cost Value, and maintain a dedicated emergency savings buffer, you take total command of your property's safety. You can enjoy your home, celebrate family milestones, and sleep soundly knowing your sanctuary is fully protected at a fair price.
I feel an immense sense of relief every renewal season now that I know how to navigate quote shopping without stress, and I hope these strategies bring that same clarity to your household.
Quick Guide: Policy Deductible Do's and Don'ts
Helpful Q&A for Homeowners
What is the most common deductible for standard homes?
A flat $1,000 deductible is the most popular choice for standard single-family homes, offering a healthy balance between affordable monthly premiums and manageable out-of-pocket risk.
What is a CLUE Report and why does it matter?
The Comprehensive Loss Underwriting Exchange (CLUE) report tracks 7 years of property claim history. Reviewing your CLUE report ensures no fraudulent or inaccurate claims are artificially inflating your quotes.
Does shopping for new insurance quotes hurt my credit score?
Standard home insurance quote requests involve a "soft credit inquiry," which has zero impact on your credit score, allowing you to shop around freely.
How do local weather risks affect my home insurance quotes?
Insurers adjust rates based on regional historical data regarding hail, windstorms, and wildfire exposure, meaning quotes can vary significantly between neighboring zip codes.
Should I switch insurance companies every year to get lower rates?
While shopping annually ensures competitive pricing, weigh potential loyalty discounts and claim-free history credits with your current carrier before making a switch.
Disclaimer: This article is published exclusively for educational and informational purposes. It does not constitute professional insurance, legal, or financial underwriting advice. Property insurance regulations and policy terms vary by state and carrier. Always consult with a licensed independent insurance agent or certified financial advisor prior to making changes to your coverage.