Cheap Home Insurance Review: Saving Money vs. Losing Protection
Every homeowner loves finding a great deal. With inflation driving up utility bills, grocery costs, and mortgage interest rates, shopping online for cheap homeowners insurance feels like a smart, proactive financial move. When an online insurance aggregator displays a quote that is $500 or $800 cheaper than your current policy, it is tempting to switch immediately and celebrate your annual savings.
However, in the world of property insurance, there is a vital distinction between cheap insurance and affordable, high-value insurance. Many ultra-cheap insurance quotes achieve their low monthly price tags by quietly stripping away essential protections, capping claim payouts, assigning Actual Cash Value (ACV) depreciation penalties, and inflating out-of-pocket deductibles in dense fine print.
What feels like a victory today can easily turn into a financial nightmare when a severe windstorm, electrical fire, or pipe burst damages your home. If a $40 monthly savings on your policy leads to a $20,000 unpaid claim denial after a storm, you haven't saved money—you have unknowingly put your family's single largest financial asset at risk. Let us conduct a thorough review of cheap home insurance policies so you can cut costs safely without giving up vital protection.
I learned the difference between cheap insurance and good insurance the hard way. Five years ago, I switched my home insurance to a budget online carrier that promised to cut my annual rate by 35%. I was thrilled with the monthly savings. But eighteen months later, a severe hailstorm ruined my roof. When the claim adjuster arrived, I discovered my bargain policy carried a 2% windstorm deductible ($8,000 out of pocket) and valued my roof on an Actual Cash Value basis. I ended up paying $6,500 out of my savings to replace a roof that I thought was fully insured. That painful experience proved that saving $30 a month isn't worth losing thousands when you need help most, and I want to share these insights so you stay fully protected.
The Hidden Traps Inside Cheap Home Insurance Policies
Budget insurance companies often advertise strikingly low rates to attract new customers. But to maintain their corporate profit margins, they cut corners in critical policy areas:
- Actual Cash Value (ACV) Depreciated Payouts: Ultra-cheap policies routinely default to ACV for personal property and roof structures. ACV subtracts depreciation for age and wear, leaving you with pennies on the dollar during a claim.
- Hidden High Deductible Jumps: Cheap monthly quotes frequently hide a $5,000 flat deductible or a 5% percentage-based storm deductible that requires massive cash checks during repairs.
- Stripped-Down Dwelling Coverage Limits: Budget quotes often under-calculate your home's physical rebuilding costs, setting dwelling limits far below actual local contractor material and labor rates.
- Excluded Perils and Sub-Limit Caps: Cheap plans systematically exclude water backup, sewer overflows, mold remediation, and enforce strict $1,000 sub-limits on electronics and jewelry.
The Emotional Toll of Being Underinsured
Carrying a bare-bones, cheap insurance policy creates a persistent background noise of anxiety that ruins your peace of mind as a homeowner:
Storm season dread—listening to heavy rain or windstorms while worrying that a damaged roof will lead to a rejected claim—causes constant mental stress. Furthermore, the shock and betrayal during claims (realizing after a disaster that your "bargain" policy won't cover basic repairs) creates immense financial shock and family strain.
Homeowners insurance isn't supposed to be a lottery ticket where you hope nothing goes wrong—it is supposed to be an unshakeable wall protecting your family's future. When every thunderstorm makes you stare at your ceiling wondering if your cheap policy will actually pay out, that policy isn't saving you money; it is charging you an emotional price every single day. True financial wisdom is finding legitimate discounts while keeping your protective wall 100% solid.
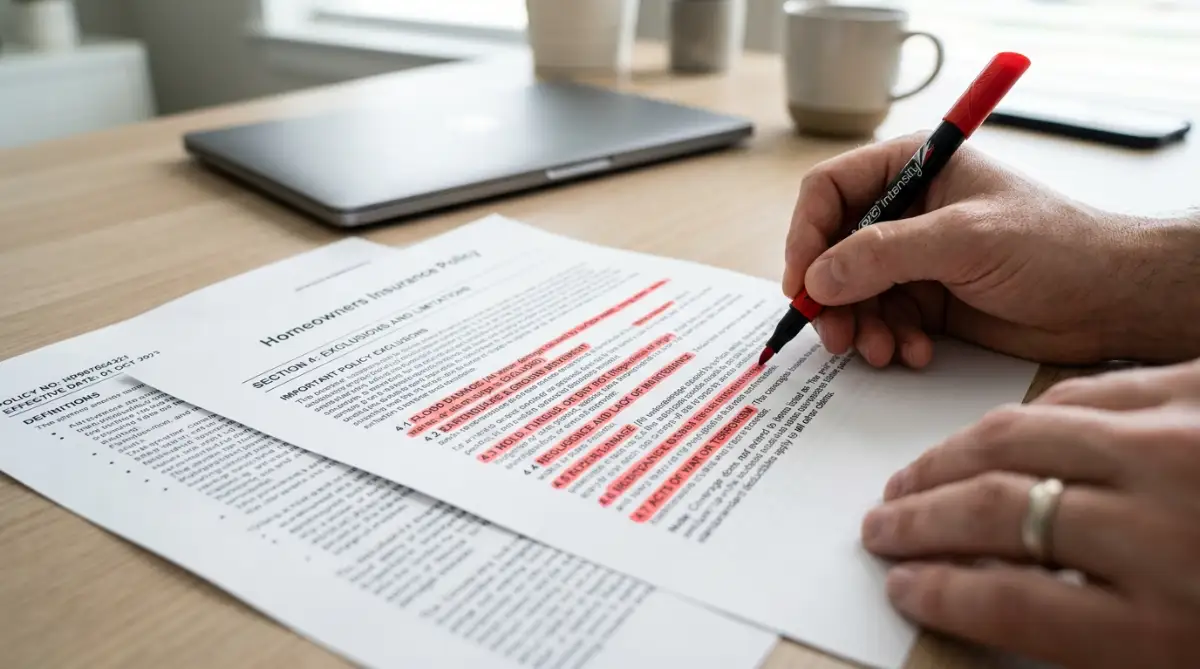
Visual Insight: How to Get Cheap Home Insurance Safely
Watch this clear and practical video guide from Finder to learn how to lower your home insurance bills safely, claim valid policy discounts, and avoid dangerous coverage gaps!
Saving Money vs. Losing Protection: Where to Cut Costs Safely
You can achieve significant annual savings on your home insurance without compromising your family's safety. Contrast these smart savings strategies against dangerous cost-cutting moves:
Managing Emergency Cash Buffers and Debt Health
Smart insurance management goes hand-in-hand with sound household financial planning:
1. Building a Reserve for Higher Deductibles: If you choose a higher flat deductible (e.g., $1,500) to lower your annual premium, maintain liquid cash in reserve to cover that sum during a claim. Read our complete guide on building a bulletproof emergency fund fast to establish a cash cushion before modifying deductible limits.
2. Improving Credit Scores for Rate Reductions: Insurers calculate premiums using credit-based insurance scores in most states. Paying down credit card debt directly improves your credit rating and qualifies you for cheaper insurance pricing tiers! Reviewing tips on improving your credit score quickly allows you to streamline monthly obligations and lower your insurance rates.
My Personal Pro Tip: When I optimized my insurance policy, I focused on bundling rather than lowering my coverage. If you are managing other financial commitments like student loans, checking out smart student loan and financing options will help you protect your total household cash flow.
3. Avoiding Predatory Repair Debt: Taking out rushed personal loans to pay property deductibles without comparing terms can cause severe financial distress. Review standard personal loan mistakes you must avoid before taking on repair debt, and make sure you understand what happens if you miss a personal loan payment to safeguard your credit history during property emergencies.
For more foundational advice on property selection and safety, check out our complete guide to initial home policies.
Reclaiming Control Over Your Sanctuary
At the end of the day, your home should be a place of safety, warmth, and family joy—not a source of hidden financial anxiety. When you choose an insurance policy that balances fair pricing with solid Replacement Cost Value (RCV) protection, you take total command of your property's security. You can celebrate milestones, enjoy weekends with family, and sleep soundly knowing your home is 100% safe.
I know how enticing cheap insurance quotes look on a computer screen, but taking the time to verify your coverage limits ensures true peace of mind. Stay protected and enjoy your home!
Quick Guide: Cheap Insurance Do's and Don'ts
Frequently Asked Questions on Cheap Home Insurance
Is ultra-cheap home insurance worth the risk?
No, ultra-cheap insurance policies often rely on hidden exclusions, ACV roof depreciation, and high deductibles that can leave you with thousands in out-of-pocket expenses after a disaster.
How can I lower my home insurance premium safely?
You can lower your premium safely by bundling your auto and home policies, installing smart safety devices, and adjusting your flat deductible while keeping emergency cash reserves.
What does Actual Cash Value (ACV) mean on a home policy?
ACV pays out the depreciated market value of damaged items based on age and wear, meaning you will receive far less than what it costs to buy brand-new replacements.
Why do online insurance aggregators show such cheap quotes?
Aggregators often display stripped-down baseline quotes with minimal coverage limits and high deductibles to look attractive, before adding mandatory fees or exclusions later.
Does a good credit score help lower home insurance rates?
Yes, insurance carriers use credit-based insurance scores in most states to determine premium rates, meaning higher credit scores frequently translate to cheaper insurance bills.
Disclaimer: This article is published exclusively for educational and informational purposes. It does not constitute professional insurance, legal, or financial underwriting advice. Property insurance rules and policy terms vary by state and carrier. Always consult with a licensed independent insurance agent or certified financial advisor prior to purchasing or modifying home insurance coverage.