Home Insurance Deductibles Explained: How to Save Money Safely
Every year, millions of homeowners face a familiar moment of anxiety when their annual insurance renewal notice arrives in the mail. You open the envelope hoping for a steady, manageable rate, only to find that your premium has jumped by hundreds of dollars. You have never filed a claim, you keep your roof in good repair, and you pay your bills on time, yet your housing costs continue to climb.
Searching for ways to lower your annual bill often leads to one immediate recommendation from agents and online tools: raise your home insurance deductible. Choosing a higher deductible instantly lowers your monthly premium, making your policy look remarkably cheap on paper. However, raising your deductible without fully understanding how it works during an emergency is one of the most dangerous financial gambles a homeowner can make.
A deductible is not just an abstract number on an insurance policy document; it is the exact out-of-pocket cash check you must write before your insurance carrier pays a single penny toward rebuilding your house. Understanding how deductibles operate, calculating your break-even point, and setting safe financial boundaries empowers you to cut your home insurance costs safely without leaving your family exposed during a storm.
Three years ago, when my annual home insurance premium jumped unexpectedly, I called my agent and hastily instructed him to raise my policy deductible from $1,000 to $2,500. I was thrilled to see my monthly bill drop by $35. But nine months later, an intense hailstorm smashed my roof shingles. When the roofing contractor handed me an emergency repair estimate and told me I had to write a $2,500 cash check before work could begin, my stomach dropped. I realized I didn't have $2,500 liquid cash saved. Saving $35 a month had backed me into a corner during an actual emergency, and I want to help you avoid that exact same financial vulnerability.
What Is a Home Insurance Deductible and How Does It Work?
In simple terms, an insurance deductible is the pre-agreed amount of money you agree to pay out of your own pocket toward a covered property claim before your insurance company begins paying for repairs.
For example, if a severe windstorm causes $8,000 worth of structural damage to your home and your policy carries a $1,000 flat deductible, you pay the first $1,000 directly to the repair contractor. Your insurance company then provides a settlement check for the remaining $7,000. Deductibles exist to prevent policyholders from filing dozens of tiny, minor claims (like a $200 broken window) that inflate administrative processing costs for insurance companies.
Flat Dollar Deductibles vs. Percentage Deductibles
One of the biggest hidden traps in modern property insurance is failing to distinguish between flat dollar deductibles and percentage-based deductibles:
In storm-prone regions, insurers routinely mandate separate percentage deductibles for hurricane, windstorm, or hail claims. Always inspect your policy Declarations Page to verify whether your deductible is a flat dollar figure or a percentage cap tied to your home's total reconstruction value.
The worst part about carrying a percentage deductible you can't afford isn't the policy paperwork—it's how you feel when severe weather warnings pop up on your phone screen. Watching dark clouds roll in while quietly praying that hail won't dent your roof because you don't have $8,000 sitting in your checking account creates an exhausting mental weight. Re-structuring your deductible so it matches your actual bank account brings back true peace of mind during storm season.
Visual Insight: Understanding Homeowners Insurance Deductibles
Watch this helpful video guide to better understand how homeowners insurance deductibles work and how adjusting them impacts your coverage and out-of-pocket expenses.
The Self-Insurance Break-Even Calculation
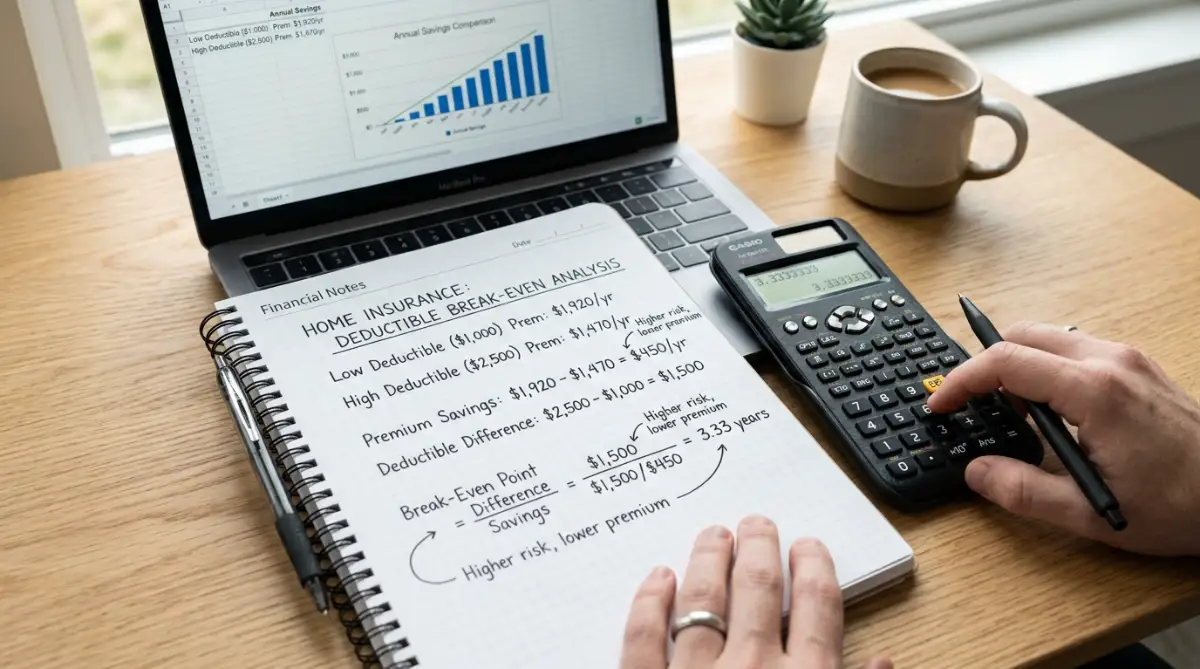
Before raising your deductible to save on annual premiums, perform a simple Break-Even Calculation. This math reveals exactly how many years you must remain claim-free for a higher deductible to yield net profit:
Low Deductible Option: $1,000 Deductible | Premium: $1,300/year
High Deductible Option: $2,500 Deductible | Premium: $1,000/year
Annual Premium Savings: $300 | Extra Out-of-Pocket Risk: $1,500
Break-Even Formula: $1,500 Risk ÷ $300 Annual Savings = 5 Years
If you remain claim-free for five full years, your accumulated $300 annual savings ($1,500 total) completely offsets your increased out-of-pocket risk. Every claim-free year beyond year five is pure savings for your household budget!
My Personal Pro Tip: When I evaluate my own insurance coverage, I always make sure my deductible aligns with my actual liquidity. If I want to take a higher deductible to lower my monthly premium, I first check that I can comfortably cover that amount without touching my core living expenses. If you need help managing loans or financial buffers, reading our guide on improving your financial profile can prepare you for better rates.
However, never raise your deductible unless you hold liquid cash in reserve to cover that out-of-pocket sum immediately. Take time to read our complete guide on building a bulletproof emergency fund fast to construct a liquid cash buffer before increasing your policy deductible limits, or review alternative financing paths like smart borrowing options to keep your cash flow secure.
Severe Deductible Traps That Can Drain Your Savings
Avoid these widespread, costly policy misunderstandings:
The Cumulative Deductible Illusion: Unlike health insurance where deductibles reset annually, property insurance deductibles apply per claim incident! If three separate hail storms hit your home in a single summer, you must pay your full deductible three separate times.
Filing Small Claims Near Deductibles: Filing an $1,100 fence repair claim with a $1,000 deductible nets you a tiny $100 payout from your carrier but logs a claim on your C.L.U.E. national record, triggering multi-year premium surcharges that cost thousands overall. For guidance on structuring your home assets safely, review our insights on selecting your home policy correctly.
Ignoring Mortgage Lender Maximum Caps: Mortgage lenders enforce strict limits on how high you can set your insurance deductible (usually capped at $2,500 or $5,000). Setting an excessively high deductible can violate your mortgage agreement.
Managing Financial Health and Debt Alignment
Protect your credit score and household budget by avoiding risky financial moves during property repairs:
1. Debt Consolidation for Insurance Rate Reduction: In most states, insurers calculate premiums using credit-based insurance scores. Paying down high-interest credit card debt directly improves your credit rating and lowers your annual home insurance rate! Studying smart financial management tools and digital setups helps you streamline monthly debt and qualify for cheaper insurance tiers.
2. Avoiding High-Interest Emergency Debt: Taking out rushed personal loans to pay property deductibles without checking interest rates causes long-term financial strain. Review standard personal loan mistakes you must avoid before borrowing, and make sure you understand what happens if you miss a personal loan payment to protect your credit health during emergency home repair periods.
Reclaiming Control Over Your Sanctuary
At the end of the day, your home should be a place of relaxation, safety, and family warmth—not a source of hidden financial traps. When you align your insurance deductible with your real liquid savings, perform the break-even math, and keep an emergency cash cushion ready, you take total command of your family's financial security. You can sleep peacefully through any storm, knowing your home is fully protected.
I feel a deep sense of security knowing my own household is structured around realistic deductibles, and I truly hope these insights help you protect your home and hard-earned savings with absolute confidence.
Quick Guide: Deductible Do's and Don'ts
Helpful Q&A for Policyholders
What is the most common deductible amount for standard homes?
A flat $1,000 deductible is the most popular choice for standard single-family homes in the United States, offering an ideal balance between affordable monthly premiums and manageable out-of-pocket risk.
Can I change my deductible amount mid-policy?
Yes! You can contact your insurance agent to adjust your deductible at any time during your policy term. Raising your deductible mid-term will result in a pro-rated premium refund or credit.
What is a percentage deductible on home insurance?
A percentage deductible calculates your out-of-pocket payment as a percentage of your total dwelling coverage limit rather than a fixed dollar amount, often applying specifically to wind or hurricane claims.
Do home insurance deductibles apply per year or per claim?
Unlike health insurance, home insurance deductibles apply separately to every single individual claim you file, meaning multiple storms in one year require paying multiple deductibles.
Will raising my deductible lower my monthly home insurance premium?
Yes, choosing a higher deductible reduces the insurer's risk exposure, which results in a lower monthly or annual premium cost for your policy.
Disclaimer: This article is published exclusively for educational and informational purposes. It does not constitute professional insurance, legal, or financial underwriting advice. Property insurance regulations, mortgage rules, and policy deductible structures vary by state and carrier. Always consult with a licensed independent insurance agent or certified financial advisor prior to making changes to your coverage limits.