How to Reduce Medical Bills Without Sacrificing Quality Care 1. Understanding the Hidden Economics of US Healthcare
Navigating the healthcare system in the United States is frequently cited as one of the most stressful financial experiences an individual or family can face. Even for Americans with comprehensive health insurance coverage, an unexpected hospital visit, outpatient procedure, or emergency room evaluation can quickly result in confusing, multi-page medical invoices carrying astronomical balances. When faced with a daunting medical bill, I watched many people experience panic paying—emptying emergency savings accounts, putting high balances on high-interest credit cards, or borrowing money out of fear that their credit score will be ruined. However, patient advocates and financial experts emphasize a reality: medical bills are rarely set in stone, and up to 80% of hospital invoices contain billing errors.
To reduce your medical bills effectively, I learned that you must first understand why healthcare pricing in America is so chaotic and unstandardized. Unlike standard retail markets where prices are transparently displayed, healthcare institutions operate using proprietary pricing databases known as Charge masters. Charge master prices are grossly inflated list prices set by hospitals—often 300% to 1,000% higher than the actual cost of providing the service or the reimbursement rates accepted from Medicare. If you are uninsured, underinsured, or receiving out-of-network care, hospitals will initially bill you based on these inflated rates unless you challenge them actively. By utilizing proactive patient advocacy and systematic auditing, I know you can significantly lower your medical expenses while receiving top-tier clinical care.
Reducing healthcare expenses does not require accepting inferior medical care or foregoing necessary procedures. With proactive patient advocacy, systematic auditing, knowledge of consumer protections, and assertive negotiation strategies, you can slash your expenses safely. To analyze broader healthcare spending metrics and economic policies, explore our comprehensive analysis of healthcare economics and medical debt dynamics.
Primary Reasons Medical Bills Are Overinflated
- Up coding: Assigning a higher-level, more expensive CPT code to a routine or simple medical procedure.
- Unbundling: Billing separately for individual supplies or procedures that should legally be grouped together under a single comprehensive billing code.
- Duplicate Charges: Billing a patient twice for the same medication, blood test, or physical therapy session.
- Mishandled Insurance Claims: Hospital billing departments failing to properly submit required diagnostic codes to your insurer, leading to automatic claim denials.
2. Step 1: Always Request an Itemized Bill Before Paying
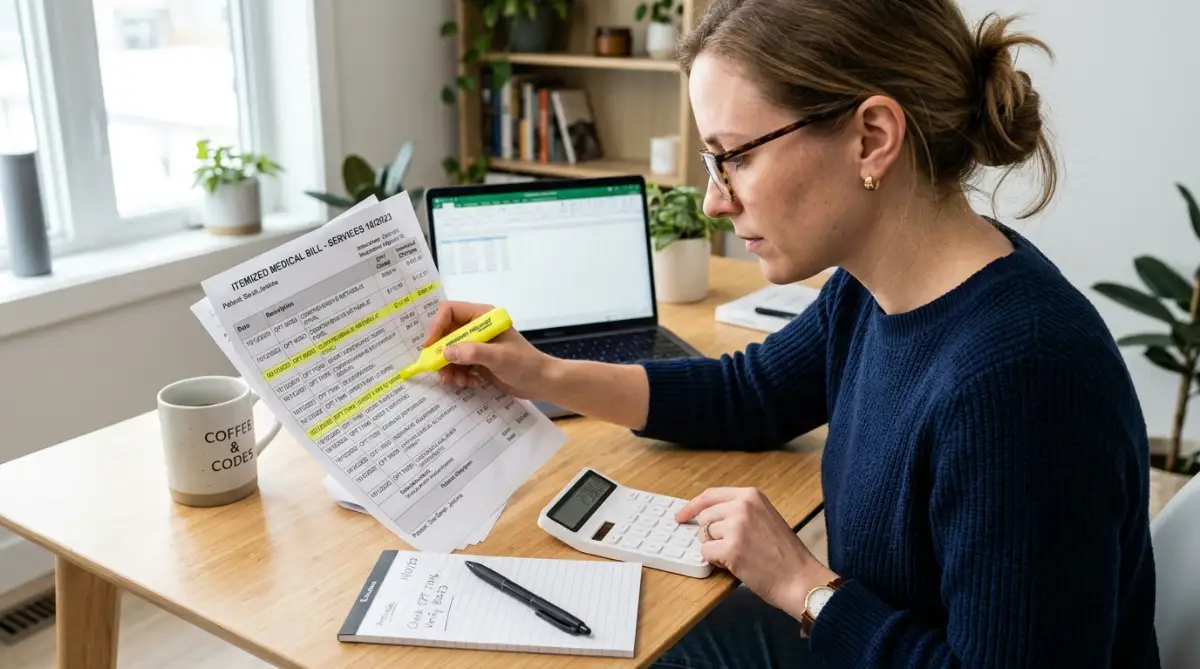
The single most important rule in medical billing advocacy is simple: never pay a summary medical bill. A summary bill provides only a vague total figure without disclosing specific line items. When you receive a bill, I recommend contacting the billing department immediately to request a complete, itemized invoice including all CPT and HCP CS codes.
My Personal Pro Tip
When I review medical invoices for my family, I always ask for the electronic itemized text file or PDF breakdown. In my experience, examining the individual codes line-by-line is the only foolproof way to catch hidden administrative markups and unbundled lab fees.
Watch: Expert Strategies on How to Negotiate Medical Bills
To gain expert strategies on communicating with hospital billing departments, spotting billing errors, and securing zero-interest payment plans, watch this detailed video tutorial:
Learn more about managing your personal health insurance records and patient rights in our essential guide to health insurance navigation and medical record management.
3. Step 2: Harnessing Hospital Charity Care Policies
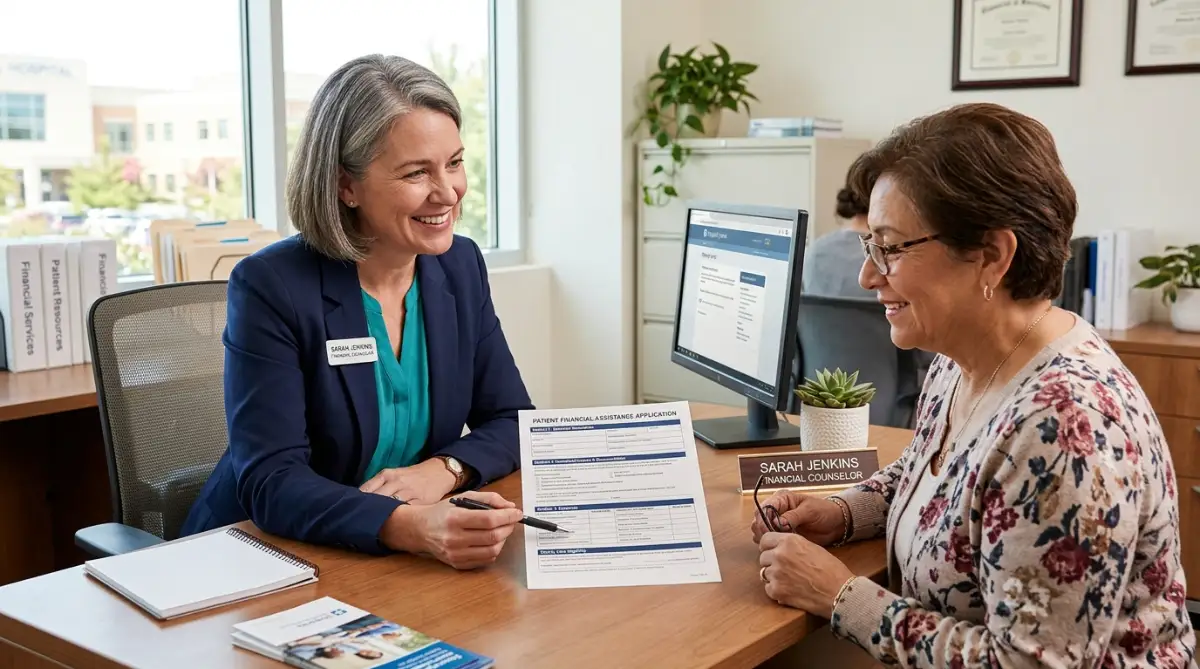
One of the best-kept secrets in healthcare financing is Charity Care. Under Section 501(r) of the Internal Revenue Code, all non-profit hospitals in the United States are legally required to maintain formal Financial Assistance Policies to retain their tax-exempt status. Charity care policies provide substantial discounts—or complete debt forgiveness—for patients meeting specific income thresholds based on the Federal Poverty Guidelines.
Many non-profit hospitals offer partial or full assistance to households earning up to 200%, 300%, or even 400% of the federal poverty line. If your income falls within these parameters, you can apply directly through the hospital's patient financial services office. By submitting proof of income, tax returns, and hardship declarations, you can legally erase or dramatically minimize your out-of-pocket obligation without impacting your credit score.
Step 3: Negotiating Cash Discounts and Payment Plans
If you do not qualify for hospital charity care, you can still negotiate substantial discounts directly with billing supervisors. Medical providers would far rather collect a reduced cash payment directly from a patient than sell delinquent debt to a collections agency for pennies on the dollar. Always ask the billing department for their cash self-pay rate if you settle immediately.
If you cannot afford a lump-sum payment, request a long-term, zero-interest payment plan. Most hospitals will allow you to pay as little as $25 to $50 per month over an extended duration without interest or credit penalties. As long as you make regular monthly payments on an agreed plan, the hospital cannot send your account to debt collection agencies.
To discover additional stress-management and financial wellness resources, explore our guide on proven wellness strategies for managing healthcare and academic stress.
If you are exploring professional career pathways in healthcare administration or patient advocacy, review our guide to high-paying healthcare careers and patient advocacy support roles.
 4. Strategic Checklist for Patient Advocacy
Before making any payment toward a medical bill, execute this 5-step advocate checklist to protect your financial resources and avoid unnecessary payments.
- Do Not Panic Pay: Take a deep breath. Medical debt collection laws provide strict grace periods before bills can affect your credit report.
- Request an Itemized CPT Bill: Review every line item for duplicate charges, unbundled services, and coding errors.
- Apply for Non-Profit Hospital Charity Care: Check if your income qualifies you for 100% or partial debt write-offs under Section 501(r).
- Negotiate Cash Rates or Zero-Interest Plans: Offer a discounted lump sum or establish an affordable monthly interest-free schedule.
- Utilize Prescription Cash Discounts: Compare generic cash prices across online discount pharmacies before filling prescriptions.
To ensure your overall financial health remains stable while managing medical obligations, read our guide on improving your financial standing and protecting your credit score.
5. Empowering Yourself as a Healthcare Consumer
Receiving high-quality medical care should never require sacrificing your family's financial stability or peace of mind. By shifting your perspective from a passive patient to an informed, proactive healthcare consumer, you gain the power to challenge incorrect bills, leverage federal consumer protections, and negotiate fair prices.
I always remind my readers that medical bills are negotiable instruments, billing errors are common, and financial assistance programs exist to protect patients. In my own journey managing family healthcare costs, taking the time to audit statements and speak directly with billing supervisors completely changed our financial security. Take control of your medical bills today: audit your statements, ask bold questions, assert your rights, and protect both your health and your financial future!
6. Additional Resource Navigation
To further support your financial planning and consumer rights education, explore our verified resource collection:
- Understanding student loans and consumer credit options
- Navigating home insurance policies and financial protection strategies
7. Frequently Asked Questions
Can unpaid medical bills hurt my credit score immediately?
No, under recent credit reporting rules, medical debt must remain unpaid for at least 365 days before appearing on credit reports, giving you time to resolve billing disputes.
What is an itemized medical bill and why is it important?
An itemized bill breaks down every single supply, medication, and CPT code used during your visit, allowing you to catch duplicate charges and billing errors.
Do for-profit hospitals offer charity care programs?
While federal law mandates charity care primarily for non-profit 501(r) hospitals, many for-profit health systems also maintain internal financial assistance policies.
How can I find generic equivalents for expensive brand-name drugs?
You can ask your physician to prescribe FDA-approved generic equivalents or check digital pharmacy discount tools to find significantly lower cash prices.
What should I do if a hospital sends my bill to collections unfairly?
Contact the hospital billing department immediately to verify whether your account was sent in error while a financial assistance or itemized dispute was pending.
8. Disclaimer
The information provided in this article is for educational, informational, and patient advocacy purposes only and does not constitute formal legal, financial, or medical advice. Medical billing laws, charity care guidelines, insurance regulations, and debt protection statutes vary by state and healthcare provider. Readers are strongly encouraged to consult directly with certified medical billing advocates, legal professionals, or official hospital billing departments before making binding financial settlements.